

October 2026 VAT Advance Notice: If Your Sales Have Declined, Check the 1/3 Threshold First
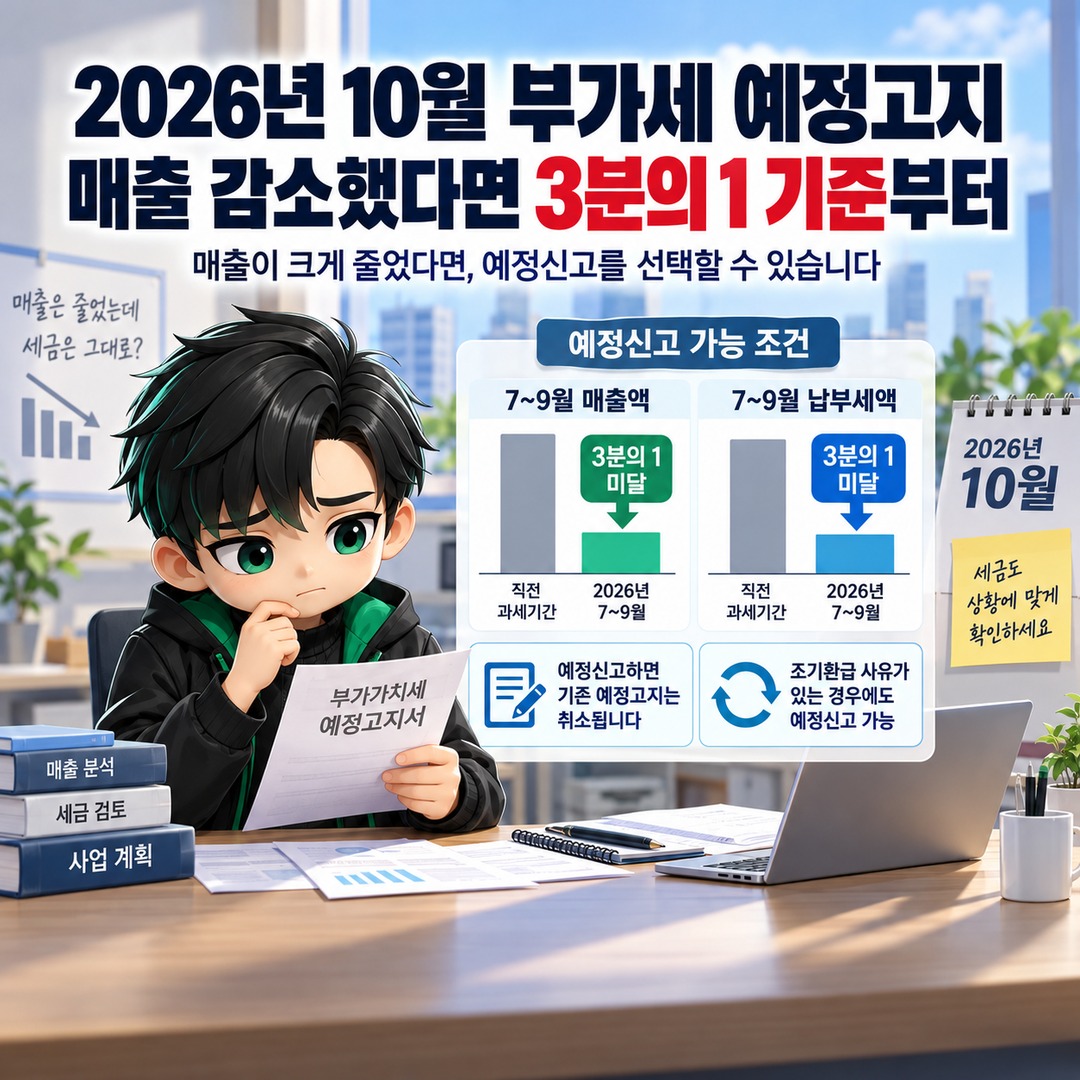
Even if you have received a October 2026 VAT advance payment notice, you may choose to file an interim VAT return instead of paying the amount stated in the notice if your sales have fallen significantly. If your sales or VAT payable for 7–September are below 1/3 of the previous tax period's amount, or if you qualify for an early refund, you may file an interim return. Filing the return cancels the original advance payment notice.
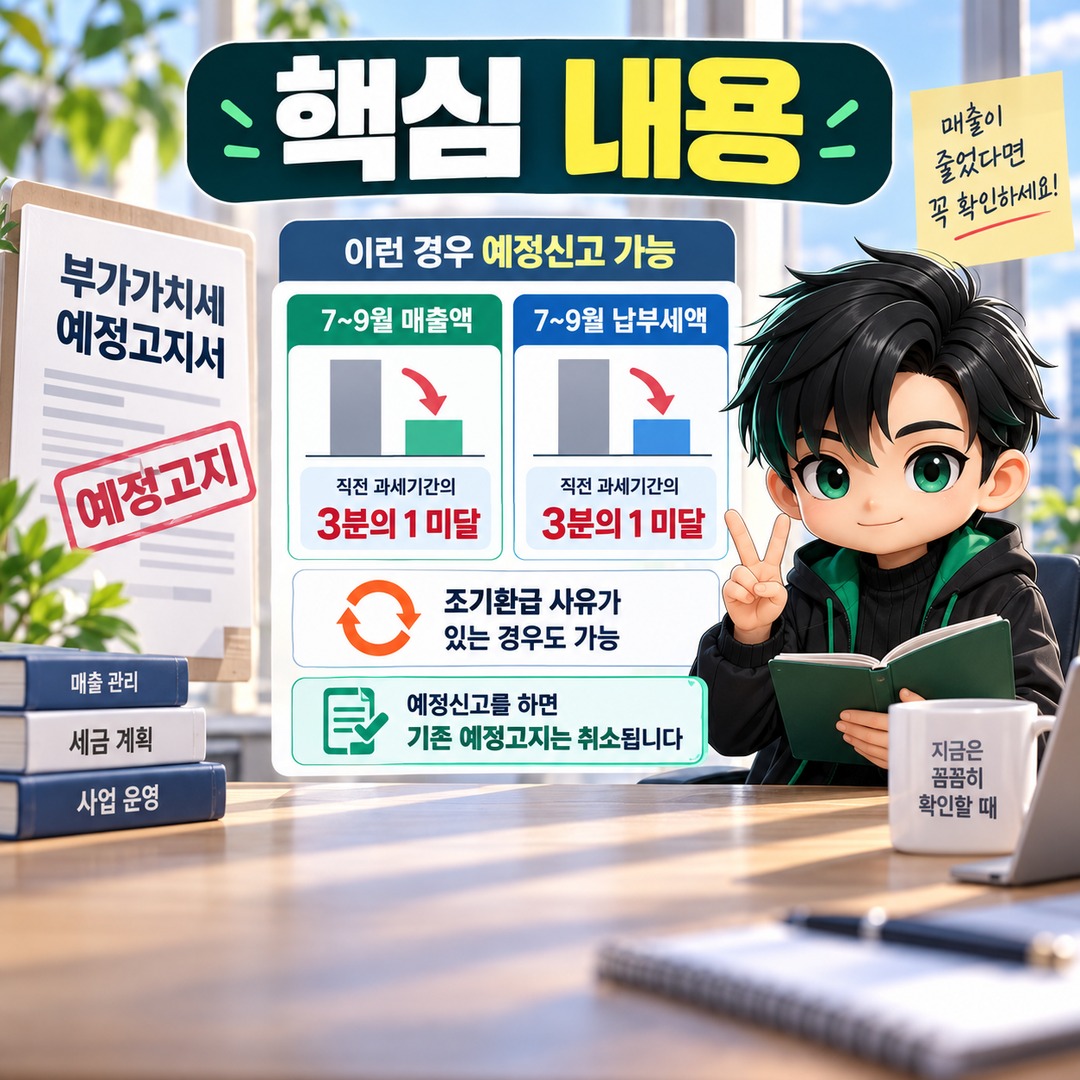
However, the amount stated in the notice does not automatically decrease simply because your sales have fallen slightly.
In 2026, the deadline for filing an interim VAT return also differs from the payment deadline for an advance VAT notice. Sole proprietors experiencing declining sales should first determine which procedure applies and which deadline they must meet.
Why Does the VAT Amount in the October Notice Differ from Current Sales?
An advance VAT payment notice does not recalculate the tax each time based on actual sales during 7–September of the current year.
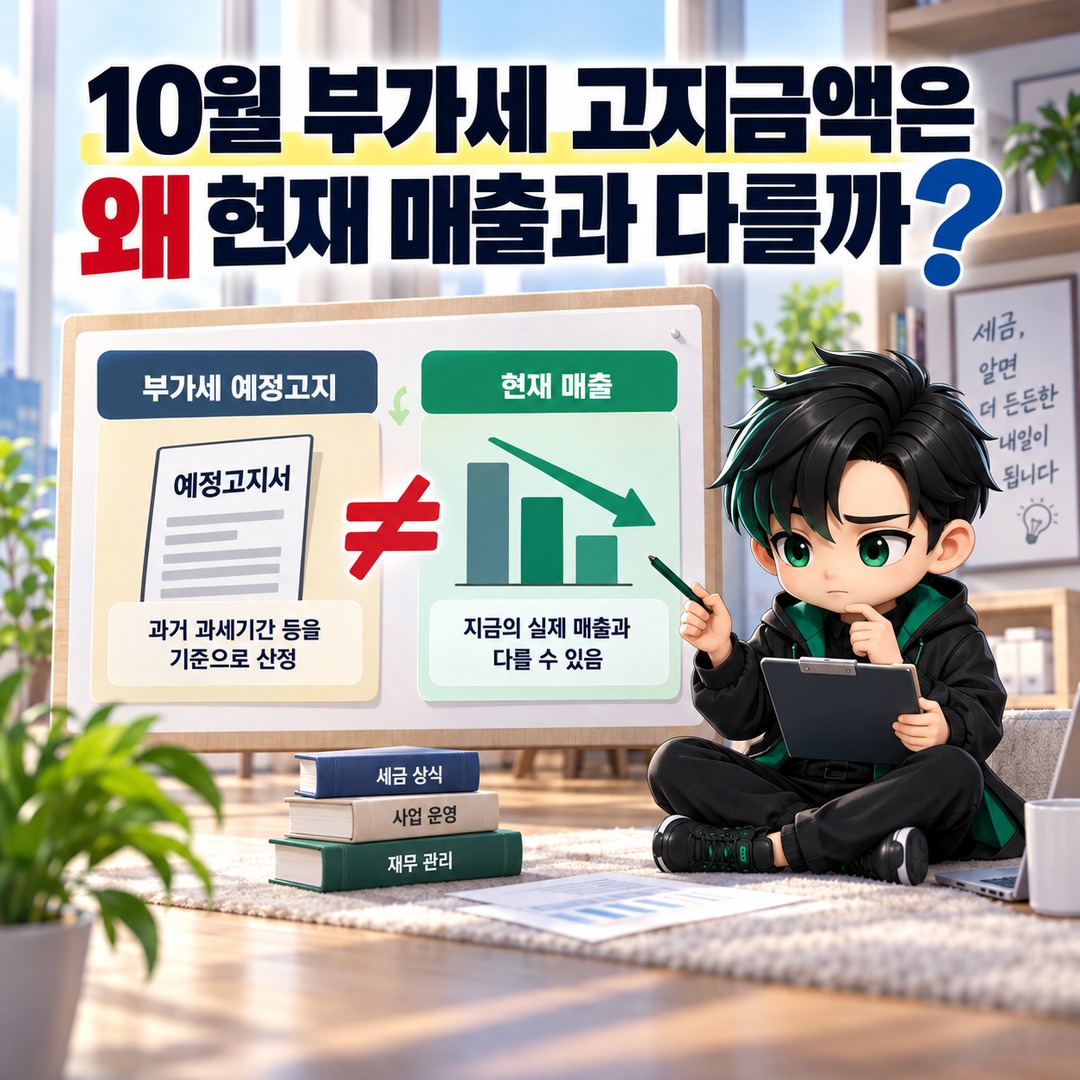
The National Tax Service (NTS) issues advance payment notices to individual general VAT taxpayers and certain small corporate taxpayers based on the VAT paid during the previous tax period.
The calculation basis for the October 2026 advance payment notice is as follows.
Reference tax period: 2026-01-01–June 30
Advance VAT amount: 50% of the VAT paid during the previous tax period
Current interim tax period: 2026-07-01–September 30
For example, if the VAT paid for the first half of 2026 was KRW 3,000,000, the calculated advance payment amount would be KRW 1,500,000.
Calculation example: KRW 3,000,000 × 50% = KRW 1,500,000
Therefore, even if sales have declined significantly in the second half of the year, a high VAT payment in the first half may make the current advance payment notice seem disproportionately large compared with the business's present circumstances.
One option worth considering in this situation is filing an interim VAT return.
How Much Must Sales Decline to Qualify for an Interim VAT Return?
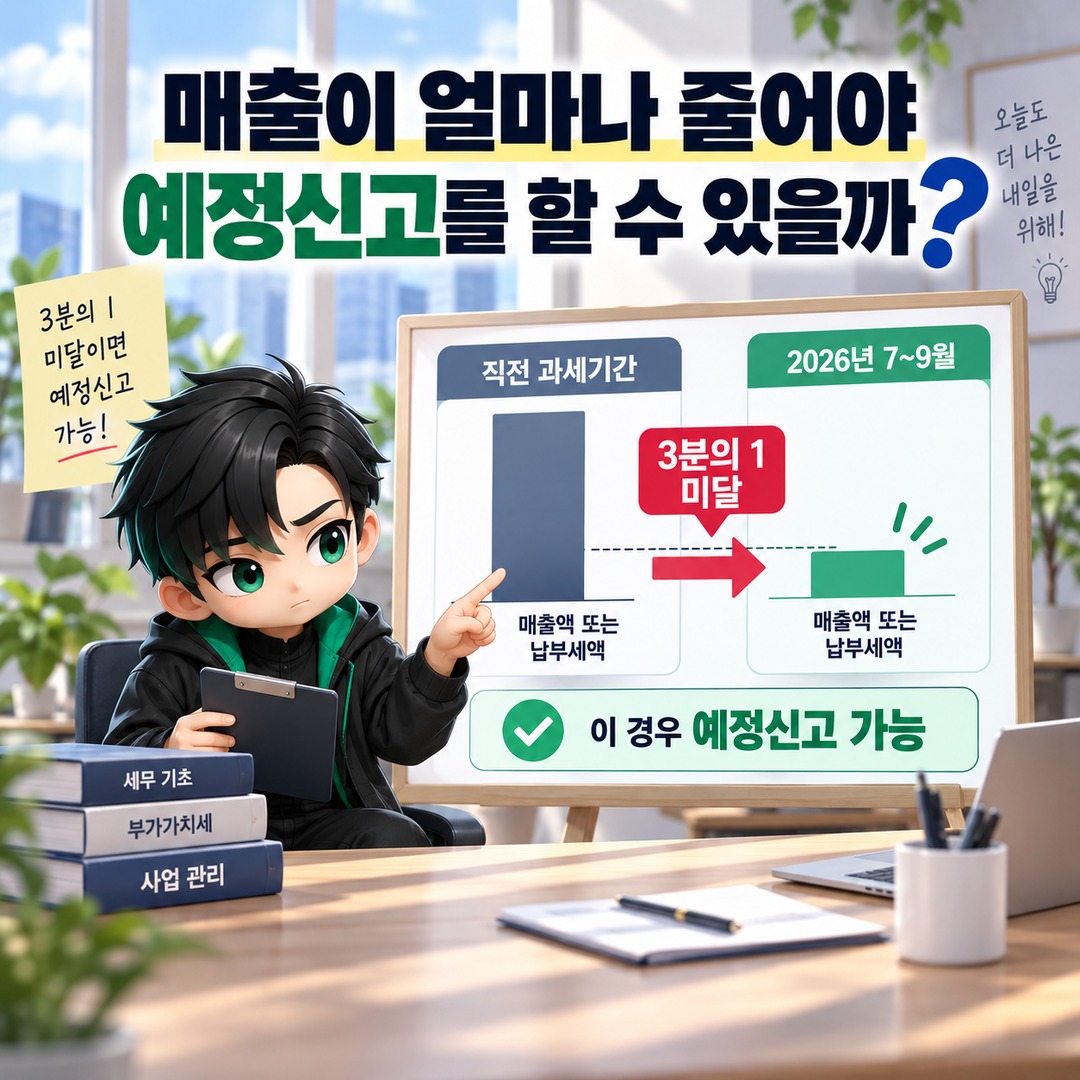
According to the criteria announced by the NTS on 2026-10-05, businesses subject to advance VAT notices may file an interim return if their sales or VAT payable for 7–September are below 1/3 of the amount for the previous tax period.
The important point is that eligibility is not determined simply by whether sales have declined compared with the previous month.
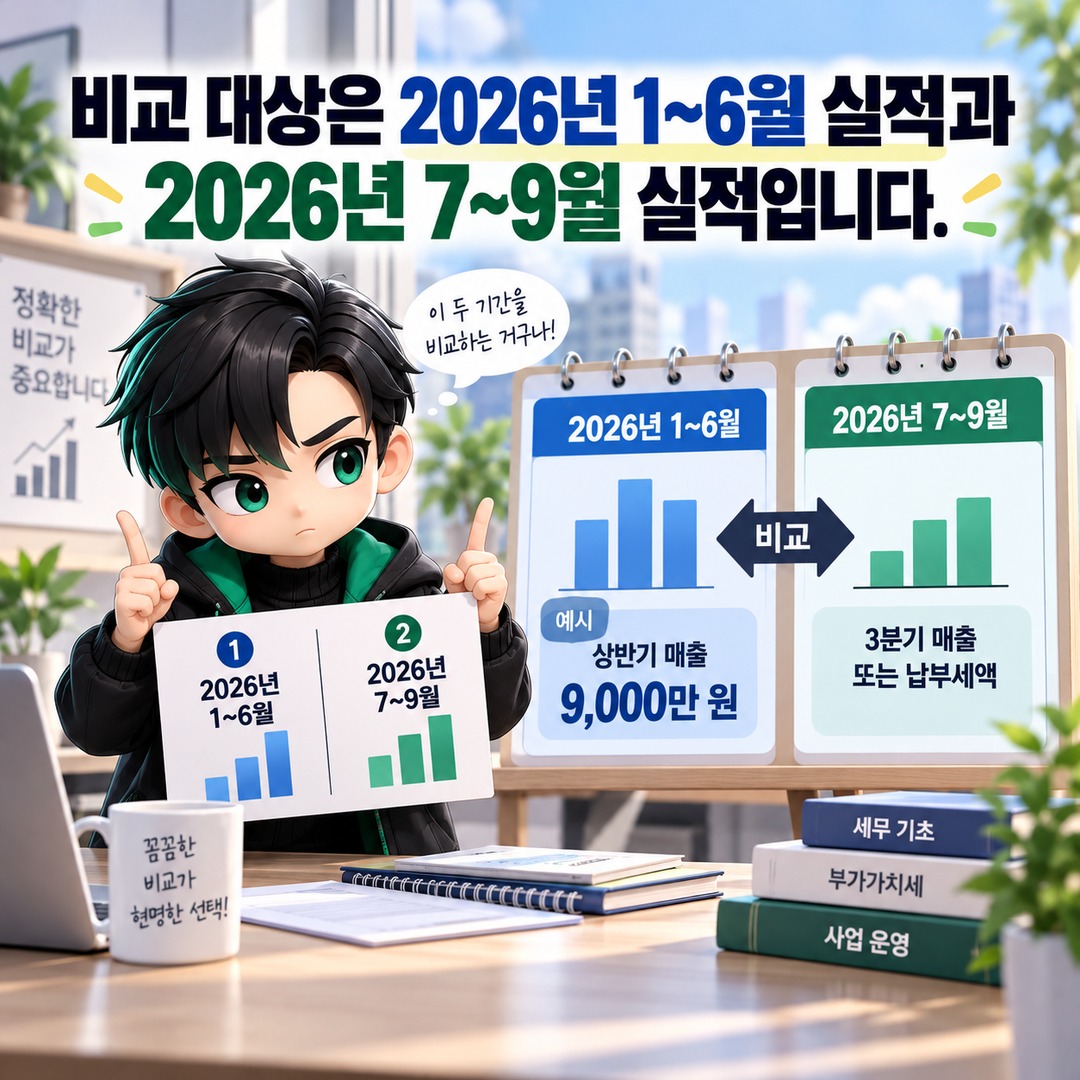
The Comparison Is Between Results for 1–June of 2026 and 7–September of 2026.
For example, suppose sales in the first half of the year were KRW 90,000,000.
| Sales for 7–September of 2026 | Assessment Against the 1/3 Threshold |
|---|---|
| KRW 20,000,000 | Below the threshold |
| KRW 30,000,000 | Equal to the threshold |
| KRW 40,000,000 | At or above the threshold |
Author's calculation: First-half sales of KRW 90,000,000 × 1/3 = KRW 30,000,000
In this example, if sales for 7–September were KRW 20,000,000, the business would meet the sales-based eligibility requirement for filing an interim return.
By contrast, if sales were KRW 30,000,000, they would be exactly 1/3 of the reference amount and therefore would not satisfy the requirement of being strictly below the sales threshold.
However, even if the sales-based requirement is not met, the business can separately examine whether it qualifies based on VAT payable or eligibility for an early refund.
Sales should be compared using the taxable supply value, excluding VAT. Actual eligibility to file must be determined by reviewing the business's tax records and VAT payable.
What Happens to the Original Notice If You File an Interim Return?
When an interim VAT return is properly filed, the original advance VAT assessment is canceled.
If a business that has received an advance payment notice meets the eligibility requirements because of declining sales or other qualifying circumstances and files an interim return, its VAT will be calculated using its actual business results for 7–September.
It is important to understand the distinction between an advance VAT notice and an interim VAT return.
An Advance VAT Notice Is Calculated Using Previously Paid Tax, While an Interim Return Reflects Actual Output VAT, Input VAT, and Other Relevant Amounts for the Current Interim Period.
For example, even if the amount stated in the notice is KRW 1,500,000, filing a return based on actual results for 7–September does not necessarily mean the VAT payable will be KRW 1,500,000.
The actual tax liability varies depending on taxable sales, deductible input VAT, and applicable tax credits or reductions.
Therefore, a decline in sales does not necessarily mean VAT will decrease by the same percentage.
Furthermore, the notice is not automatically canceled simply because sales have declined. If the business meets the requirements for filing an interim return, it must actually submit the return within the filing deadline.
2026-10-26 or November 2: Which Deadline Must You Meet?
For October 2026 VAT, the deadlines differ between businesses filing interim returns and those paying the amounts stated in their advance payment notices.
According to the NTS guidance for October 2026, the schedule is as follows.
| Category | Deadline |
|---|---|
| Interim VAT return filing and payment | October 26 (Monday) |
| Advance VAT notice payment | November 2 (Monday) |
| Businesses covered by a separate automatic payment deadline extension | December 28 (Monday) |
Businesses choosing to file an interim return must complete the filing process by October 26.
By contrast, businesses that are ordinarily subject to advance VAT notices and do not file interim returns may pay the assessed amount by November 2.
For 2026, the NTS extended the advance VAT payment deadline across the board to the end of October. Because October 31 fell on a Saturday, the actual payment deadline was set at November 2.
The NTS also automatically extended the payment deadline to December 28 for designated businesses, including certain businesses in areas affected by heavy rainfall and businesses affected by Homeplus-related circumstances.
This extension does not automatically apply to every business experiencing declining sales. Each business must verify whether it is covered.
What Should You Check First on Hometax?
Sole proprietors experiencing declining sales can first check whether they are subject to an advance VAT notice and review the assessed amount through Hometax.
The inquiry procedure provided by the NTS is as follows.
1. Log in to Hometax.
2. Navigate to `Tax Filing → VAT Filing`.
3. Under `View Filing Assistance Materials`, check whether you are subject to an advance VAT notice and review the assessed amount.
4. Compare sales and VAT payable for 1–June and 7–September of 2026.
5. If you meet the eligibility requirements for an interim return, file by October 26 using your actual business results.
You can also review the notice under `My Hometax → Payments and Arrears → Notice History`.
Sole proprietors may also use the NTS automated telephone service at 1544-9944 to check their advance VAT amount.
When preparing an interim return, businesses should verify that electronic tax invoices for 7–September, credit card sales, cash receipts, platform settlement records, purchase documentation, and other supporting materials match their actual transactions.
Pre-filled information provided by Hometax may also differ from actual transaction records, so it is advisable to reconcile the information before filing.
When Must Businesses Pay the Advance VAT Amount Despite Declining Sales?
If the decline in sales does not meet the eligibility requirements for an interim return and there is no qualifying reason for an early refund, the business must follow the standard advance VAT payment procedure.
Businesses subject to advance VAT notices generally pay the assessed amount without filing a separate interim return.
The advance VAT paid in this way is deducted as tax already paid when the next final VAT return is filed.
The October 2026 advance VAT payment is reflected in the final VAT return for the 2 VAT period of 2026.
Therefore, paying the advance VAT amount does not mean that the business must pay the same amount again in full when filing its final return.
Some businesses are also excluded from advance VAT notices altogether.
According to NTS guidance, businesses are excluded from advance VAT notices if the amount to be collected is below KRW 500,000, or if they converted from simplified VAT taxpayer status to general VAT taxpayer status as of the beginning of the tax period, among other qualifying circumstances.
If you have not received a notice, it is advisable to check your business's VAT taxpayer classification and whether an exclusion applies.
What Businesses With Declining Sales Should Decide This October
If you have received a October 2026 advance VAT payment notice, you should review your actual business results for 7–September before deciding whether to pay the assessed amount.
If your sales or VAT payable are below 1/3 of the amount for the first half of the year, or if you qualify for an early refund, you may consider filing an interim return.
If you choose to file an interim return, the deadline is October 26. If you instead pay the standard advance VAT amount as assessed, the applicable deadline is November 2.
Because eligibility to file and the actual VAT payable depend on each business's tax records, it is advisable to review your Hometax filing information and, if necessary, consult the NTS Taxpayer Assistance Center at 126 or a tax professional.
※ This article is provided for reference purposes to help readers understand market trends and does not constitute investment advice regarding any particular security or asset. All final investment decisions and responsibilities rest with the individual.