
Mortgage Balance of KRW 300,000,000: Can a 0.5%p Rate Cut Recover KRW 900,000 in Fees?
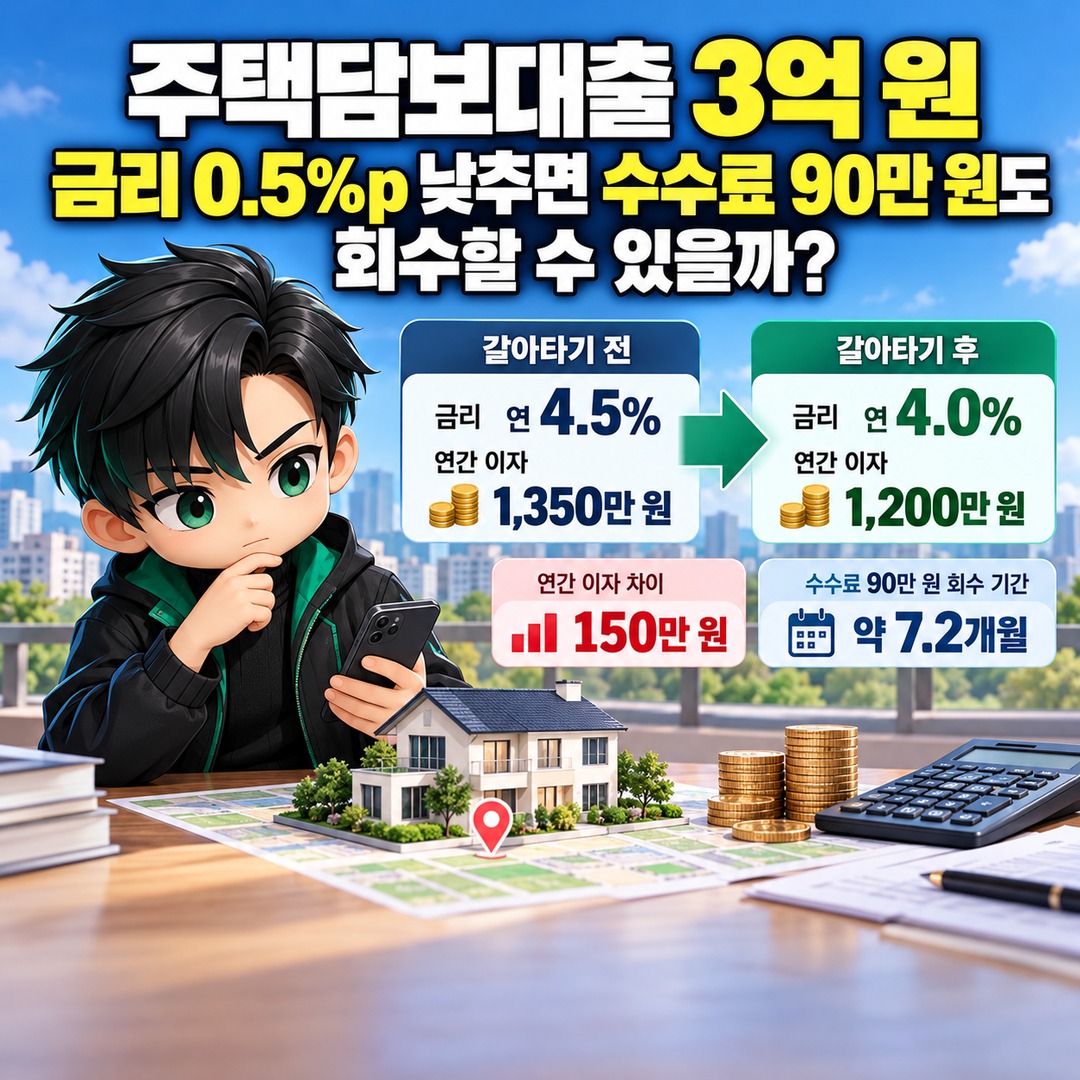
If a mortgage balance of KRW 300,000,000 is refinanced from an annual interest rate of 4.5% to 4.0%, the annual interest difference is KRW 1,500,000, assuming the principal remains unchanged. If the early repayment fee and additional expenses total KRW 900,000, a simple calculation suggests that the costs can be recovered in approximately 7.2 months. However, the actual benefit depends on the original loan agreement date, repayment method, remaining term, and conditions of the new loan.
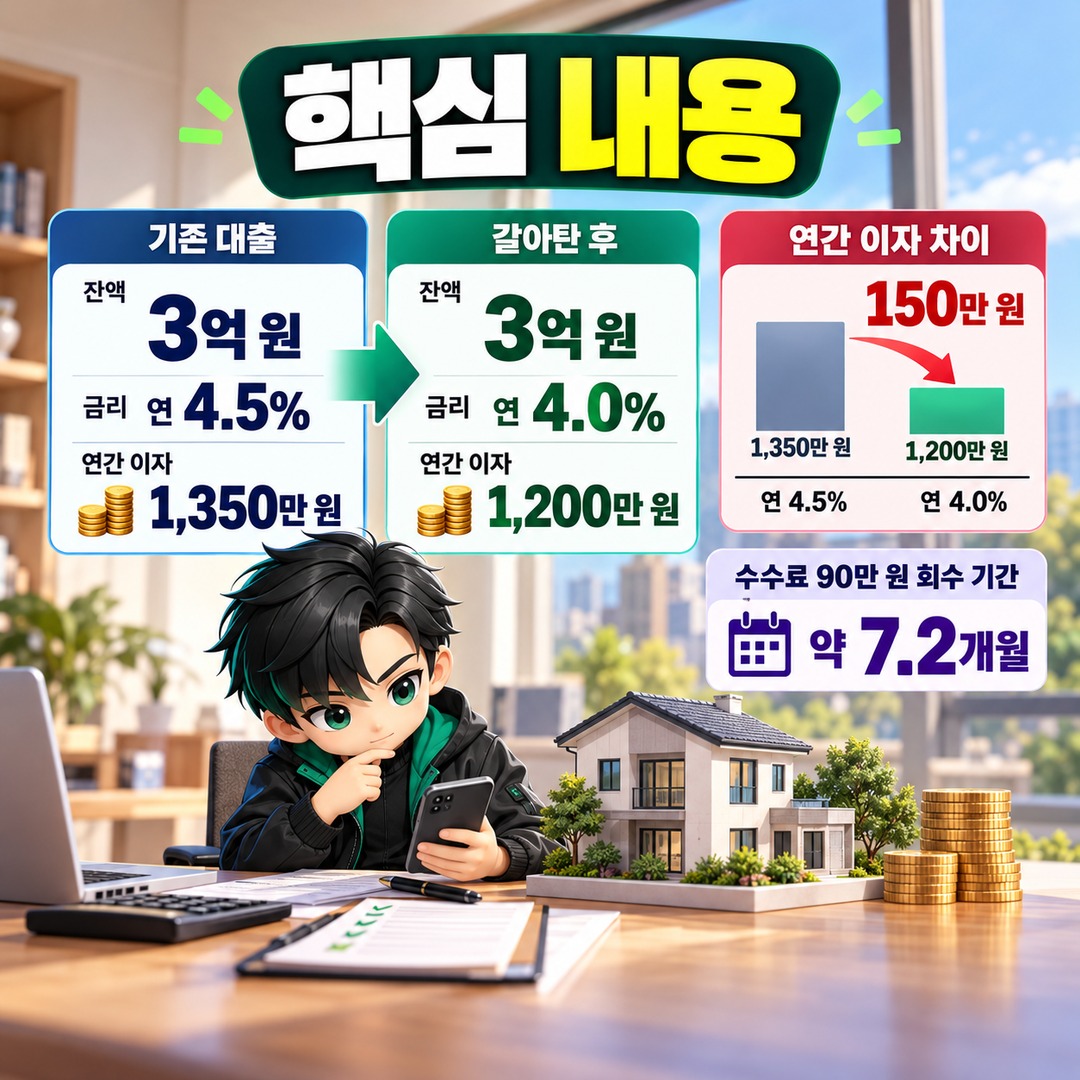
As of 2026-10-25, the key question is not simply how much lower the interest rate is, but how quickly the costs of refinancing can be recovered through future savings.
How Much Interest Can You Save by Lowering the Rate on KRW 300,000,000 by 0.5%p?
If the outstanding loan balance remains at KRW 300,000,000, an annual interest rate difference of 0.5% percentage points produces an interest difference of KRW 1,500,000 over 1 year.
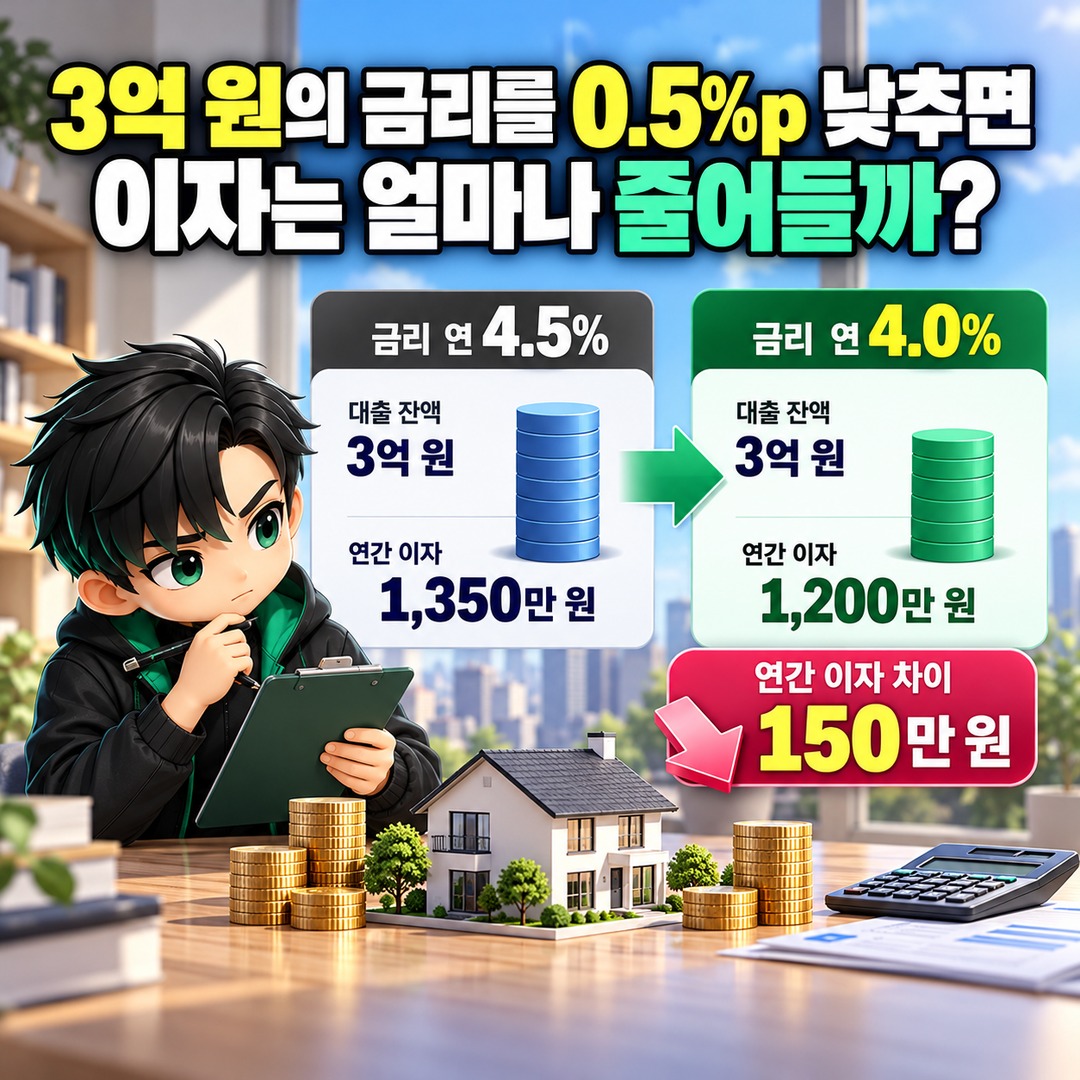
The calculation is as follows.
KRW 300,000,000 × 0.005 = KRW 1,500,000
Dividing this by 12 months gives a monthly average of KRW 125,000.
| Item | Existing Loan | Refinanced Loan |
|---|---|---|
| Outstanding loan balance | KRW 300,000,000 | KRW 300,000,000 |
| Annual interest rate | 4.5% | 4.0% |
| Annual interest | KRW 13,500,000 | KRW 12,000,000 |
| Average monthly interest | KRW 1,125,000 | KRW 1,000,000 |
The table above is a hypothetical example for illustration. It uses a simple interest calculation in which the loan principal remains at KRW 300,000,000 throughout 1 year. It does not represent the actual monthly payment or total annual interest on a loan with equal monthly principal-and-interest payments.
With equal monthly principal-and-interest payments, borrowers repay both principal and interest each month, so the outstanding balance gradually decreases. As a result, the actual amount of interest saved also changes over time.
In particular, a reduction in the monthly payment should not be treated entirely as interest savings. Part of the difference may come from a change in the amount of principal being repaid.
How Is an Early Repayment Fee of KRW 900,000 Calculated?
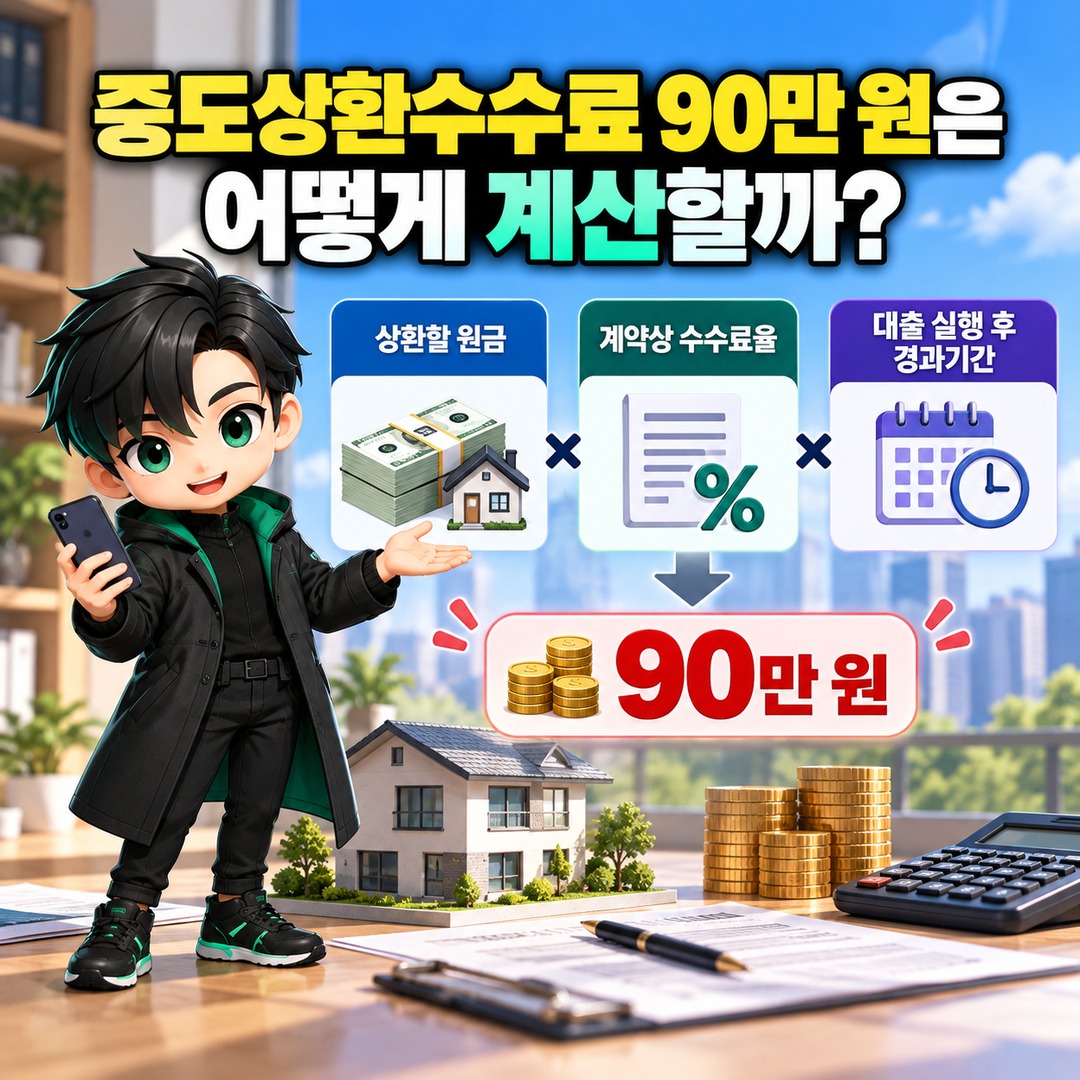
An early repayment fee may vary depending on the principal being repaid, the contractual fee rate, and the time elapsed since the loan was originated.
Consider the following hypothetical conditions.
Loan principal to be repaid: KRW 300,000,000
Contractual early repayment fee rate: 0.6%
Fee assessment period: 3 years
Time elapsed since loan origination: 18 months
Time remaining in the fee assessment period: 18 months
If the contract provides for the fee to decrease in proportion to the remaining period, the formula is:
Early repayment fee = Principal being repaid × Fee rate × Proportion of the fee assessment period remaining
KRW 300,000,000 × 0.006 × (18 months ÷ 36 months)
= KRW 900,000
This is the author's calculation based on an assumed fee rate of 0.6%, not an actual 2026 fee quotation from any particular bank.
Financial institutions may calculate the actual amount according to the contract terms and the precise number of days elapsed. Borrowers should therefore confirm the repayment amount quoted by their bank before proceeding with a new loan.
Does the 2025 Fee Reform Also Apply to Existing Loans?
The method for calculating early repayment fees changed starting 2025-01-13, but the new fee rates do not automatically apply to all loans contracted before that date.
In its January 2025 announcement on early repayment fee reform, South Korea's Financial Services Commission stated that the system had been revised so that fees would be calculated primarily based on the costs financial institutions incur when borrowers repay loans early.
The average mortgage fee rates for banks announced at the time were as follows.
| Category | Before Reform | After Reform |
|---|---|---|
| Fixed-rate mortgages | 1.43% | 0.56% |
| Variable-rate mortgages | 1.25% | 0.55% |
These figures are banking-sector averages from the 2025 reform, not fee rates applicable to every loan in 2026.
According to the Financial Services Commission's Q&A on the application of new loan fee rates, the revised calculation method applies to contracts entered into from 2025-01-13 onward. Even if an existing contract has been renewed, it may be excluded if its key terms remain substantially unchanged.
Therefore, someone refinancing in 2026 a mortgage originally taken out in 2024 should first check the fee rate specified in their existing contract rather than relying on the newly announced rates.
How Many Months Does It Take for Refinancing to Become Worthwhile After Paying the Fee?
If the interest rate difference is 0.5%p and the outstanding loan balance is held constant at KRW 300,000,000, the average monthly interest savings are KRW 125,000.
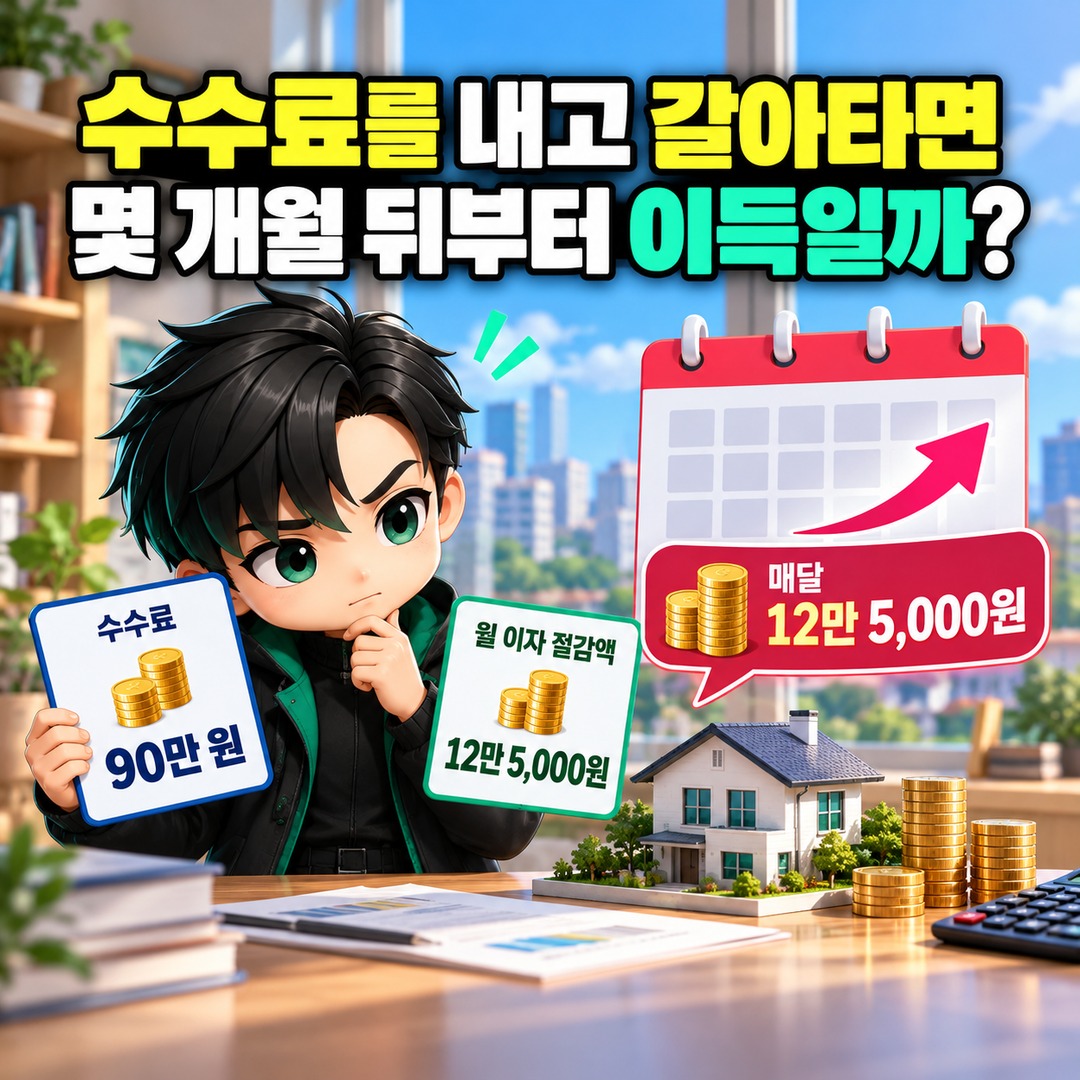
This amount can be used to calculate the break-even period for different refinancing costs.
| Total Refinancing Cost | Simple Payback Period |
|---|---|
| KRW 300,000 | 2.4 months |
| KRW 600,000 | 4.8 months |
| KRW 900,000 | 7.2 months |
| KRW 1,200,000 | 9.6 months |
| KRW 1,800,000 | 14.4 months |
Author's calculation. This assumes that the outstanding loan balance remains at KRW 300,000,000, the interest rate difference stays at 0.5%p, and no additional costs arise. The actual payback period for an amortizing loan may differ.
If the early repayment fee is KRW 900,000 and there are no other costs, the simple payback period is approximately 7.2 months.
However, if additional expenses of KRW 300,000 are incurred on top of the KRW 900,000 fee, the total cost becomes KRW 1,200,000, extending the payback period to approximately 9.6 months.
There is an important distinction here.
The time needed to recover the early repayment fee is not necessarily the same as the time needed to recover all refinancing costs.
If stamp taxes, registration-related expenses, or other borrower-paid charges apply, they must be included in the total. Borrowers should confirm whether these charges apply and how much they will cost with the financial institution providing the new loan.
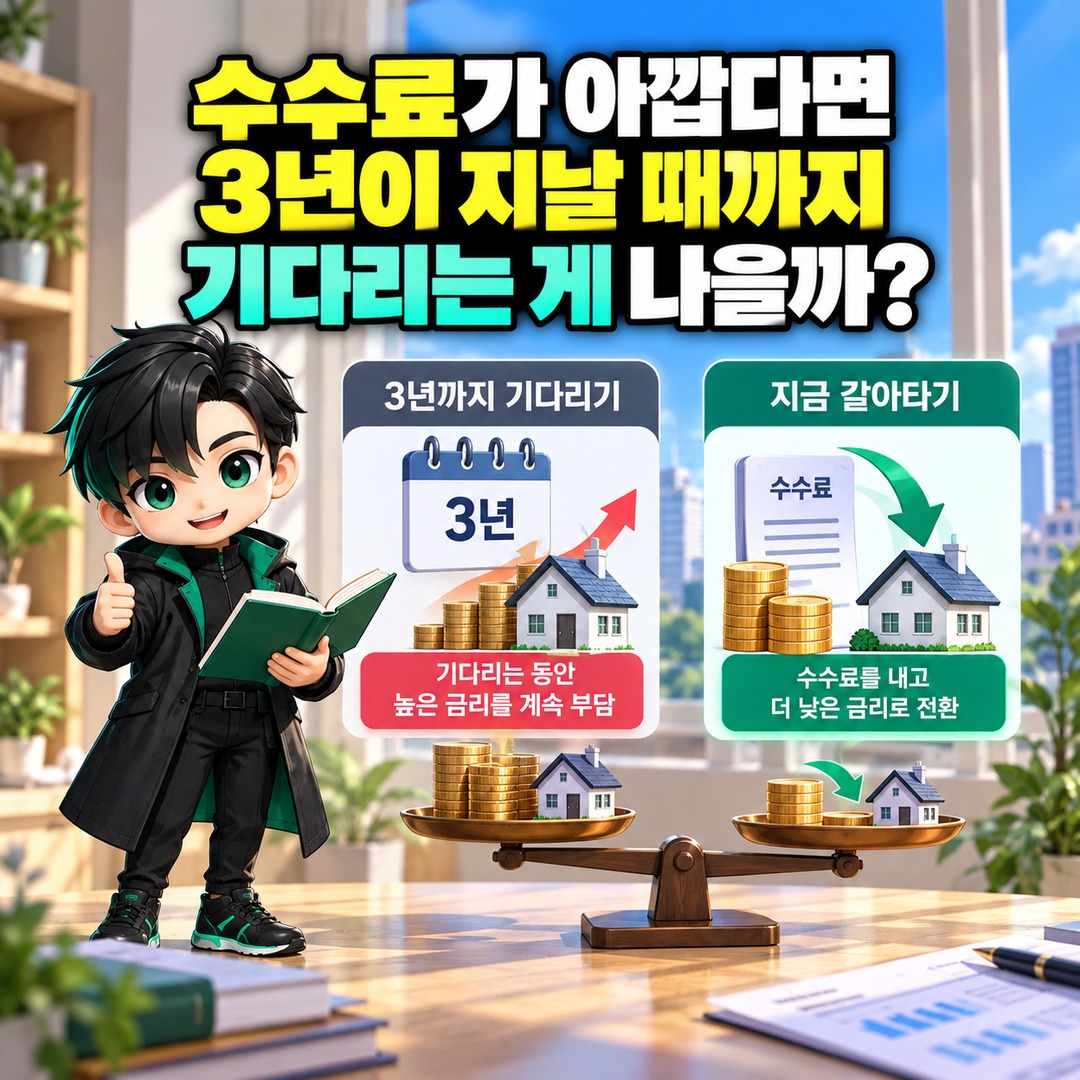
Is It Better to Wait Until 3 Years Have Passed to Avoid the Fee?
Waiting until the early repayment fee is waived is not always the better option. During the waiting period, the borrower may continue paying the higher interest rate on the existing loan.
Consider another hypothetical example.
Assume the outstanding loan balance is KRW 300,000,000, the existing annual interest rate is 4.5%, and the refinancing rate is 4.0%.
Also assume that 6 months remain until the early repayment fee is waived and that refinancing now would incur a fee of KRW 300,000.
If the principal remains unchanged, the interest difference over 6 months is calculated as follows.
KRW 300,000,000 × 0.005 × (6 ÷ 12)
= KRW 750,000
If refinancing now costs only the KRW 300,000 fee, the difference between the simple interest savings over 6 months and that fee is KRW 450,000.
Conversely, if the fee and additional expenses total KRW 1,000,000, the costs exceed the simple interest savings of KRW 750,000 over 6 months. In that case, waiting could be the better choice.
Both calculations assume that interest rates remain unchanged throughout 6 months, the loan principal does not decrease, and the loan execution timing and other conditions are otherwise identical.
In practice, borrowers should compare the exact time remaining until the fee waiver date with the interest savings expected during that period.
Why Refinancing Can Be a Poor Choice Even When Monthly Payments Fall
Extending the repayment term can reduce monthly payments while increasing the total interest paid over the life of the loan.
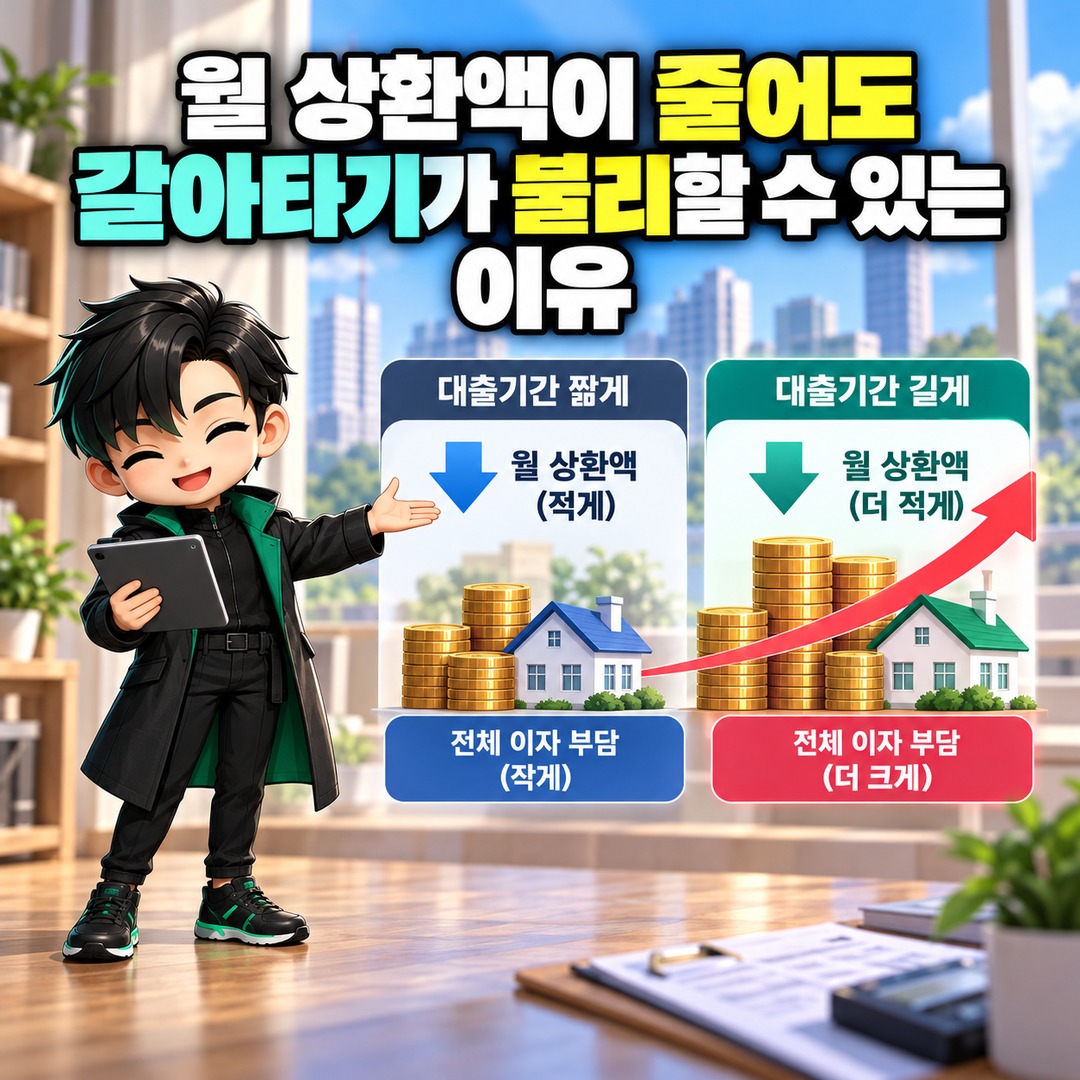
For example, suppose the existing loan has 15 years remaining, but the new loan is set to run for 30 years. In that case, the lower monthly payment reflects not only the reduced interest rate but also the effect of spreading principal repayment over a longer period.
If the goal is to reduce monthly financial pressure, a longer repayment term may help.
However, if the goal is to reduce total interest expenses, the comparison needs to be made differently.
The remaining total interest payable on the existing loan should be compared with the total interest payable after refinancing, using the same repayment end date as the basis for comparison.
Furthermore, if the borrower switches from a variable rate to a fixed rate, or if the fixed-rate period changes, comparing only the interest rates currently being offered is insufficient.
Borrowers should also examine the interest rate application period, future rate-reset conditions, and requirements for maintaining preferential interest rates.
What Should You Confirm With Your Bank Before Refinancing?
Mortgage refinancing does not happen automatically simply because a lower interest rate is available. The borrower must undergo a new loan assessment, collateral valuation, and confirmation of the amount that can be borrowed.
At the existing bank, borrowers should confirm the early repayment fee and total payoff amount based on the intended repayment date. At the new bank, they should verify the interest rate actually available to them and the repayment term.
The following items should be checked.
1. Current outstanding principal and interest rate on the existing loan
2. Original loan execution date and early repayment fee waiver date
3. Actual early repayment fee applicable on the refinancing date
4. Confirmed or estimated interest rate on the new loan and conditions for preferential rates
5. Additional expenses payable by the borrower, including stamp taxes
6. Repayment terms and repayment methods of both the existing and new loans
7. Whether the new loan can be approved and its expected execution date
Checking only the fee and the new interest rate while overlooking the repayment term can lead to a misleading comparison of monthly payments and, ultimately, a poor decision.
In particular, if the existing loan is a government-backed policy loan or includes special contractual provisions, borrowers should separately verify whether it can be refinanced in the same way as a conventional bank mortgage.
How Should You Decide Whether to Refinance KRW 300,000,000 When the Rate Difference Is 0.5%p?
For an outstanding mortgage balance of KRW 300,000,000, an interest rate reduction of 0.5%p produces an annual interest difference of KRW 1,500,000, provided the principal remains unchanged.
If total refinancing costs are KRW 900,000, the simple payback period is approximately 7.2 months. However, for an actual loan with equal monthly principal-and-interest payments, the declining principal balance and differences in repayment terms must be considered. This period should therefore not be treated as a guaranteed break-even point.
It helps to distinguish three amounts when making the decision.
First, the interest you would pay in the future if you kept your existing loan.
Second, the interest you would pay after refinancing into the new loan.
Third, the one-time costs incurred during refinancing, including the early repayment fee.
The point at which the interest savings between the two loans exceed the refinancing costs is the break-even point that matters for your circumstances.
If you plan to sell your home or repay the entire loan in the near future, the comparison period should end at that point.
Conversely, if you intend to keep the loan for a long time and the new interest rate comes with favorable conditions, refinancing may be a reasonable choice even if you have to pay an early repayment fee.
The first step is to ask your existing bank for the early repayment fee and total payoff amount applicable on your intended refinancing date. You need those figures before you can compare the costs with your actual potential interest savings.
※ This article is provided for reference to help readers understand market conditions and does not constitute an investment recommendation for any specific security or asset. Final decisions and responsibility for investments rest with the individual.