

October 2026 VAT Advance Notice: Businesses With Declining Sales May Cancel the Assessed Amount by Filing an Interim Return
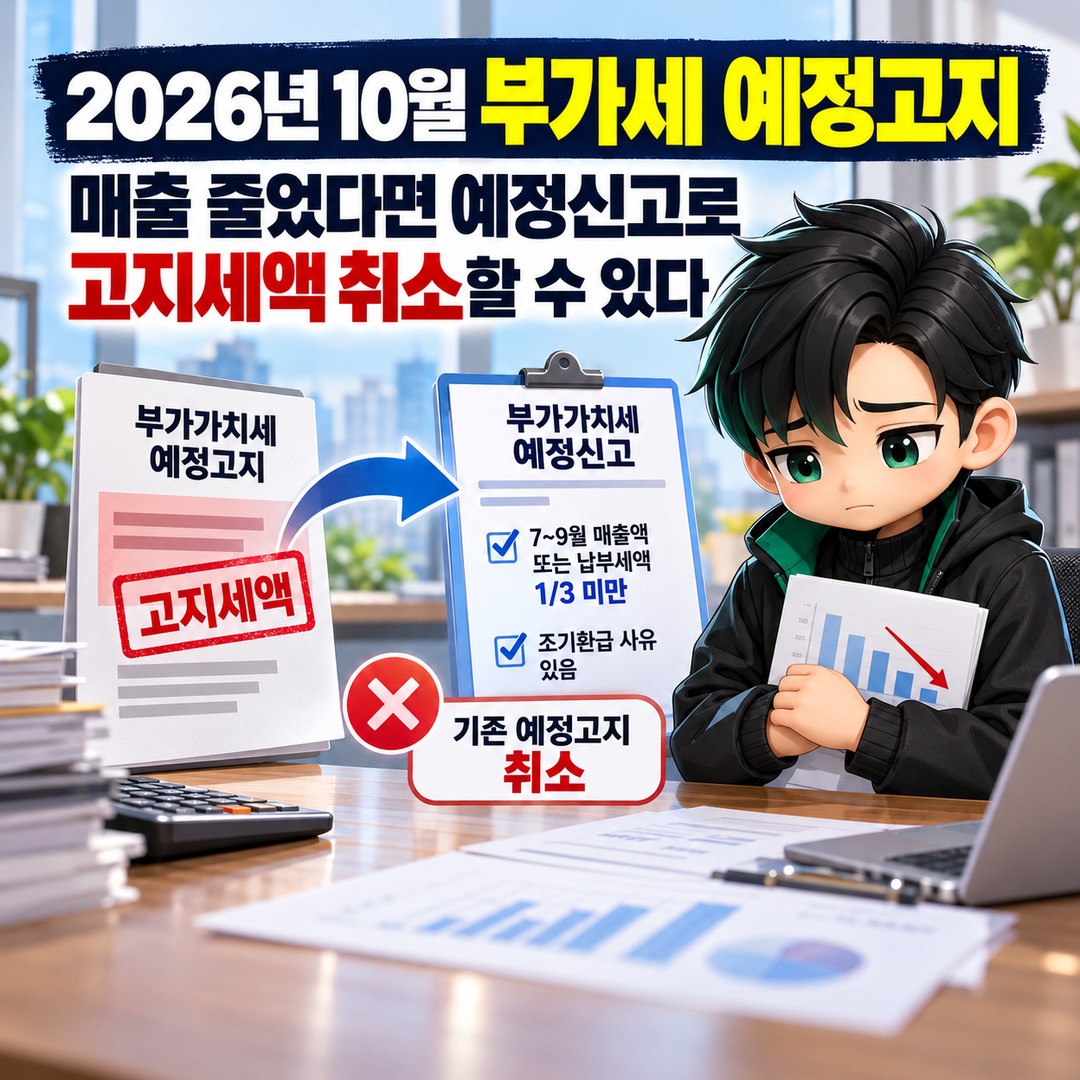
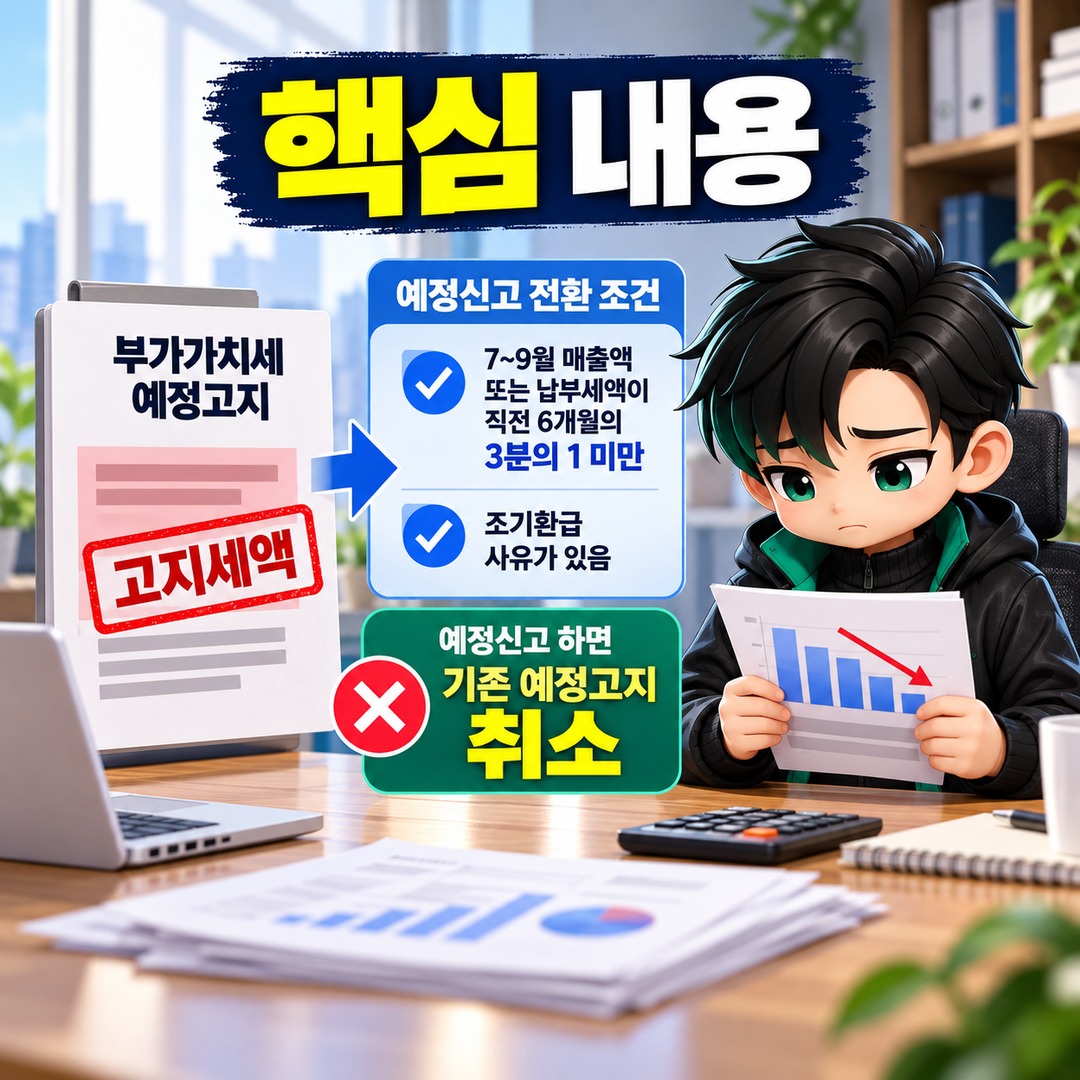
If a October 2026 VAT advance notice is based on results from before a decline in sales, businesses meeting certain conditions may switch to filing an interim return. An interim return is permitted if sales or VAT payable for 7–September are less than 1-3 of the corresponding amount for the preceding 6-month tax period, or if grounds for an early refund exist. Filing the return cancels the original advance notice.
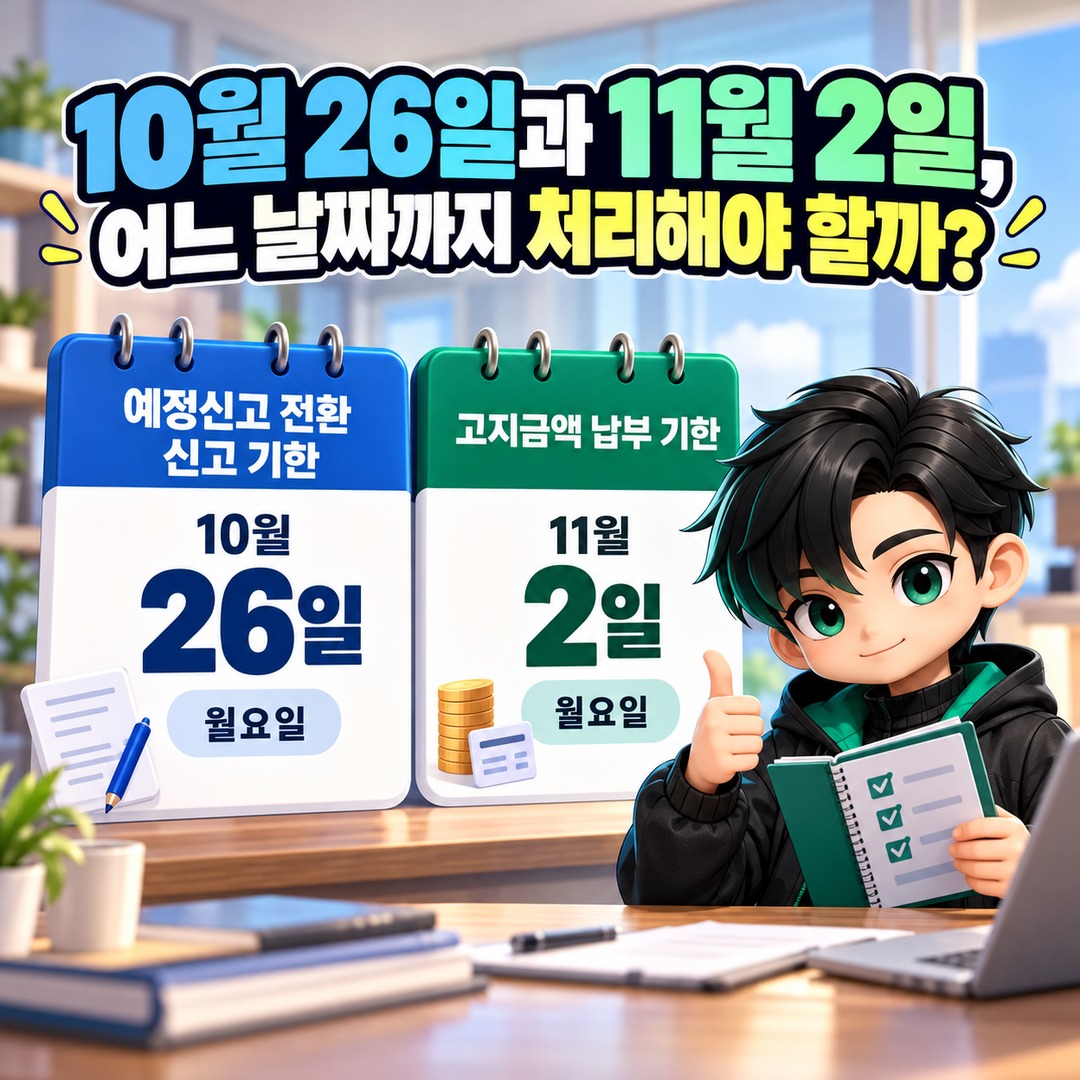
However, a modest decline in sales does not automatically entitle every business to a reduction in its assessed tax. The 2026 interim return filing deadline is October 26, while the advance-notice payment deadline is November 2. These are different dates.
As of 2026-10-25, this information is based on the National Tax Service's guidance on VAT interim returns and advance notices, announced on October 5.
Why Has My VAT Advance Notice Stayed the Same Even Though Sales Have Fallen?
A VAT advance notice is not calculated anew using actual sales from the current 3-month period. As a general rule, the assessed amount is based on 50% of the VAT paid for the preceding tax period.
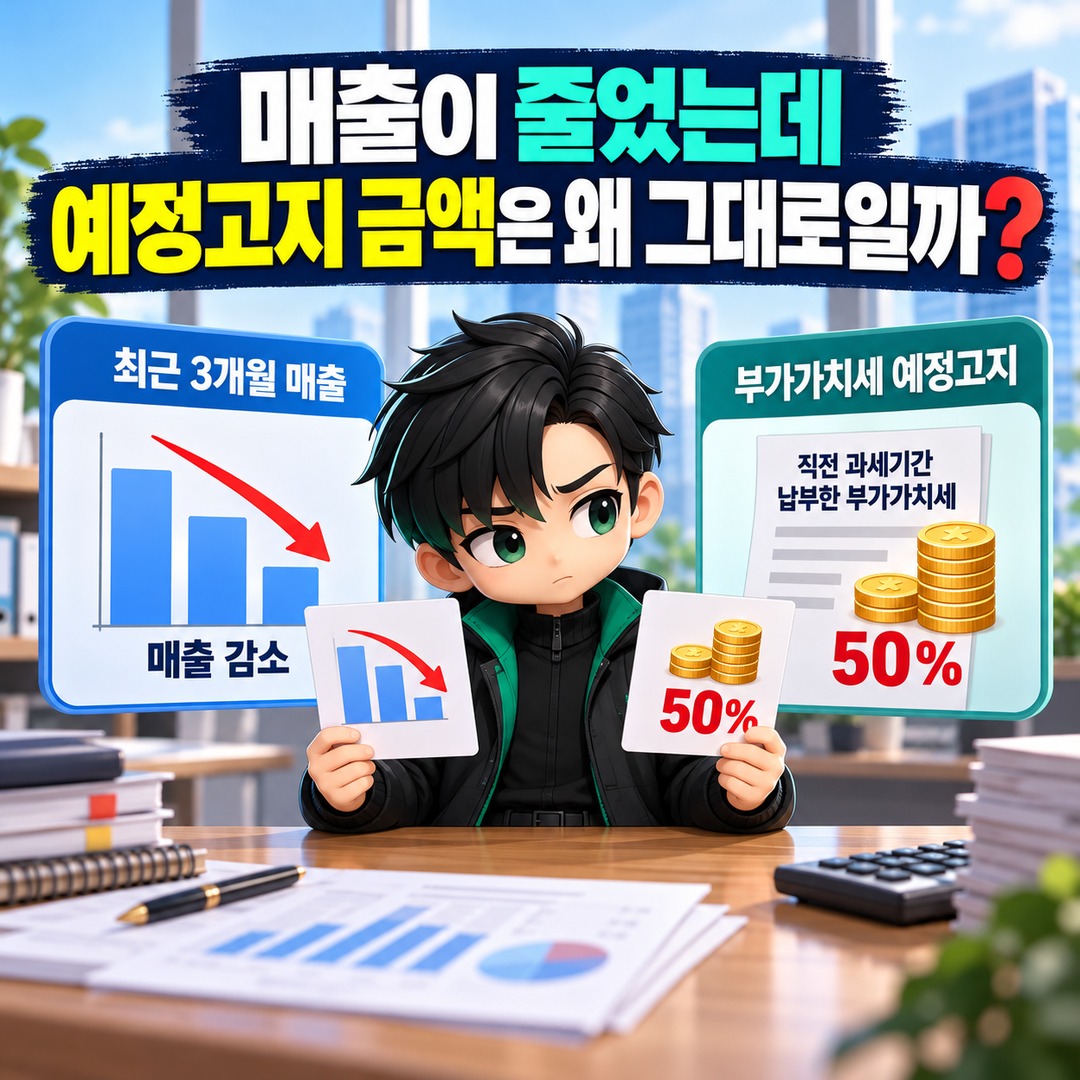
The October 2026 advance notice is based on the VAT paid between 2026-01-01 and June 30.
For example, a business that performed well in the first half of the year but experienced a sharp decline in sales starting in July could receive a October notice showing an amount higher than its current operating conditions might suggest.
The National Tax Service (NTS) stated that approximately 223 ten thousand individual general VAT taxpayers and approximately 19 ten thousand small corporations are subject to the October 2026 advance-notice system.
A small corporation is defined as a corporation whose total taxable supply value in the preceding tax period was less than 1 hundred million 5 ten thousand won.
How Much Must Sales Decline to Qualify for an Interim Return?
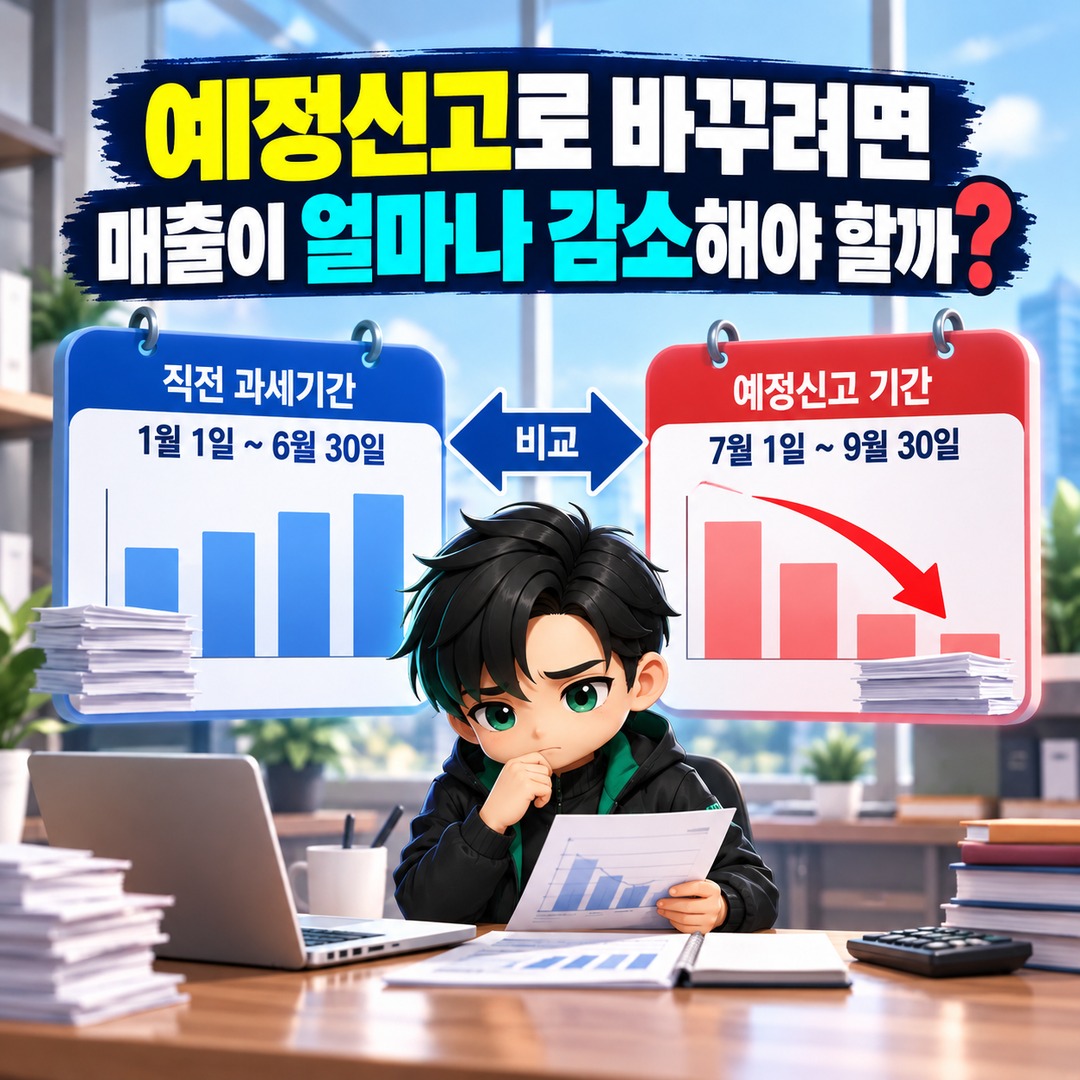
For the 2 VAT interim return in 2026, sales or VAT payable from July 1 through September 30 are compared with the corresponding amounts for the preceding tax period, from January 1 through June 30.
If Either Amount Falls Below 1-3 of the Previous Tax Period's Amount, You May Choose to File an Interim Return.
Both sales and VAT payable do not have to decline. An interim return is also permitted when grounds for an early VAT refund arise.
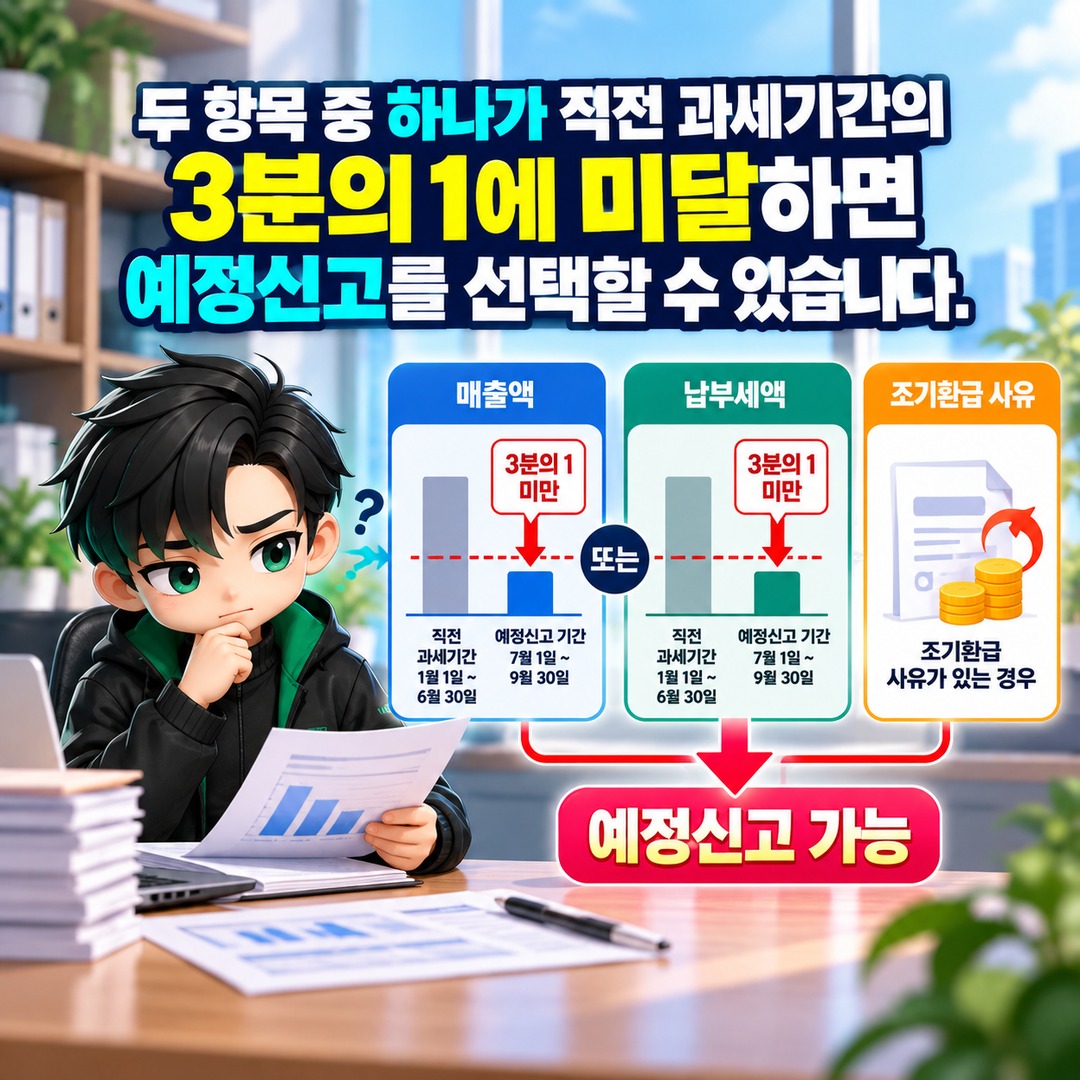
This is related to the interim filing provisions for business difficulties and other qualifying circumstances under Article 48, Paragraph 4 of the Value-Added Tax Act.
Calculating the Sales Decline Threshold
Consider a hypothetical individual general VAT taxpayer whose sales in the first half of 2026 were KRW 90,000,000.
1-3 of the preceding tax period's sales is calculated as follows:
KRW 90,000,000 ÷ 3 = KRW 30,000,000
Therefore, if sales during 7–September of 2026 were KRW 27,000,000, they would be KRW 3,000,000 below the threshold, satisfying the sales requirement.
Conversely, if sales during 7–September were KRW 30,000,000, they would equal exactly 1-3 of the previous period's sales. The business would therefore not satisfy the requirement of being 'less than 1-3' based on sales alone. It would need to check the VAT payable requirement or whether grounds for an early refund apply.
It is also important to remember that the periods being compared are 6 months and 3 months. This is not simply a comparison of whether sales declined from the previous quarter.
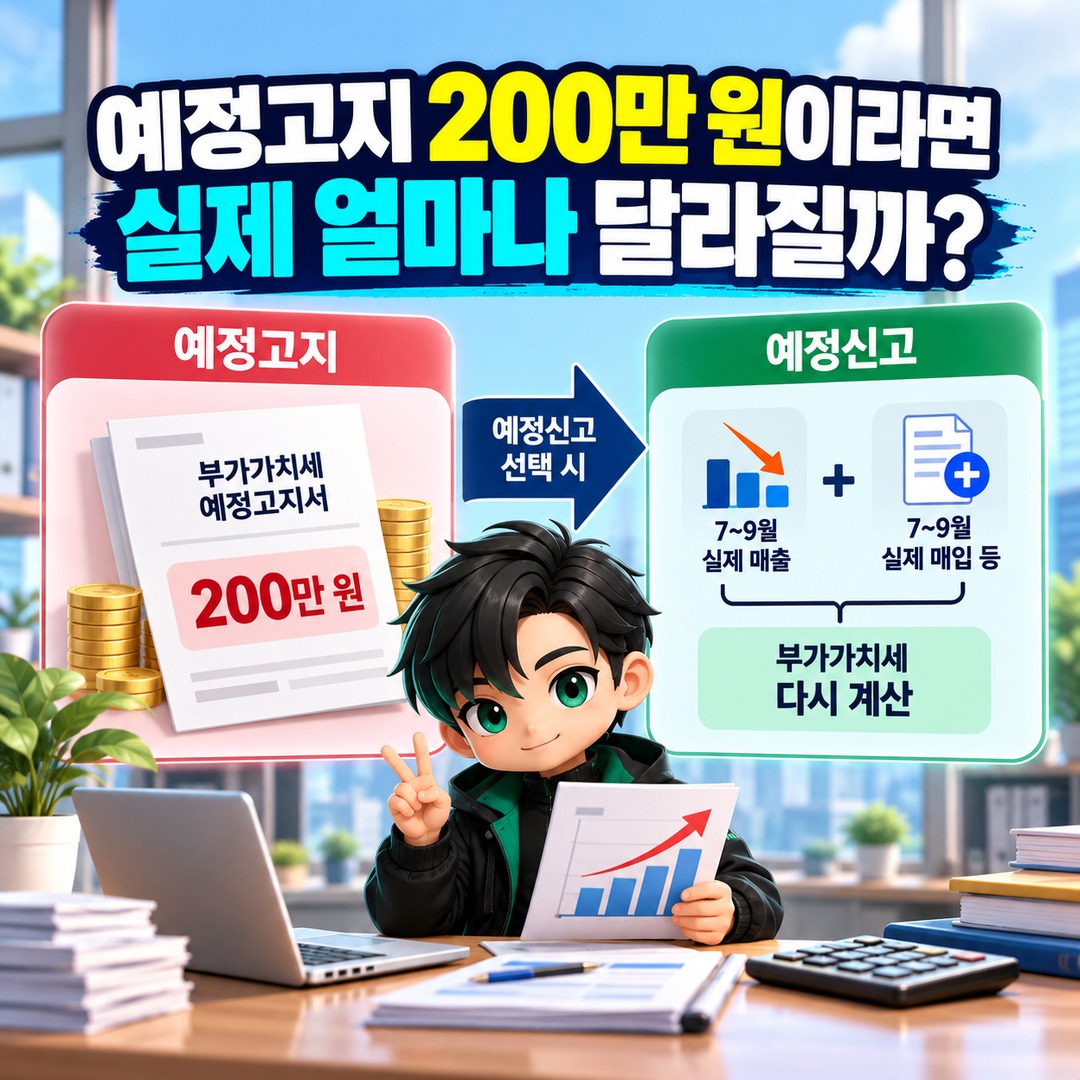
If Your VAT Advance Notice Is KRW 2,000,000, How Much Could the Amount Change?
Choosing to file an interim return does not mean receiving a fixed percentage discount on the advance-notice amount. Instead, the business calculates VAT using actual sales, purchases, and other relevant figures for 7–September, rather than paying the amount stated in the advance notice.
Consider the following hypothetical example.
| Item | Amount |
|---|---|
| VAT paid for the first half of 2026 | KRW 4,000,000 |
| VAT assessed in the October advance notice | KRW 2,000,000 |
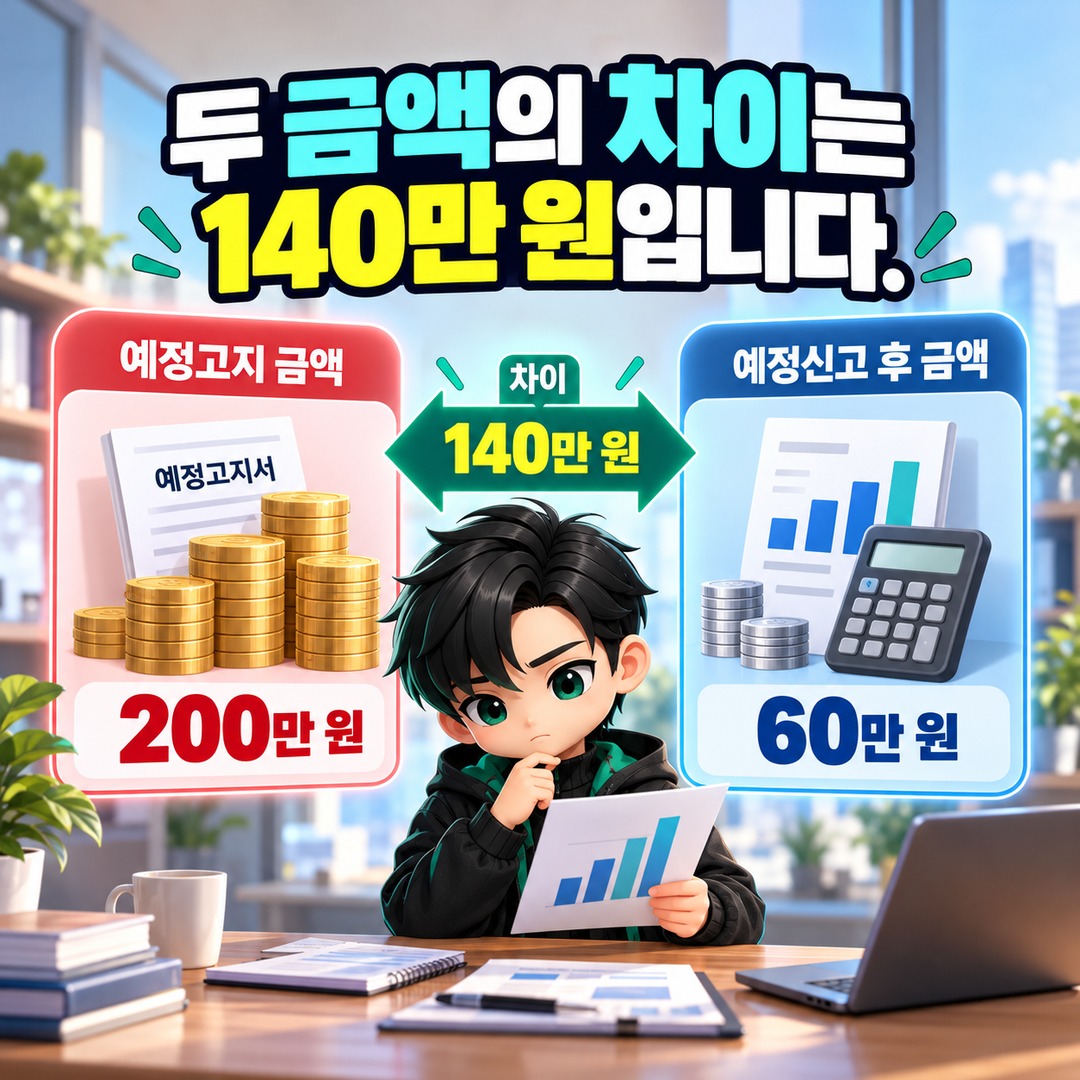
| Actual VAT payable for 7–September (assumed) | KRW 600,000 |
| Difference between the two amounts | KRW 1,400,000 |
If the VAT paid for the first half of the year was KRW 4,000,000, the advance-notice amount would generally be KRW 2,000,000.
However, suppose the actual VAT payable for 7–September is calculated as KRW 600,000. This would be less than approximately KRW 1,333,333, or 1-3 of the VAT paid for the preceding tax period.
If the business properly completes an interim return, the original advance notice for KRW 2,000,000 is canceled. The business instead files and pays based on the assumed actual VAT liability of KRW 600,000.
The Difference Between the Two Amounts Is KRW 1,400,000.
This is a hypothetical illustration based on the author's calculations, not an actual tax saving or refund. The actual VAT payable depends on each business's taxable sales, deductible input VAT, applicable credits, additional taxes, and other information reported in its return.
Importantly, VAT paid under an advance notice is deducted as tax already paid when the subsequent final return is filed. A reduction in the amount payable immediately through an interim return must therefore be distinguished from an equivalent reduction in the business's final tax liability.
October 26 or November 2: Which Deadline Applies?
Businesses wishing to switch to filing a October 2026 VAT interim return must submit their return by Monday, October 26. Businesses that received an advance notice and do not file an interim return must pay the assessed amount by Monday, November 2.
| Item | 2026 Deadline |
|---|---|
| Interim return filing and payment | October 26 (Monday) |
| Payment of VAT assessed through an advance notice | November 2 (Monday) |
| Electronic filing through Hometax | By 24 on October 26 |
| In-person filing at a tax office | By 18 on October 26 |
The NTS extended the advance-notice payment deadline because public holidays in early October could delay delivery of tax notices.
However, this extension applies to payment of advance notices. It does not mean that the interim return filing deadline was also extended to November 2.
Businesses choosing to file an interim return because of declining sales should therefore be careful not to confuse the two dates.
How to Check Your Advance Notice and File an Interim Return Through Hometax
You can check whether your business is subject to an advance notice and view the assessed amount through the NTS Hometax service. Before choosing an interim return, it is advisable to review both the existing assessment and the actual filing records for 7–September.
First, sign in to NTS Hometax.
1. Under `Tax Filing → Value-Added Tax Filing → View Filing Assistance Materials`, check whether your business is subject to an advance notice and review the assessed tax.
2. Compare sales and VAT payable for the first half of 2026 with the corresponding figures for 7–September.
3. If you meet the interim filing requirements, use the VAT filing menu to submit the 2 interim return for 2026.
4. Reconcile sales and purchase records, including electronic tax invoices, credit card transactions, and cash receipts, before submitting the return.
5. Check the filing confirmation and tax payable, then make payment by the applicable deadline.
The NTS provides prefilled information for this filing period but advises businesses to verify that the information matches their actual transactions.
In particular, businesses should check that sales through delivery platforms, credit cards, and cash receipts have not been omitted or counted twice.
If you are unsure whether your business qualifies for an interim return, you can contact the National Tax Consultation Center at 126 or your local tax office.
What If Sales Have Declined but Have Not Fallen Below the 1-3 Threshold?
Even if the decline in sales is insufficient to meet the interim filing threshold, the VAT payable requirement can be assessed separately.
For example, sales might remain at or above 1-3 of the preceding tax period's sales, while actual VAT payable falls below 1-3 because of input VAT and other factors. In that situation, the business may assess whether it qualifies under the VAT payable requirement.
If neither requirement is met and there are no grounds for an early refund, financial difficulties alone would generally not be sufficient grounds for choosing an interim return.
However, businesses having difficulty making payments should check whether they qualify for separate tax relief measures.
In its October 2026 guidance, the NTS announced an automatic extension of payment deadlines until December 28 for certain eligible businesses in the flood-affected areas of Andong, Uiseong, Geoje, Tongyeong, and Yeonggwang, as well as certain businesses affected by matters related to Homeplus.
This payment deadline extension is a separate measure from cancellation of an advance notice. Businesses should confirm eligibility through their individual notices and the relevant tax support inquiry pages on Hometax.
What Happens to the Subsequent Final VAT Return If You File an Interim Return?
Choosing to file an interim return does not complete all VAT reporting for the second half of 2026.
The 2 VAT tax period for 2026 runs from July 1 through December 31. The current interim return covers the results from July through September within that period.
The subsequent final return reconciles the tax position by taking into account the amounts already reported and paid through the interim return.
Conversely, businesses that pay VAT under an advance notice deduct that payment as tax already paid when filing their final return.
When deciding whether to file an interim return, businesses should therefore consider not only the amount payable now but also how it will be reflected in the subsequent final return.
As of 2026-10-25, if declining sales have made your VAT advance notice difficult to pay, start by comparing sales or VAT payable for the first half of the year with the corresponding figures for 7–September. If you meet the interim filing requirements, the key is to complete a return reflecting actual business results by October 26.
※ This article is provided for reference to help readers understand market developments and does not constitute a recommendation to invest in any particular security or asset. All final investment decisions and associated responsibilities rest with the individual investor.