

If You Make a KRW 30,000,000 Partial Mortgage Principal Repayment, How Much Will Your Monthly Payment Decrease? Shortening the Loan Term vs. Lowering Payments
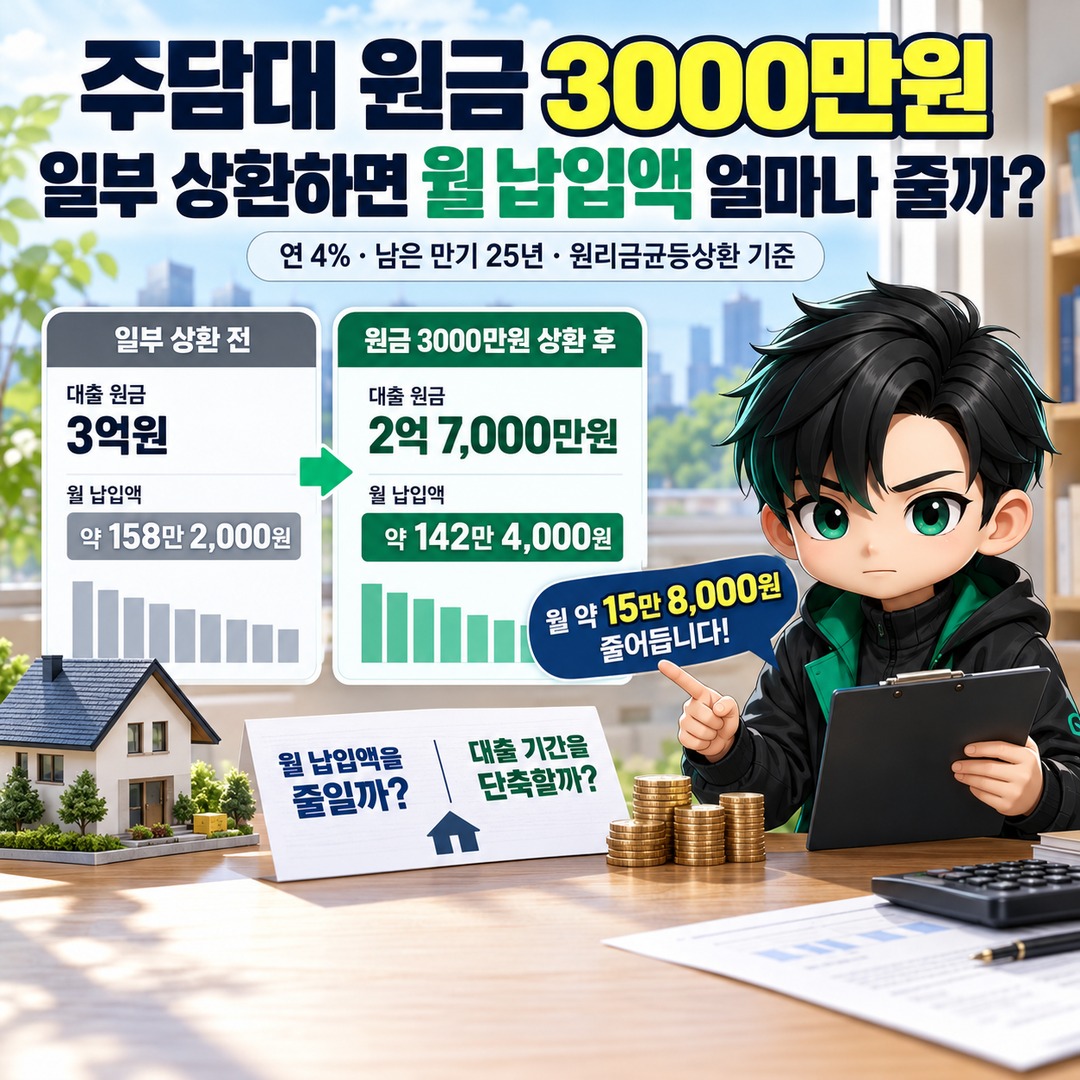
If you repay KRW 30,000,000 early on a mortgage with an outstanding principal of KRW 300,000,000, you may be able to reduce your monthly payment or pay off the loan sooner while keeping your monthly payments unchanged. For a mortgage with equal monthly principal-and-interest payments, an annual interest rate of 4%, and 25 years remaining, recalculating the monthly payment would reduce it by approximately KRW 158,000. However, the actual treatment depends on the loan product and the financial institution's agreement.
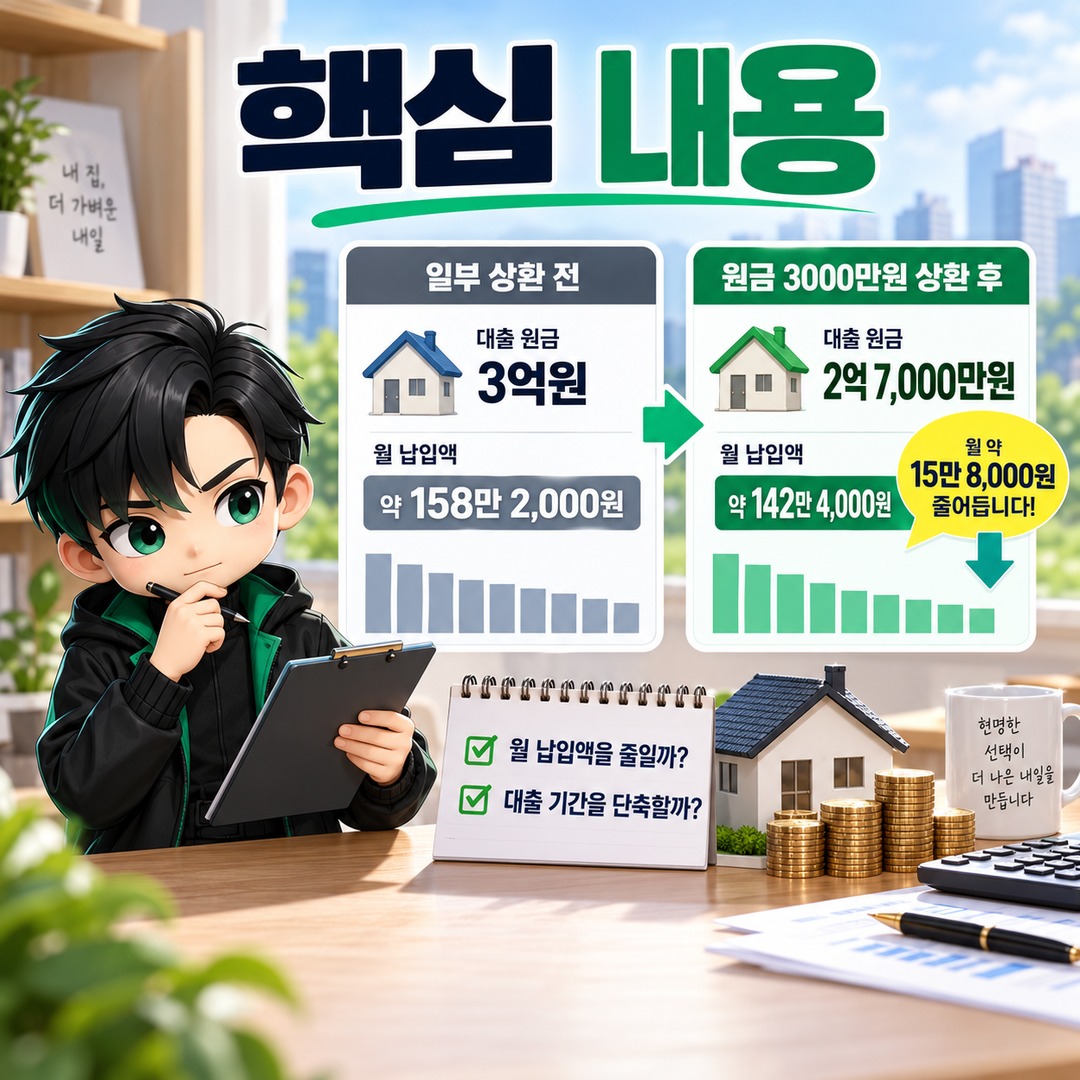
Even if you repay the same KRW 30,000,000, reducing your monthly financial burden and reducing total interest costs are two different objectives.
As of 2026-10-14, let's examine the calculations and decision criteria you should consider before making a partial mortgage repayment.
1. How Much Will Your Monthly Mortgage Payment Decrease If You Repay KRW 30,000,000?
If your lender allows your monthly payment to be recalculated, the outstanding loan balance decreases by the amount of principal repaid, and your new monthly payment is calculated using the remaining balance.
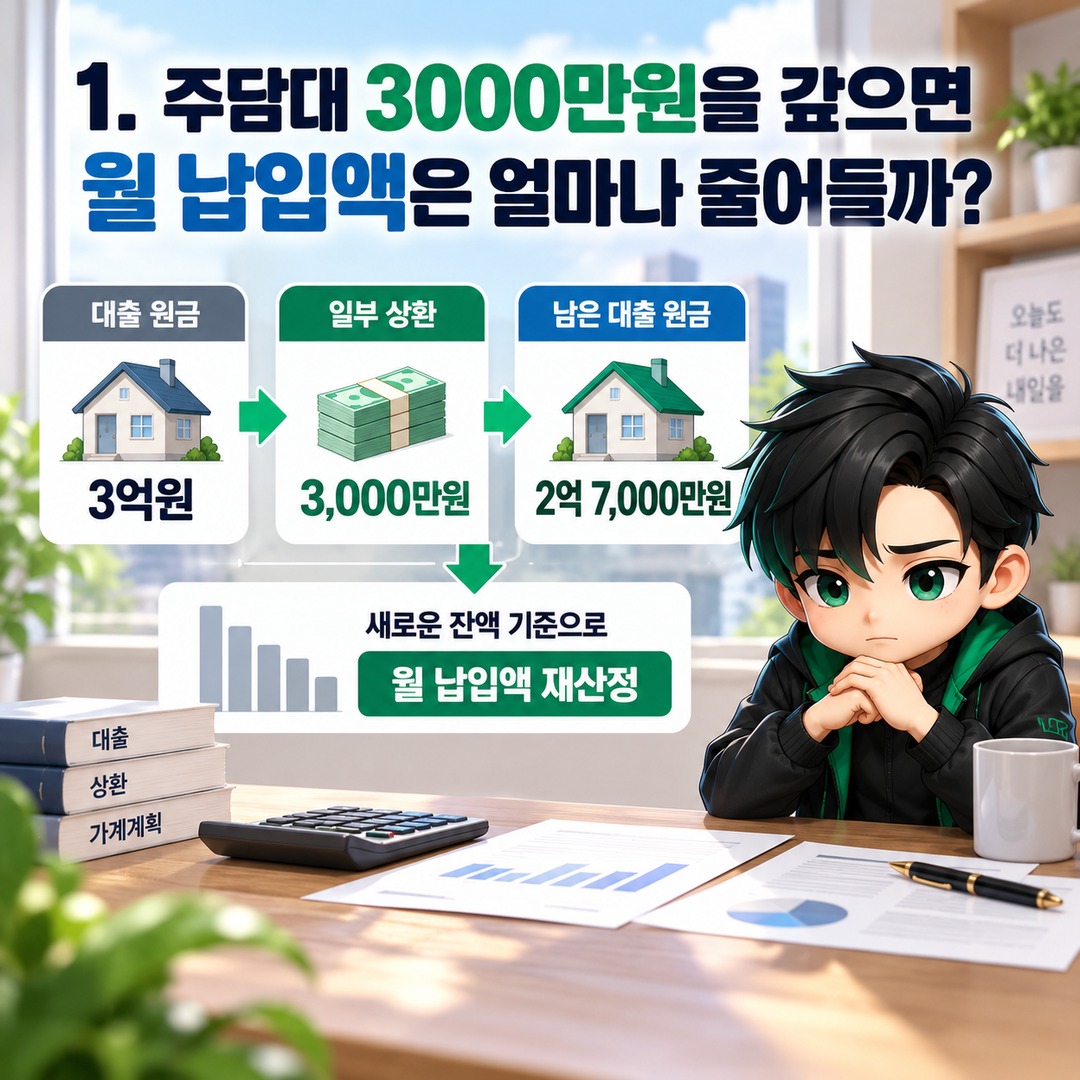
For example, assume the following conditions.
Current outstanding loan balance: KRW 300,000,000
Applicable interest rate: 4.0% annually
Remaining loan term: 25 years (300 months)
Repayment method: Equal monthly principal-and-interest payments
Partial early repayment amount: KRW 30,000,000
Interest rate and remaining maturity remain unchanged after the partial repayment
<text color="secondary" weight="medium" size="xs">Monthly Payment Comparison · Author's Calculations</text>
<text color="secondary" size="xs">Before repayment</text>
<title size="xl" color="default" tabularNums>Approximately KRW 1,584,000.0</title>
<caption>Outstanding loan balance: KRW 300,000,000</caption>
<text color="secondary" size="xs">After repaying KRW 30,000,000</text>
<title size="xl" color="default" tabularNums>Approximately KRW 1,425,000.0</title>
<caption>Outstanding loan balance: KRW 270,000,000</caption>
<text color="secondary" weight="medium" size="xs">Monthly reduction in principal and interest payments</text>
<title size="2xl" color="success">Approximately KRW 158,000</title>
<caption>Annual reduction of approximately KRW 1,900,000 · Excluding fees</caption>
The reason your monthly payment can decrease by approximately 10% is that, under an equal principal-and-interest repayment schedule, the monthly payment is proportional to the outstanding loan balance when the interest rate and remaining term stay the same.
If you repay KRW 30,000,000 on a balance of KRW 300,000,000, the outstanding balance decreases by 10%. Accordingly, the monthly payment also decreases by approximately 10%.
However, this calculation applies when the bank keeps the remaining loan term unchanged and recalculates the monthly payment. A partial repayment does not automatically reduce monthly payments on every mortgage.
2. What Is the Difference Between Reducing Monthly Payments and Shortening the Loan Term?
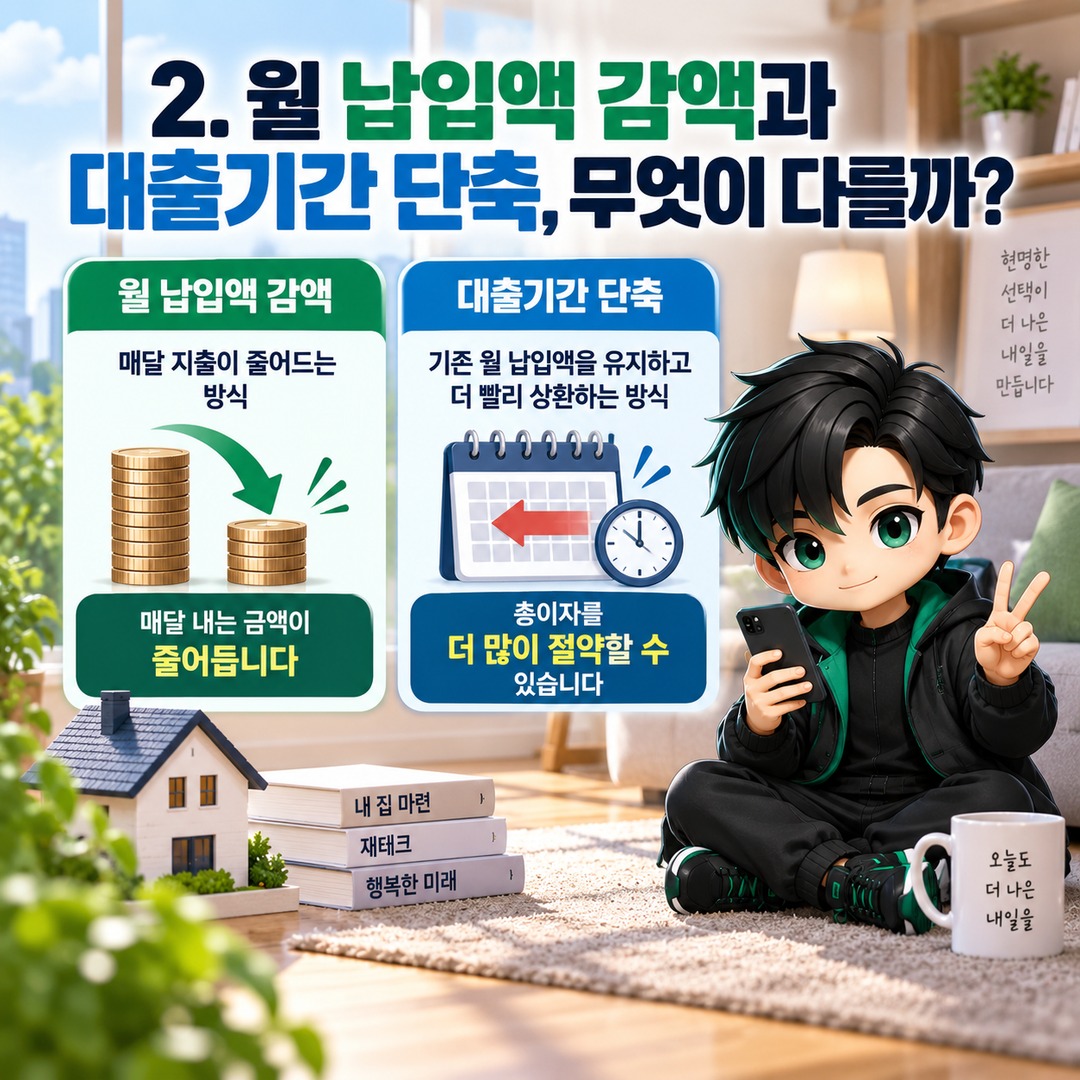
Reducing your monthly payment after a partial early repayment helps lower your regular expenses. By contrast, if you can maintain your existing monthly payment while shortening the loan term, you can save more in total interest.
Even when you repay the same KRW 30,000,000, the outcome depends on the subsequent repayment schedule.
| Comparison | Reduce Monthly Payments | Shorten Loan Term |
|---|---|---|
| Monthly payment | Decreases | Remains at the existing level |
| Remaining loan term | Stays at 25 years | Approximately 20 years and 9 months |
| Monthly cash flow | More disposable income | Little change |
| Total interest savings | Relatively smaller | Relatively greater |
The table above is based on the hypothetical example presented earlier, with an annual interest rate of 4%, an outstanding balance of KRW 300,000,000, and 25 years remaining.
Under the shorter-term option, assuming you continue paying approximately KRW 1,584,000 per month, the loan would be paid off approximately 4 years and 3 months earlier.
The important point is that both options involve repaying KRW 30,000,000 of principal.
The difference comes from how quickly you reduce the remaining principal afterward.
Reducing monthly payments focuses on easing your household's regular financial burden, while shortening the loan term focuses on maintaining the pace of principal repayment to reduce interest accumulated over time.
However, you must confirm with your financial institution whether shortening the loan term is permitted and how the repayment schedule can be modified for your particular loan product.
3. How Much Does Total Interest Differ After Repaying KRW 30,000,000?
With equal monthly principal-and-interest payments, total interest depends not only on the outstanding loan balance but also on how quickly the principal is repaid. Therefore, comparing monthly payments alone makes it difficult to accurately assess the actual savings.
Keeping the previous assumptions unchanged and comparing only the interest incurred after the partial repayment produces the following results.
| Scenario | Total Future Interest |
|---|---|
| No partial repayment | Approximately KRW 175,050,000 |
| Repay KRW 30,000,000 and reduce monthly payments | Approximately KRW 157,540,000 |
| Repay KRW 30,000,000 and shorten the loan term | Approximately KRW 132,500,000 |
<text color="secondary" size="xs">Author's calculations. Assumes a fixed annual interest rate of 4%, equal monthly principal-and-interest payments, and excludes early repayment fees and other costs. The shorter-term scenario assumes that the existing monthly payment is maintained, with the final installment adjusted.</text>
If you repay KRW 30,000,000 early and lower your monthly payment, your future interest costs decrease by approximately KRW 17,510,000 compared with making no partial repayment.
By contrast, maintaining your existing monthly payment while shortening the loan term can save approximately KRW 42,550,000 in interest.
The difference in future interest between the two approaches is approximately KRW 25,040,000.
This does not mean that shortening the loan term is always the better choice. Because your monthly expenses do not decrease under this option, it may be harder to manage a decline in income or unexpected living expenses.
The calculations will also change if the interest rate fluctuates or the repayment method differs.
4. Will Your Monthly Payment Automatically Decrease If You Make a Partial Repayment Through Your Banking App?
Whether your monthly payment automatically decreases after a partial repayment depends on your loan agreement and how your financial institution processes the repayment.
An early repayment means paying back principal ahead of schedule, while recalculating monthly payments or changing the maturity date concerns how the remaining repayment schedule will be adjusted.
Therefore, before requesting a repayment, check the following.
1. Whether the remaining principal and interest payments are automatically recalculated after a partial early repayment
2. Whether you can shorten the loan term while maintaining the existing monthly payment
3. Whether changing the repayment method requires a separate application or approval process
4. How interest is settled between the repayment date and the next automatic debit date
5. How much the early repayment fee and other charges will be
In particular, even if your banking app supports partial repayments, you should not assume that it also supports your preferred repayment schedule adjustment.
When contacting your bank's customer service department, you can make the following request.
If possible, obtain projected repayment schedules for both before and after the partial repayment and compare them.
5. Are the Calculations the Same for Equal Principal-and-Interest Payments and Equal Principal Repayments?
Both repayment methods can reduce future interest costs when a partial repayment lowers the outstanding loan balance. However, because the principal and interest components of each monthly payment differ, repaying the same amount can produce different changes in monthly payments.
According to official explanations from the Korea Housing Finance Corporation and the Housing and Urban Fund, equal principal-and-interest repayment is structured so that the combined monthly principal and interest payment remains constant.
By contrast, under equal principal repayment, a fixed amount of principal is repaid each month. As a result, interest decreases over time, and the total monthly payment also declines.
For example, consider an equal principal repayment mortgage with an outstanding balance of KRW 300,000,000, an annual interest rate of 4%, and 25 years remaining. The principal repayment for the first month would be KRW 1,000,000.
The first month's interest would be KRW 1,000,000, bringing the total payment to KRW 2,000,000.
Assuming you make a partial repayment of KRW 30,000,000 and redistribute the remaining KRW 270,000,000 over 300 months, the results would be as follows.
Monthly principal repayment: KRW 1,000,000 → KRW 900,000
First month's interest: KRW 1,000,000 → KRW 900,000
Total payment for the first month: KRW 2,000,000 → KRW 1,800,000
This represents a reduction of approximately KRW 200,000 in the first month's payment.
However, even with equal principal repayment, the actual outcome depends on how the remaining principal repayment schedule is adjusted after the partial repayment.
6. Will You Have to Pay an Early Repayment Fee When Making a Partial Repayment?
A fee may apply when you partially repay a mortgage. However, the same fee rate or exemption conditions do not apply to every loan.
The factors you generally need to check include the principal amount being repaid early, the contractual fee rate, the time elapsed since the loan was originated, and any applicable exemption conditions.
For example, if the fee rate is 0.6% and you simply assume that this rate applies to the entire repayment principal of KRW 30,000,000, the fee would be KRW 180,000.
KRW 30,000,000 × 0.6% = KRW 180,000
In practice, however, the fee may decrease depending on how much time has elapsed, or product-specific exemptions may apply.
Therefore, KRW 180,000 is only an illustrative calculation, not the amount you will necessarily be charged.
In particular, government-backed mortgage products and ordinary bank mortgages may have different contractual conditions and should not be treated as identical.
Before deciding to make a partial repayment, check the fee quoted by your bank for your intended repayment date.
7. If You Have KRW 30,000,000 in Spare Cash, Should You Use It to Repay Mortgage Principal First?
Partially repaying your principal can reduce future loan interest, but it also reduces your available cash by the same amount. Therefore, rather than deciding based solely on your loan interest rate, you should also consider your emergency savings and planned future expenses.
It is particularly important to distinguish among the following three situations.
If Your Monthly Mortgage Payment Is a Financial Burden
Reducing your monthly payment may be an appropriate option. However, you should first confirm with your bank whether a reduction is possible and what the new payment would be.
If Your Income Is Stable and You Want to Reduce Total Interest
Shortening the loan term may be advantageous. With the same interest rate and principal conditions, paying down principal more quickly reduces the long-term interest burden.
If You Expect to Need a Large Amount of Cash Soon
If you have planned expenses such as home repairs, moving costs, or education fees, consider the risk of running short of cash after making a partial repayment.
Using all your available cash to pay down your mortgage is not always a financially sensible choice.
8. Final Checklist Before Making a Partial Early Repayment
When making a partial mortgage repayment, checking only how much the principal balance will decrease is not enough.
Before submitting a repayment request, review the following items.
Current outstanding loan balance and applicable interest rate
Remaining loan term and repayment method
Whether monthly payments can be recalculated after a partial repayment
Whether the loan term can be shortened
Early repayment fees and exemption conditions
Living expenses and emergency savings remaining after repayment
For an actual decision, the repayment schedule issued or provided by your bank is the most important reference.
Even if you repay the same KRW 30,000,000, your choice will depend on whether your goal is to reduce monthly payments or pay off the loan sooner.
Ultimately, the benefit of repaying KRW 30,000,000 of principal goes beyond simply reducing your outstanding loan balance by KRW 30,000,000. If you can lower your monthly payments, you will have more room in your household budget. If you can shorten the loan term, you may achieve greater long-term interest savings.
The key is to compare the projected monthly payments and total future interest under both options before pressing the repayment button.
<text color="secondary" size="xs">Information verified as of 2026-10-14. The calculations in this article are hypothetical examples for explanatory purposes. Actual repayment amounts and fees depend on the loan agreement and the financial institution's calculations.</text>