

2026 VAT Preliminary Notice Below KRW 500,000: Exemption from Collection and Differences from the Final VAT Return
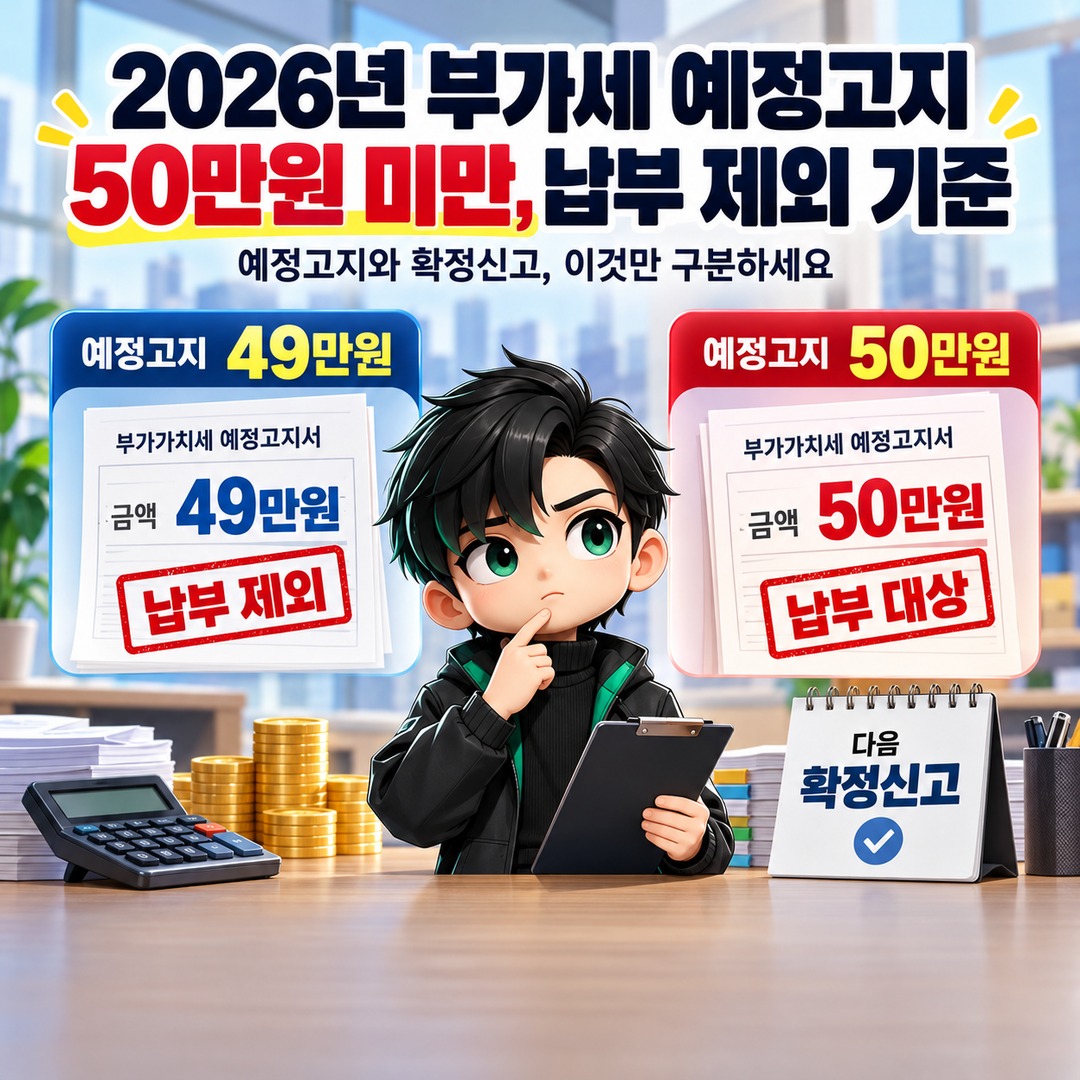
If the VAT amount stated in a preliminary tax notice for October 2026 is below KRW 500,000, that amount will not be collected. However, this does not mean the tax itself is exempt. Individual general VAT taxpayers and small corporations meeting certain requirements must distinguish between exemption from preliminary collection and their obligation to file a subsequent final VAT return.
In particular, KRW 490,000 and KRW 500,000 lead to different outcomes. If the preliminary notice amount is exactly KRW 500,000, it does not qualify as being below KRW 500,000.
*Verification basis: 2026-10-17, Article 48 of the Value-Added Tax Act and guidance from the National Tax Service (NTS)*
Why Is a VAT Preliminary Notice Below KRW 500,000 Not Collected?
Article 48, Paragraph 3 of the Value-Added Tax Act stipulates that an amount subject to collection through a preliminary tax notice will not be collected if it is below KRW 500,000.
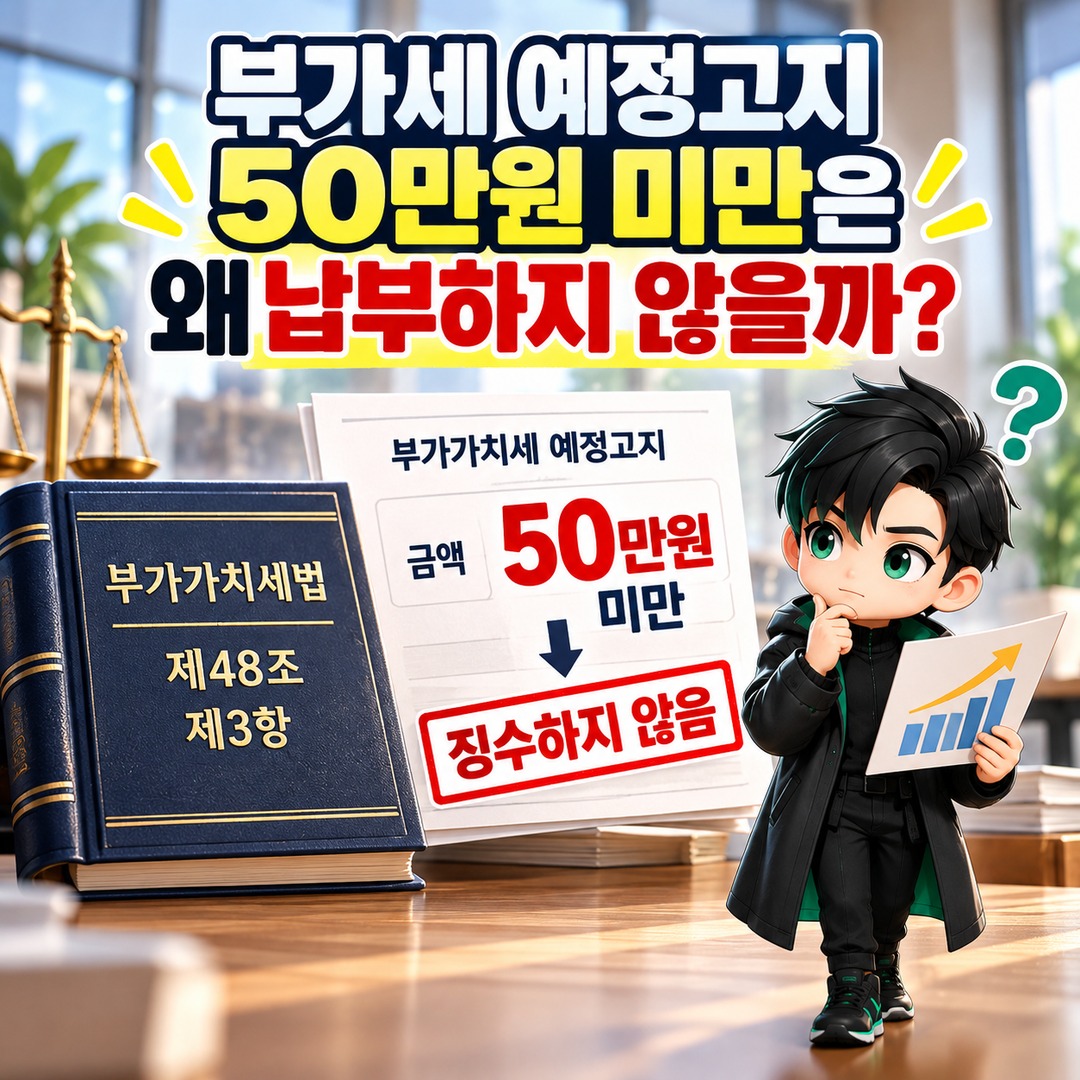
The important distinction is that the threshold does not refer to sales revenue of KRW 500,000 or total VAT of KRW 500,000. It refers to whether the amount the tax office intends to collect through a preliminary notice is below KRW 500,000.
A preliminary VAT notice is a system in which the tax office determines an advance payment based on the VAT paid during the previous tax period, rather than requiring businesses to calculate and report VAT themselves each time.
For individual general VAT taxpayers and small corporations meeting certain requirements, the preliminary notice amount is generally calculated using 50% of the VAT paid during the preceding 6 months.
For example, if the reference VAT payment for the previous tax period was KRW 900,000, the calculated preliminary notice amount would be KRW 450,000. Because this is below KRW 500,000, it is excluded from preliminary collection.
By contrast, if the reference VAT payment was KRW 1,000,000, the calculated preliminary notice amount would be KRW 500,000, so it would not qualify for exclusion based on the amount threshold.
KRW 490,000 vs. KRW 500,000: What Is the Actual Difference?
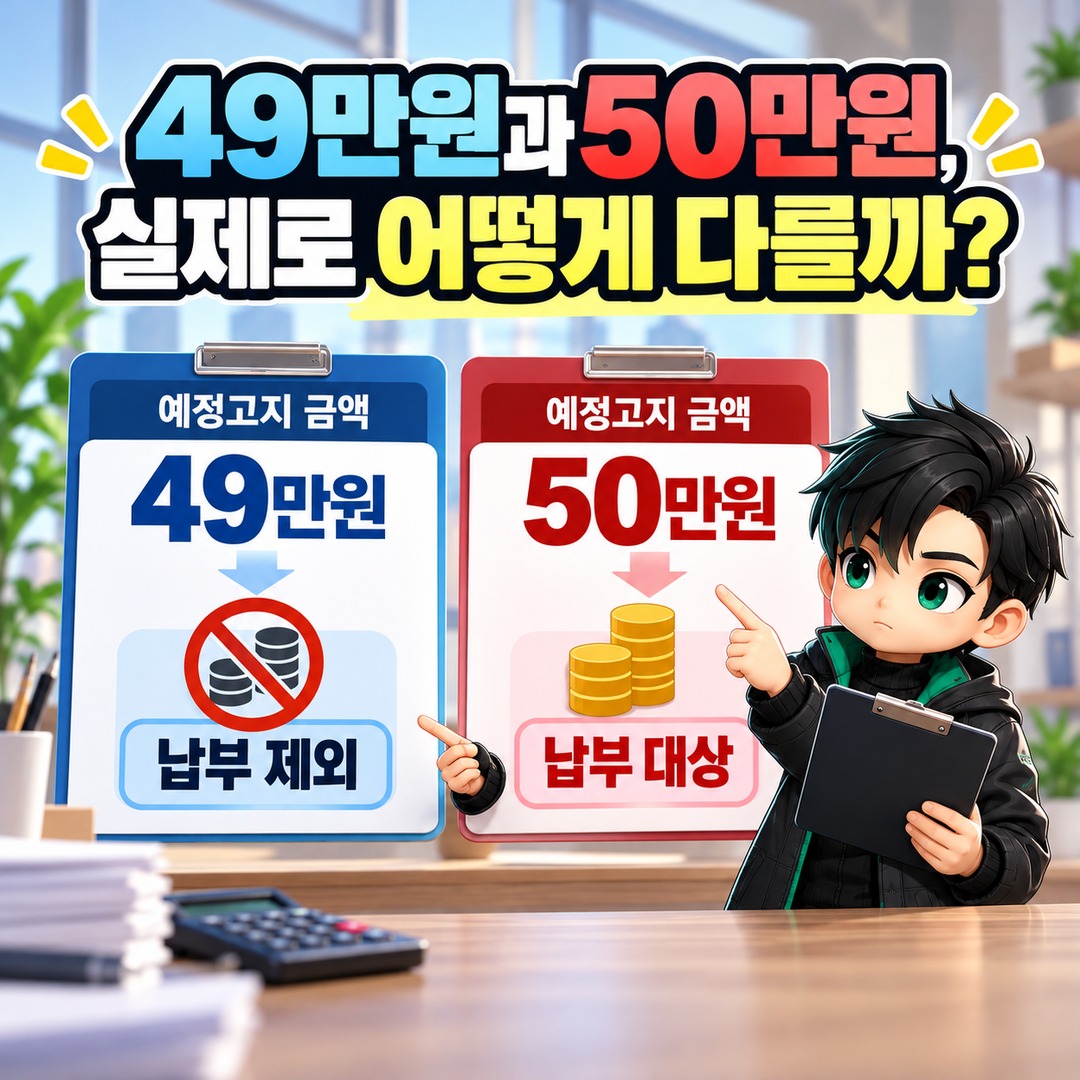
The difference becomes clear when eligibility is determined using the calculated preliminary notice amount.
| Calculated preliminary notice amount | Collection status |
|---|---|
| KRW 300,000 | Excluded because it is below KRW 500,000 |
| KRW 490,000 | Excluded because it is below KRW 500,000 |
| KRW 500,000 | Not excluded based on the amount threshold |
| KRW 700,000 | Not excluded based on the amount threshold |
The table compares only the amount threshold, assuming that no other grounds for exclusion apply.
When calculating preliminary VAT, 50% of the VAT paid during the previous tax period is applied, adjustments such as statutory deductions and corrections are reflected, and fractional amounts below KRW 1,000 are discarded.
Therefore, rather than determining whether a notice will be issued solely from the amount paid previously, it is more accurate to check the actual tax notice details.
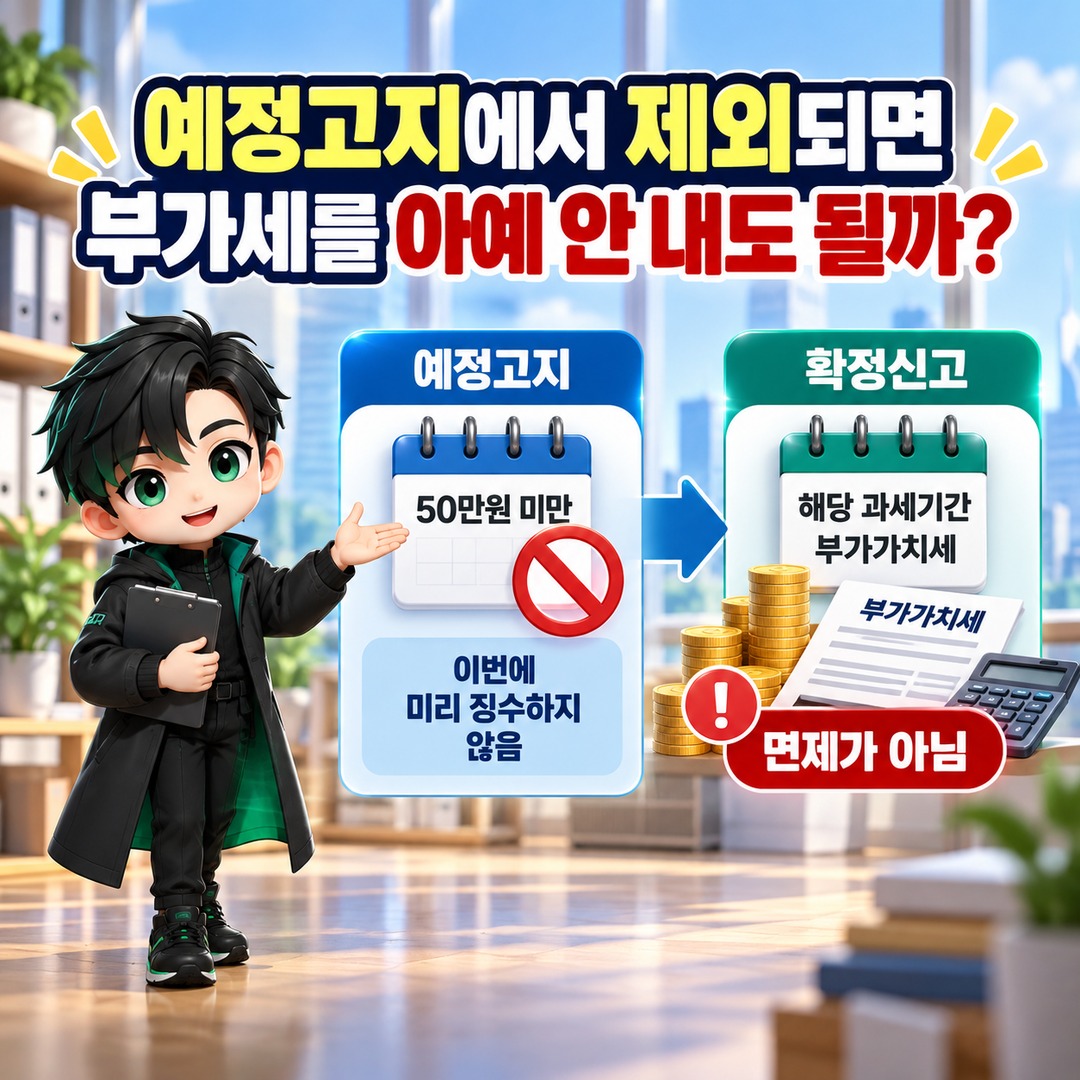
Does Exclusion from Preliminary Collection Mean No VAT Is Payable at All?
No. Exclusion from preliminary collection means the tax will not be collected in advance at this stage. It does not mean VAT for the relevant tax period is exempt.
Preliminary VAT notices and final VAT returns serve different purposes.
A preliminary notice is a procedure for paying a specified amount in advance based on the tax liability from the previous tax period. By contrast, a final VAT return calculates the amount payable or refundable based on actual sales, purchases, and other relevant transactions during the tax period.
The preliminary notice for October 2026 takes place during the 2 VAT tax period. For individual general VAT taxpayers, the final return for the 2 tax period covers business activity from July 2026 through December and is filed in January of the following year.
Even if no payment was required this time because the preliminary notice amount was below KRW 500,000, VAT may still be payable when the final return is filed.
Conversely, any amount already paid through a preliminary notice is deducted as tax previously paid when filing the final return.
In other words, exclusion from preliminary collection and the actual final VAT liability must be assessed separately.
Do Individual Businesses and Corporations Follow the Same Rules?
The rule excluding amounts below KRW 500,000 from collection applies to individual businesses and small corporations that are subject to preliminary VAT notices. However, not all businesses are subject to the same preliminary notice system.
The National Tax Service identifies individual general VAT taxpayers and small corporations whose total supply value during the previous tax period was below 1 hundred million 5 ten million as businesses subject to preliminary VAT notices.
Corporations generally operate under a system of filing preliminary VAT returns and paying the corresponding tax, so it is necessary to determine first whether a corporation is subject to a preliminary notice.
Simplified VAT taxpayers also follow a different filing and payment system from general VAT taxpayers. Article 66 of the Value-Added Tax Act applies to preliminary assessments for simplified VAT taxpayers, and that provision also includes a rule excluding amounts below KRW 500,000 from collection.
However, the filing obligations and tax periods applicable to simplified VAT taxpayers are not the same as those for general VAT taxpayers. Therefore, their overall obligations should not be determined solely by the KRW 500,000 threshold.
What If You Have Not Received a Preliminary VAT Notice for October 2026?
It is advisable not to assume that you have been excluded from preliminary collection simply because you have not received a notice.
In addition to cases where the preliminary notice amount is below KRW 500,000, other statutory grounds for exclusion may apply, including changes in VAT taxpayer classification.
In particular, a business that changed from simplified VAT taxation to general VAT taxation as of the first day of the relevant tax period qualifies for exclusion from preliminary collection under Article 48 of the Value-Added Tax Act.
Businesses can check their circumstances in the following order.
1. Check the business's current VAT taxpayer classification through Hometax, the Korean National Tax Service's online tax platform.
2. Review the preliminary VAT notice records and the amount of tax assessed for payment.
3. Determine whether the preliminary notice amount is below KRW 500,000 or whether another ground for exclusion applies.
4. If the notice details differ from expectations or the payment obligation is unclear, contact the tax office with jurisdiction over the business.
Checking the actual assessment and payment records is more important than whether a paper notice has been received.
What If Sales Have Declined but the Preliminary VAT Notice Amount Is High?
Even businesses subject to preliminary VAT notices may be permitted to file a preliminary VAT return under certain conditions if their business performance has deteriorated because of a suspension of operations, a business downturn, or similar circumstances.
Article 48, Paragraph 4 of the Value-Added Tax Act allows businesses to choose preliminary filing in such circumstances.
The National Tax Service also explains that preliminary filing is available when business performance has deteriorated or when a business seeks an early refund. If a valid preliminary return is filed, the existing preliminary tax notice is canceled.
Therefore, the fact that a preliminary notice amount is KRW 500,000 or more does not necessarily mean that every business must pay exactly the amount stated in the notice.
However, preliminary filing is permitted only when the statutory grounds and requirements are satisfied, so businesses must verify whether they are eligible to file.
What Should You Check About the October 2026 VAT Preliminary Notice?
The most important point regarding this preliminary notice is to distinguish the amount assessed for advance payment from the obligation to file a final VAT return.
If the calculated preliminary notice amount is below KRW 500,000, that amount will not be collected. If it is exactly KRW 500,000 or more, it is not excluded based on the amount threshold, although other grounds for exclusion or eligibility for preliminary filing may still apply.
Even when a business is excluded from preliminary collection, its subsequent final VAT filing obligation does not automatically disappear.
If you are unsure whether you must pay VAT for October 2026, first check the actual assessed amount and payment deadline in your preliminary VAT notice records on Hometax, and review the filing obligations applicable to your VAT taxpayer classification.
※ This article is provided for reference purposes to help readers understand market trends and does not constitute an investment recommendation concerning any specific security or asset. Final decisions and responsibility for investments rest with the individual.
Related Articles
October 2026 VAT Preliminary Notice: If Sales Have Declined, Check the 1 out of 3 Threshold First