

No October 2026 VAT Preliminary Tax Notice? The Exemption Threshold Below KRW 500,000 and How to Check on Hometax
Not receiving a October 2026 VAT preliminary tax notice does not necessarily mean you are exempt from payment. If the preliminary tax assessment is below KRW 500,000, you may be excluded from receiving a notice. However, you could still be required to pay even if the notice has not arrived. First, check your eligibility for preliminary assessment and your assessment records on Hometax.
For individual general VAT taxpayers and small corporations in particular, the outcome depends on the business category and the VAT paid during the previous tax period.
*Reference date: 2026-10-13, based on publicly available guidance from the National Tax Service*
1. 4 Common Reasons Why You May Not Receive a VAT Preliminary Tax Notice
VAT preliminary tax notices are not issued to all businesses under the same rules. Businesses may be excluded depending on their tax classification, previous tax payments, and whether their VAT classification has changed.
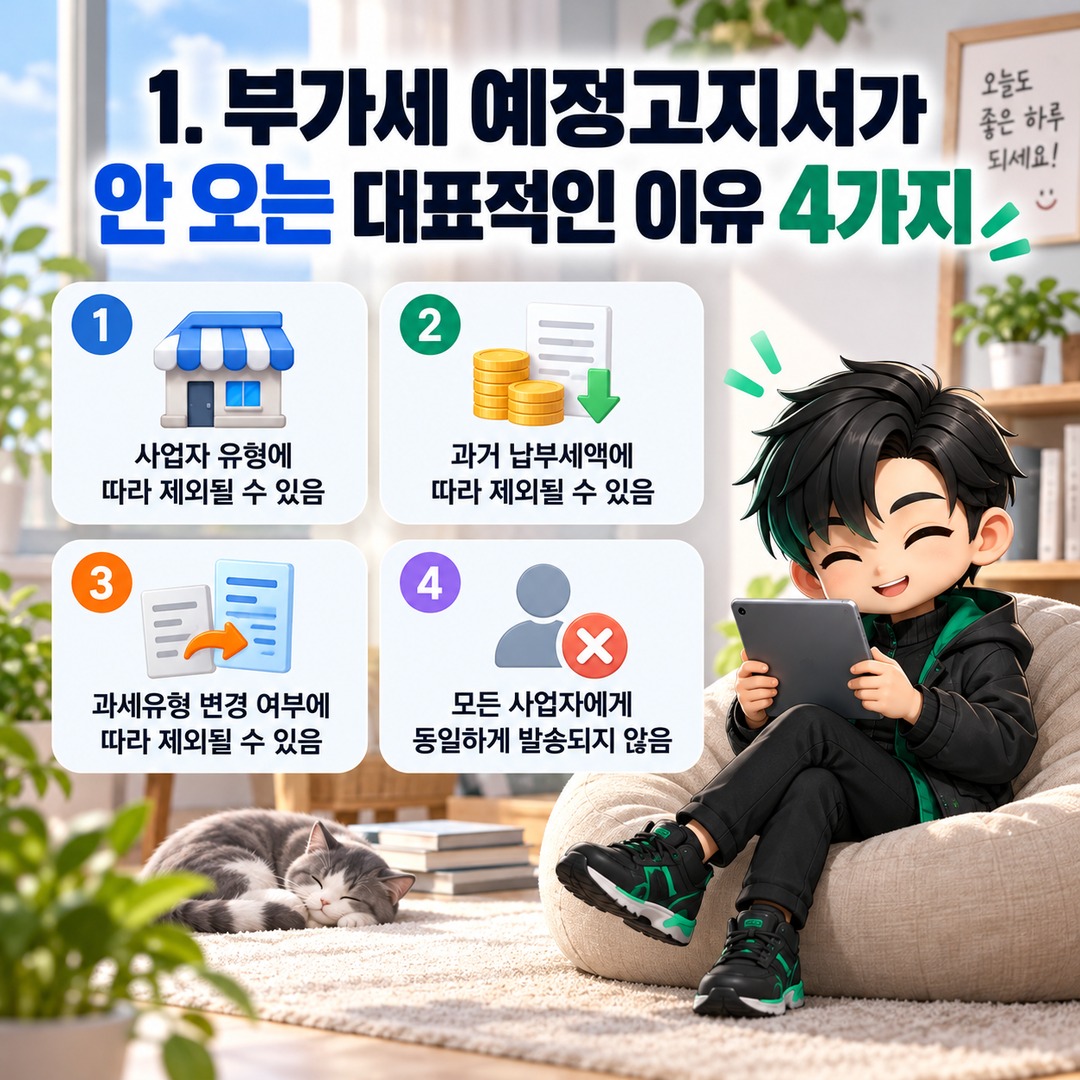
Common situations include the following.
| Category | Reason No Notice Is Received |
|---|---|
| Preliminary tax assessment below KRW 500,000 | Falls under the minimum collection threshold |
| Conversion from simplified VAT taxation to general VAT taxation | Excluded when the conversion takes effect as of the beginning of the tax period |
| Ordinary corporate taxpayer | May be required to file a preliminary VAT return instead of receiving a preliminary tax notice |
| Notice not received | The business is subject to preliminary assessment but did not receive the notice by mail or another delivery method |
The important distinction is that being excluded from preliminary assessment and simply not receiving a notice are entirely different situations.
The National Tax Service applies the preliminary assessment system to individual general VAT taxpayers and small corporations meeting specified requirements.
By contrast, corporate taxpayers who are not subject to preliminary assessment may have a separate obligation to file a preliminary VAT return.
Therefore, you should not assume that no tax return or payment is required simply because you have not received a notice.
2. Below KRW 500,000 Means Exemption, but What Happens at Exactly KRW 500,000?
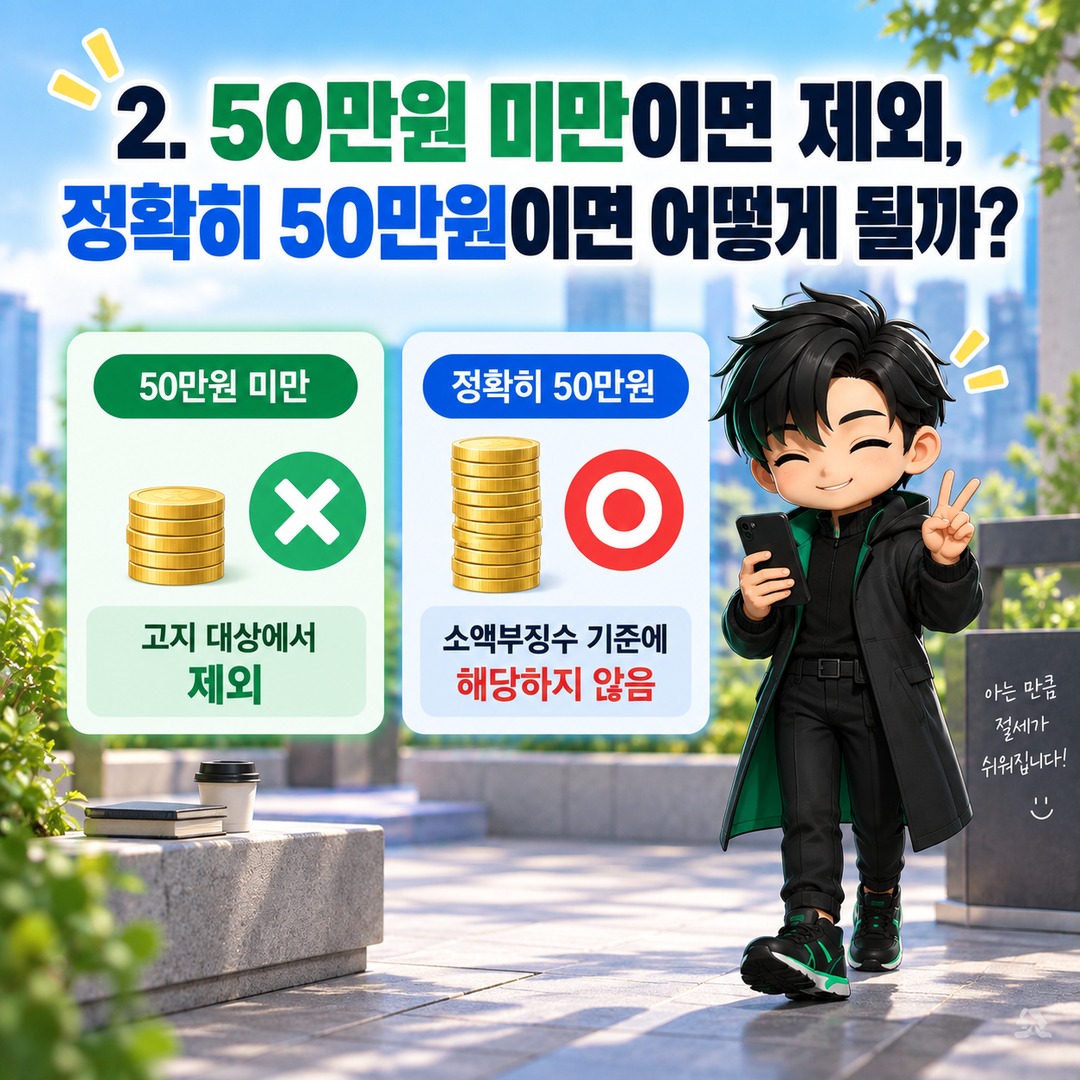
If the preliminary tax assessment is exactly KRW 500,000, it does not qualify for the minimum collection exemption.
This is because the statutory exemption threshold is not 'KRW 500,000 or less' but 'less than KRW 500,000'.
Generally, the preliminary tax assessment is calculated by multiplying the VAT paid during the previous 6-month tax period by 50%.
For the October 2026 preliminary assessment, the calculation is generally based on VAT paid for the period from January 2026 through June.
Preliminary Tax Assessment Formula
VAT paid in the previous tax period × 50%
This is the general calculation method. The actual assessment amount must be verified against the National Tax Service's official determination.
For example, the following differences arise depending on the VAT paid during the previous tax period.
| VAT Previously Paid | Amount Calculated Using 50% | Result |
|---|---|---|
| KRW 800,000 | KRW 400,000 | Excluded from preliminary assessment |
| KRW 990,000 | KRW 495,000 | Excluded from preliminary assessment |
| KRW 1,000,000 | KRW 500,000 | Subject to preliminary assessment based on the amount threshold |
| KRW 2,000,000 | KRW 1,000,000 | Subject to preliminary assessment based on the amount threshold |
| KRW 4,000,000 | KRW 2,000,000 | Subject to preliminary assessment based on the amount threshold |
*These amounts are illustrative calculations by the author, assuming no other grounds for exclusion apply.*
In particular, a business that previously paid KRW 990,000 and one that paid KRW 1,000,000 may receive different preliminary assessment outcomes despite a difference of only KRW 10,000.
Furthermore, exclusion from preliminary assessment because the amount is below KRW 500,000 does not mean VAT itself is waived. The actual tax liability for the relevant period is calculated when the final VAT return is filed.
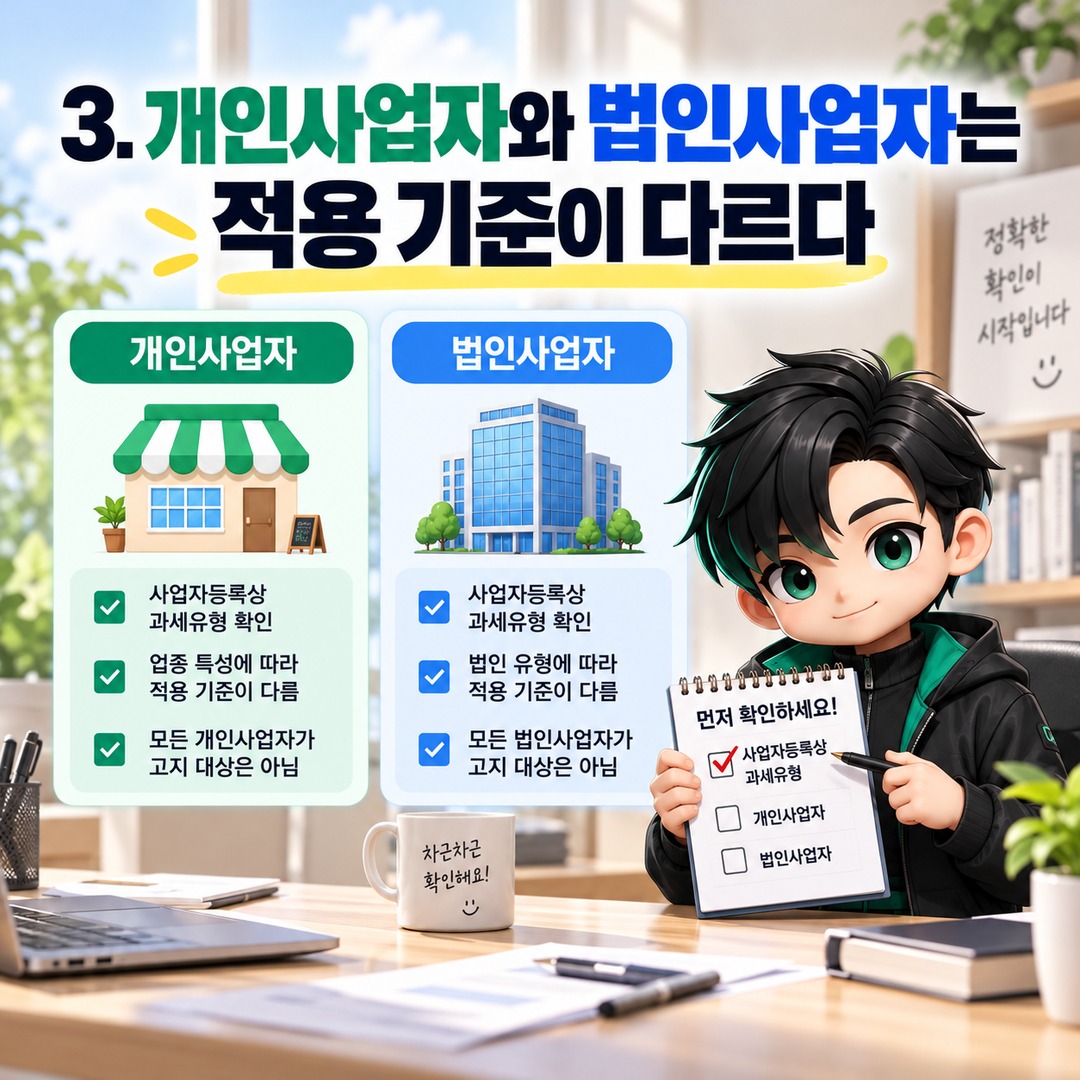
3. Different Rules Apply to Individual Businesses and Corporations
If you have not received a preliminary tax notice, the first thing to check is the VAT classification shown on your business registration.
Not all individual business owners pay VAT under the same system.
| Business Category | October VAT Treatment |
|---|---|
| Individual general VAT taxpayer | Generally subject to preliminary assessment |
| Small corporation | Subject to preliminary assessment if eligibility requirements are met |
| Other corporate taxpayers | Generally required to file a preliminary VAT return |
| Individual simplified VAT taxpayer | Subject to a separate system from preliminary assessment for general VAT taxpayers |
A small corporation is defined as a corporation whose total taxable supply value during the previous 6-month tax period was less than 1억5천만원.
The taxable supply value generally refers to sales revenue excluding VAT.
For example, a corporation with a taxable supply value of 1억4천만원 during the previous tax period may meet the small-corporation threshold. Conversely, a corporation with a taxable supply value of exactly 1억5천만원 does not satisfy the requirement of being 'less than 1억5천만원'.
However, even if a corporation meets the small-corporation criteria, it must check whether any other grounds for exclusion apply.
Simplified VAT taxpayers are also subject to a filing and payment system separate from the April and October preliminary assessments applicable to general VAT taxpayers.
Therefore, applying only the KRW 500,000 threshold without checking the business's VAT classification would be inaccurate.
4. How to Check Preliminary Assessment Eligibility and Tax Amounts on Hometax
If you have not received a notice, the most reliable approach is to check directly through the National Tax Service's Hometax system. You can separately verify whether you are subject to preliminary assessment and the amount actually payable.
Steps to Check on Hometax Using a PC
Visit National Tax Service Hometax and log in
Select 'Tax Filing' from the top menu
Select 'VAT Filing'
Under 'View Filing Assistance Materials', check 'Check Preliminary Assessment (Imposition) Eligibility'
Check the amount under 'View Preliminary Assessment (Imposition) Tax Amount'
Another option is to log in to Hometax and review tax notices related to payments and outstanding taxes under 'My Hometax'.
Menu names and layouts may change when the Hometax interface is updated.
If online access is difficult, you can contact the National Tax Consultation Center at 126 or your local tax office.
When checking, it is advisable to have your business registration number and the relevant tax period available.
5. If No Assessment Record Appears, Can You Do Nothing in October 2026?
The absence of an assessment record does not automatically eliminate all filing and payment obligations.
You must determine the appropriate action after checking your business category and the reason for exclusion from preliminary assessment.
The situations can be distinguished as follows.
① Individual General VAT Taxpayer Excluded Because the Amount Is Below KRW 500,000
Normally, without filing a separate October preliminary VAT return, the business reports its operating results for the second half of 2026 when filing the next final VAT return.
② Ordinary Corporate Taxpayer Required to File a Preliminary Return
Even without a preliminary tax notice, a preliminary VAT return may be required for business activity during the period from 2026-07-01 through September 30.
The preliminary VAT filing and payment deadline announced by the National Tax Service for October 2026 is October 26.
③ Business Subject to Preliminary Assessment but the Notice Was Not Received
You must check the actual assessment record and payment amount on Hometax.
The general payment deadline for the October 2026 preliminary assessment is November 2.
④ Business Converted from Simplified VAT Taxation to General VAT Taxation
Check whether your VAT classification changed as of 2026-07-01. Exclusion from preliminary assessment and the obligation to file a final VAT return must be considered separately.
6. Frequently Asked Questions
Q. I Received a Preliminary Tax Notice Last Year but Not This Year. Is That Normal?
It may be normal.
Possible reasons include a change in VAT paid during the previous tax period that reduced the preliminary assessment below KRW 500,000, or a change in VAT classification.
However, you should verify the actual reason for exclusion through Hometax.
Q. If I Do Not Receive a Notice Because the Amount Is Below KRW 500,000, Does That Mean I Do Not Have to Pay Any Tax?
No.
Exclusion from preliminary assessment means no interim payment is required. It does not mean VAT is exempted.
When filing the final VAT return, the actual tax payable is calculated based on sales, purchases, deductions, and other applicable items.
Q. Should I Contact the Tax Office Directly If I Have Not Received a Notice?
You can check Hometax first.
If your preliminary assessment eligibility remains unclear, or the assessment records do not match your actual business classification, it is advisable to contact the National Tax Consultation Center or your local tax office.
7. Key Things to Check Now for October 2026
If you have not received a preliminary tax notice, check the following four items.
Whether your business is registered as an individual general VAT taxpayer, a simplified VAT taxpayer, or a corporate taxpayer
Whether 50% of the VAT paid during the previous tax period is below KRW 500,000
Whether your VAT classification changed as of 2026-07-01
Whether an actual preliminary assessment record exists on Hometax
The Most Important Thing Is to Distinguish Between 'No Notice Received' and 'No Payment Obligation'.
If you are excluded from preliminary assessment, check the final VAT filing schedule. If you are required to file a preliminary return, make sure to meet the separate filing deadline.
When checking your October 2026 VAT obligations, it is more accurate to verify your business classification registered with the National Tax Service and your actual assessment records before relying on whether a paper notice has arrived.