

October 2026 VAT Preliminary Notice: If Sales Have Declined, You May File a Preliminary Return Under the 1-in-3 Threshold
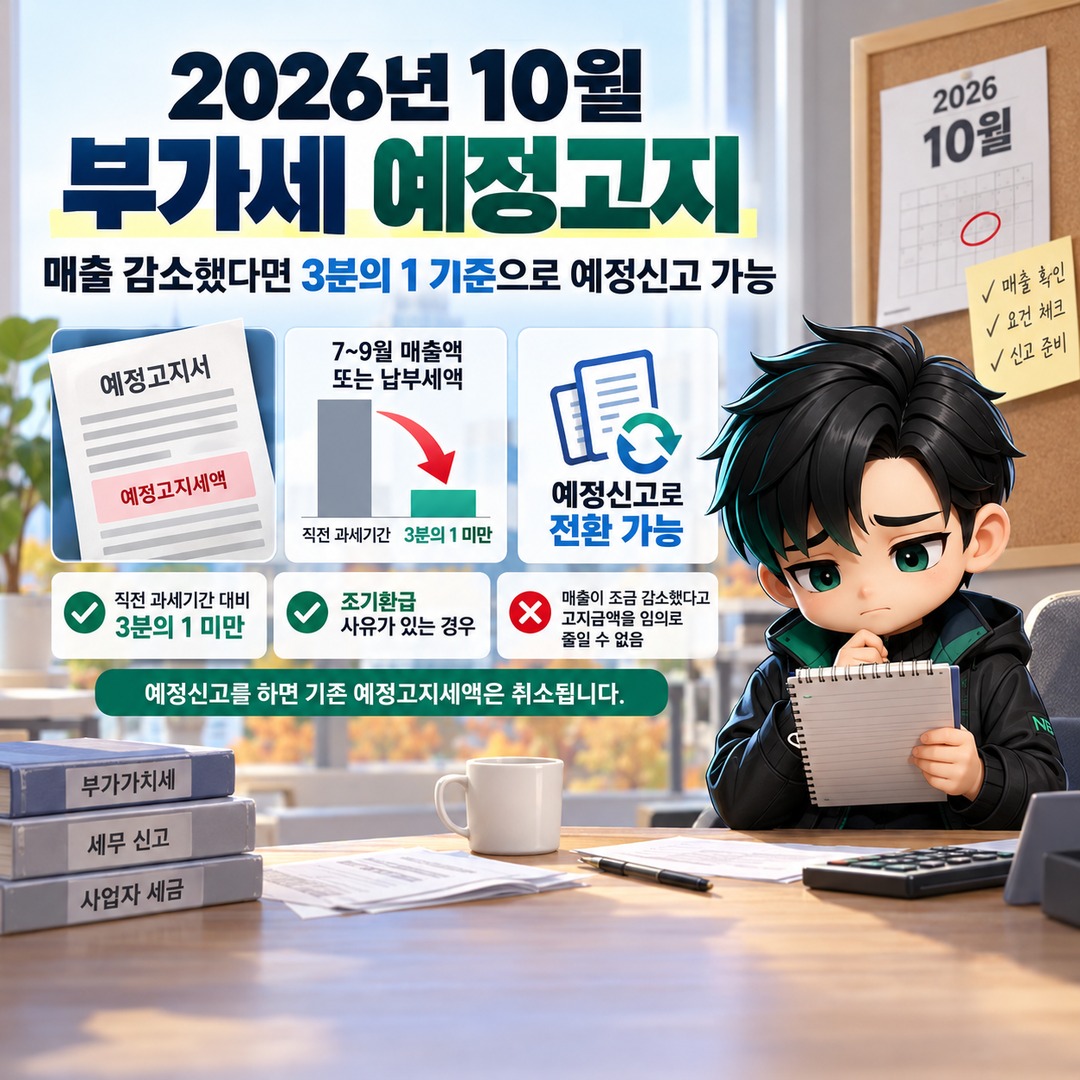
Even if you have received a October 2026 VAT preliminary tax notice, you may switch to filing a preliminary return if your sales or VAT payable for 7–September have fallen significantly below the prescribed threshold. A preliminary return is permitted if the amount is less than 1/3 of the previous tax period's comparison amount or if there are grounds for an early refund. Filing the return cancels the original preliminary tax assessment.
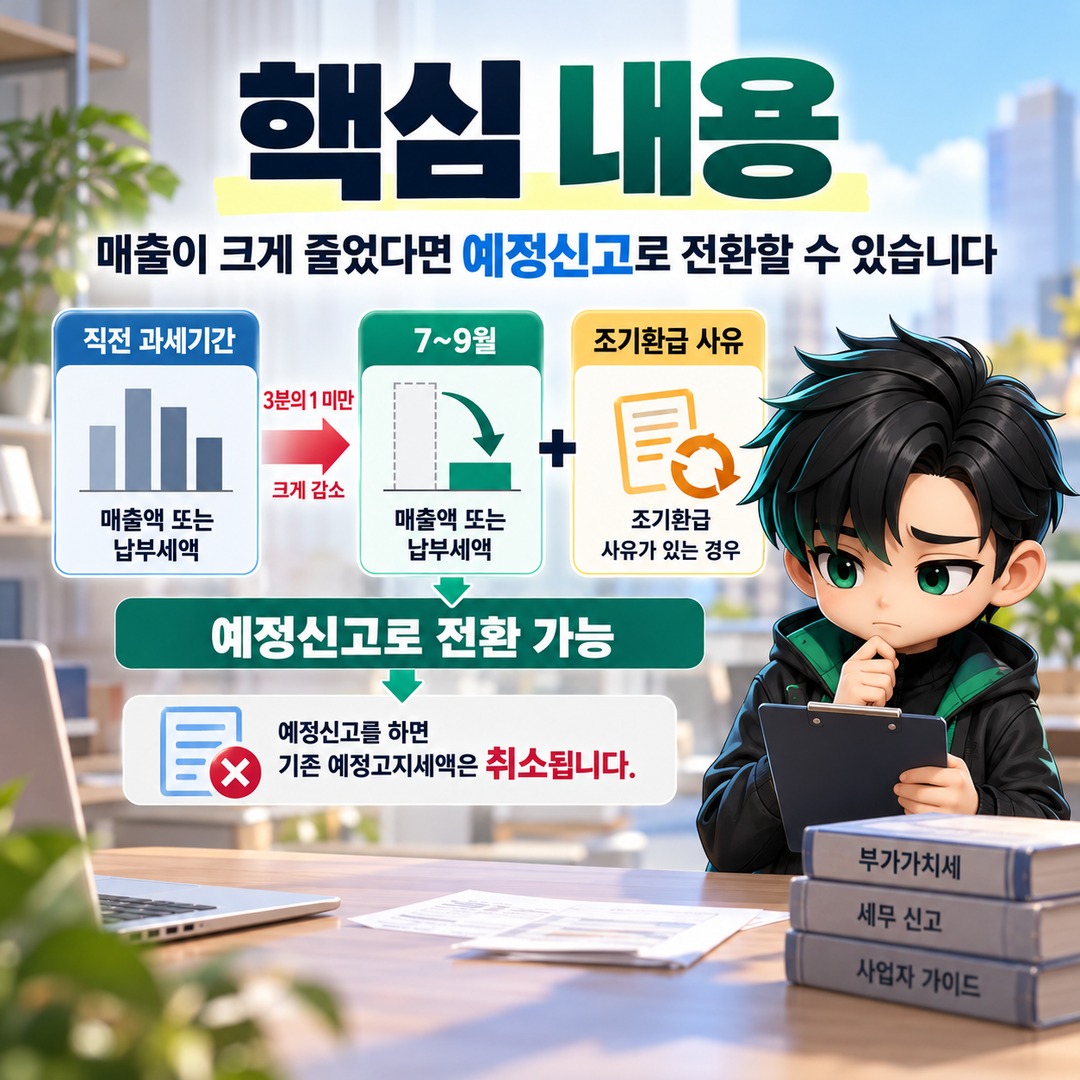
However, a slight decline in sales does not allow you to arbitrarily reduce the amount stated in the notice.
In October 2026, the deadline for filing a preliminary return also differs from the payment deadline for a preliminary tax notice. Business owners experiencing declining sales should compare their eligibility for filing with their actual VAT liability before paying the amount stated in the notice.
October 2026 VAT Preliminary Notice: Why Has the Tax Amount Stayed the Same Even Though Sales Have Declined?
This is because the preliminary VAT assessment is not calculated using actual sales for 7–September of the current year.
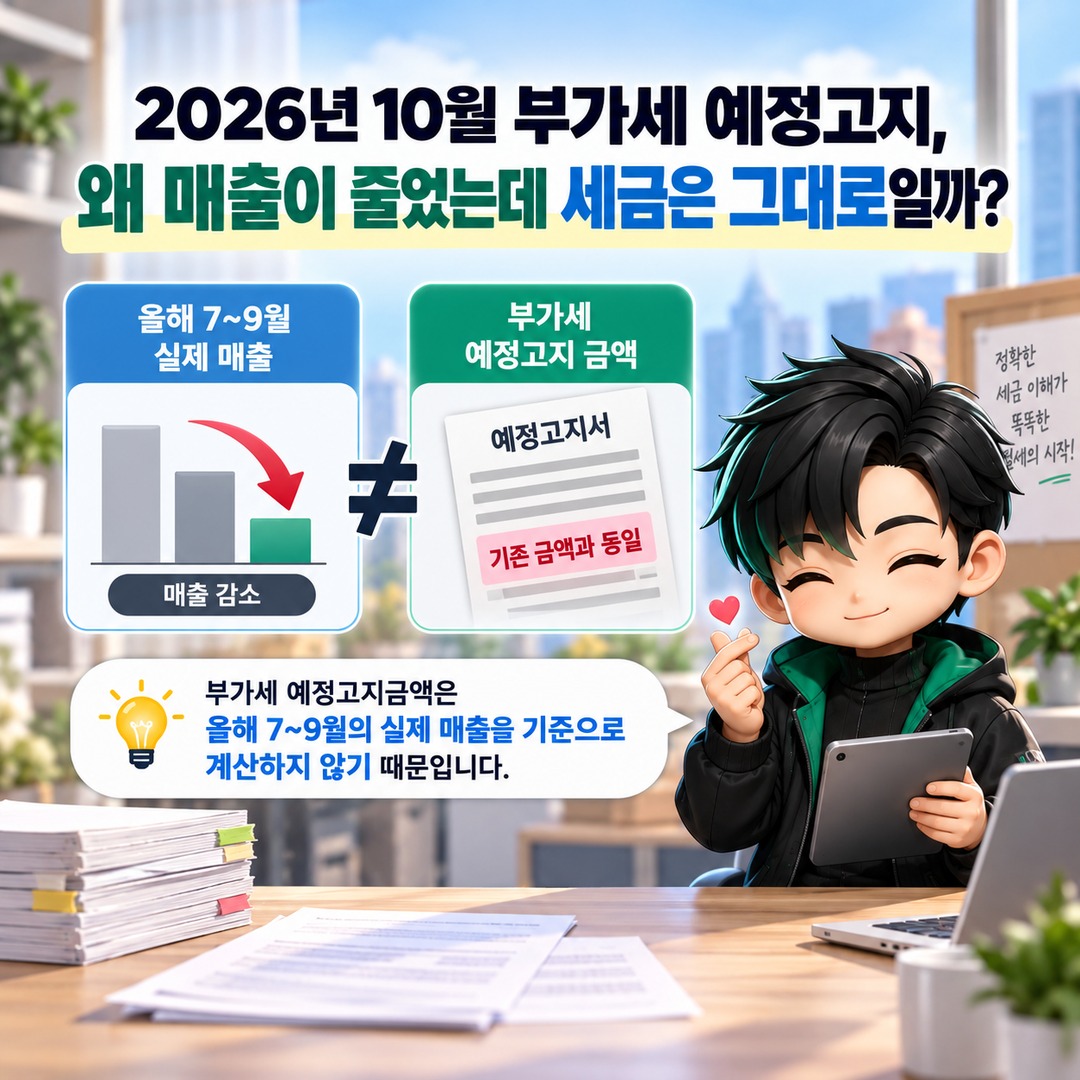
The National Tax Service (NTS) issues preliminary VAT assessments to individual general VAT taxpayers and small corporations meeting certain requirements, based on 50% of the VAT paid during the previous tax period.
The previous tax period used to calculate the October 2026 preliminary assessment runs from 2026-01-01 through June 30.
For example, if the VAT paid for the first half of the current year was KRW 4,000,000, the preliminary assessment would generally be KRW 2,000,000.
Even if sales for 7–September have fallen sharply, the assessment is calculated using the VAT paid during the previous first half of the year.
However, the preliminary assessment does not represent the final VAT liability for the second half of the year. It is an interim payment that is reconciled when the final VAT return is filed.
How Much Must Sales Decline to Qualify for a Preliminary Return?
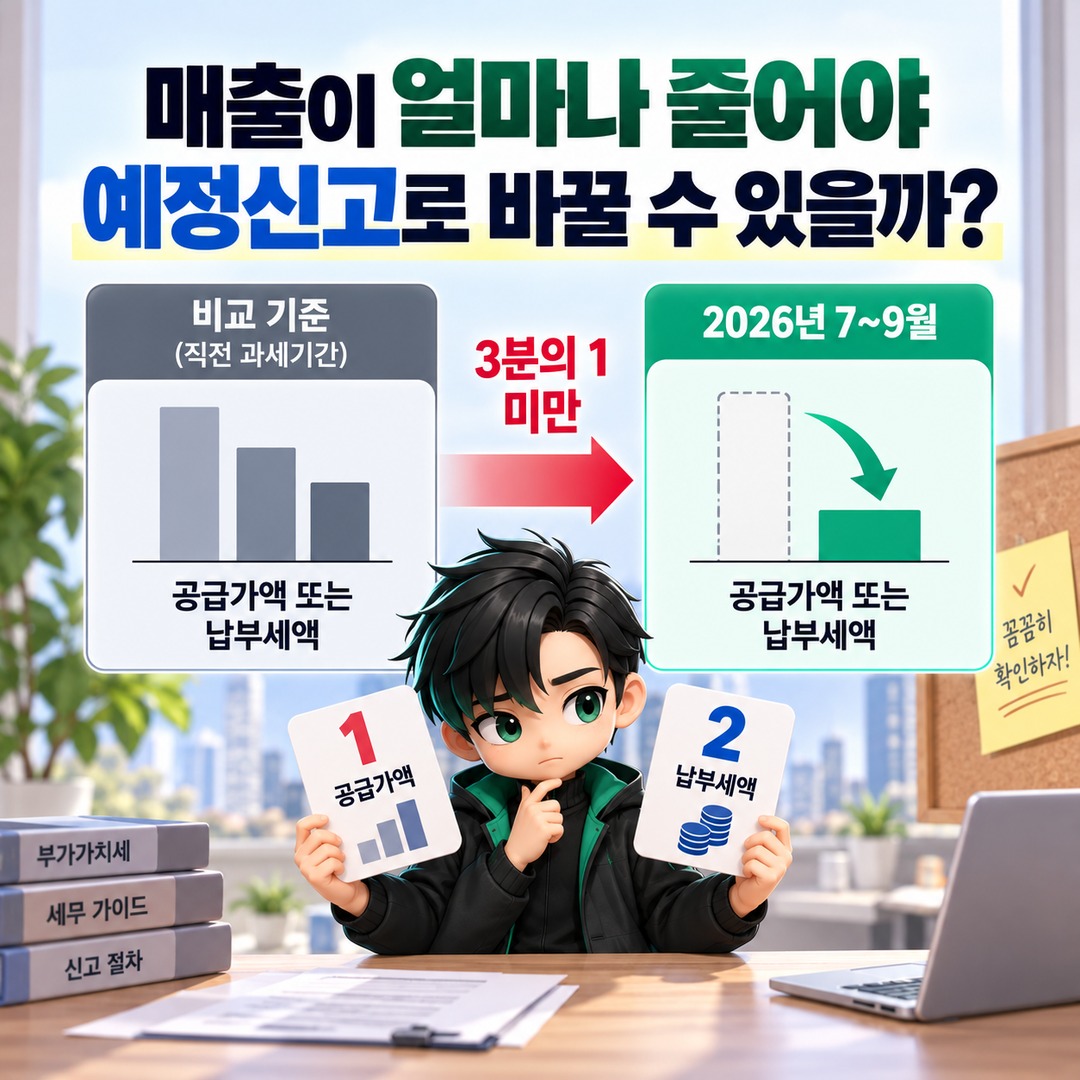
When determining whether you can switch to a preliminary return in October 2026, you must check whether the taxable supply value or VAT payable for 7–September is less than 1/3 of the applicable comparison amount.
Article 90 of the Enforcement Decree of the Value-Added Tax Act allows taxpayers to choose preliminary filing when business performance deteriorates because of a suspension of operations, poor business conditions, or similar circumstances.
| Comparison Item | Eligibility Threshold for Switching to Preliminary Filing |
|---|---|
| Taxable supply value | Less than 1/3 of the taxable supply value in the previous tax period |
| VAT payable | Less than 1/3 of the tax amount used as the basis for the preliminary assessment |
| Early refund | When applying for an early refund |
You do not need to satisfy both business-performance criteria. If either the taxable supply value or VAT payable meets the applicable threshold, you may consider filing a preliminary return.
Here, taxable supply value means sales revenue excluding VAT.
An amount exactly equal to 1/3 does not qualify as 'less than' the threshold. The amount must be strictly below it.
Calculating an Example of an Actual Sales Decline
Suppose an individual general VAT taxpayer had a taxable supply value of KRW 90,000,000 during the first half of 2026.
The 1-in-3 threshold is calculated as follows.
KRW 90,000,000 ÷ 3 = KRW 30,000,000
If the taxable supply value for 7–September of 2026 was KRW 25,000,000, it would be below KRW 30,000,000 and therefore meet the taxable supply value criterion.
Conversely, if the taxable supply value for 7–September was KRW 35,000,000, the taxpayer would not qualify based on taxable supply value alone. The VAT payable criterion or grounds for an early refund would then need to be checked separately.
The important point is that eligibility should not be determined solely by the percentage decline in sales.
Eligibility for Preliminary Filing and the Actual VAT Payable Are Two Different Calculations
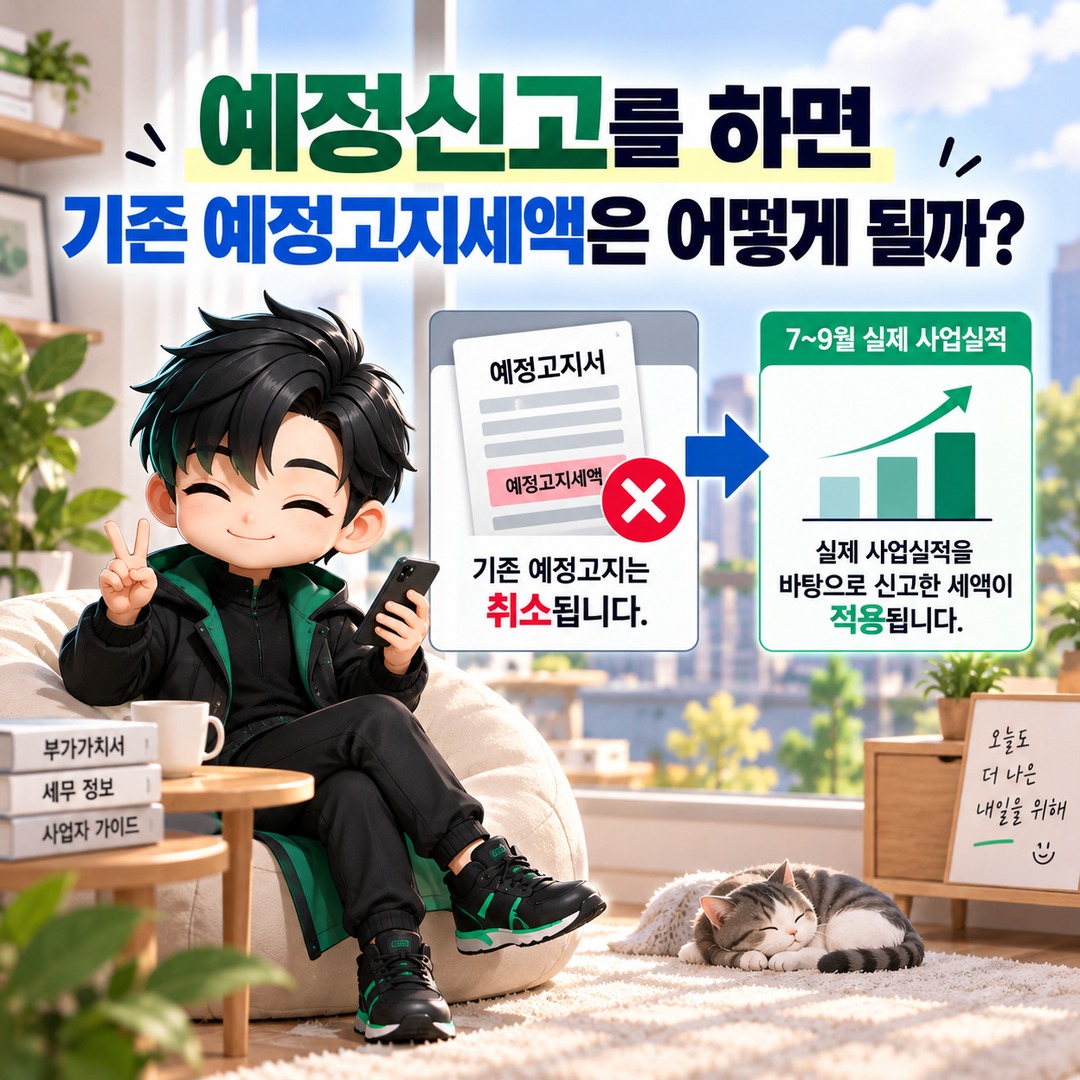
What Happens to the Existing Preliminary Tax Assessment If You File a Preliminary Return?
When an eligible business files a preliminary return, the original preliminary assessment is canceled, and the tax amount reported based on actual business performance for 7–September applies instead.
In 2026-10-05, the National Tax Service explained that the assessed amount is canceled when a taxpayer subject to preliminary assessment files a preliminary return because of poor business performance or grounds for an early refund.
For example, suppose a business has received a preliminary tax assessment of KRW 2,000,000.
If the business meets the preliminary filing requirements and its VAT payable, calculated using actual sales and purchase records for 7–September, is KRW 800,000, it would report and pay KRW 800,000 through the preliminary return process.
The difference between the two amounts is KRW 1,200,000.
This is a hypothetical calculation for illustration. Actual VAT liability must reflect output VAT and deductible input VAT, among other factors.
Therefore, filing a preliminary return does not necessarily reduce the tax liability of every business. The amount payable depends on the actual calculation.
October 2026 Preliminary Filing and Preliminary Assessment Payment Have Different Deadlines
In October 2026, it is important to distinguish the filing deadline from the payment deadline for an assessed amount.
The schedule announced by the National Tax Service is as follows.
| Category | Deadline in 2026 |
|---|---|
| Preliminary return filing and payment of reported tax | October 26 Monday |
| Payment of preliminary assessed tax | November 2 Monday |
| Taxpayers eligible for an automatic payment deadline extension | December 28 Monday |
The payment deadline for preliminary assessments was extended in consideration of potential delays in delivering tax notices caused by public holidays in early October and other factors.
One particularly important point is that November 2 is not the deadline for filing a preliminary return.
Taxpayers who choose preliminary filing because of poor business performance must complete their returns by October 26.
The National Tax Service also automatically extended the payment deadline to December 28 for certain businesses in areas affected by heavy rainfall and businesses affected by issues related to Homeplus.
This relief does not apply automatically to every business, so taxpayers should check whether they qualify for the extension.
How to Check Preliminary Filing Eligibility Through Hometax
First, check whether you are subject to a preliminary assessment and review the assessed amount in Hometax. Then compare your business performance for 7–September.
The National Tax Service provides the following navigation path for checking preliminary assessments.
1. Log in to the National Tax Service's Hometax website.
2. Under 'Tax Filing,' go to 'VAT Filing.'
3. Select 'View Filing Assistance Materials.'
4. Check your eligibility under 'Preliminary Assessment (Imposition) Subject Inquiry.'
5. Check the assessed amount under 'Preliminary Assessment (Imposition) Tax Amount Inquiry.'
After confirming the preliminary assessment amount, organize your sales and purchase records for the period from 2026-07-01 through September 30.
Next, compare the taxable supply value with the previous tax period and calculate the actual VAT payable to determine whether you meet the preliminary filing requirements.
You can file a preliminary return through the VAT filing menu in Hometax.
Starting with October 2026 filings, the National Tax Service provides prefilled information related to sales and purchases. However, business owners must verify that the prefilled information matches their actual transactions.
It is important to check that electronic tax invoices, credit card sales, cash receipts, input VAT deduction records, and other relevant information have not been omitted.
When Can You Not Choose Preliminary Filing Even If Sales Have Declined?
A decline in sales alone does not mean that every taxpayer subject to a preliminary assessment can choose to file a preliminary return.
If neither the taxable supply value nor the VAT payable meets the statutory threshold, and there are no grounds for an early refund, the taxpayer does not meet the preliminary filing requirements based on poor business performance.
This system concerns switching from a preliminary assessment to a preliminary return, so it must be distinguished from the rules for corporations that are already required to file preliminary returns.
Taxpayers subject to October 2026 preliminary assessments include individual general VAT taxpayers and small corporations whose total taxable supply value in the previous tax period was less than KRW 150,000,000.
A preliminary assessment may not be issued when the assessed tax is less than KRW 500,000 or when other statutory grounds for exemption from preliminary assessment apply.
Therefore, the absence of a tax notice should not be interpreted as meaning that there are no tax filing or payment obligations at all.
What Should You Decide Before October 26?
Businesses that have received a October 2026 VAT preliminary tax notice should first compare the following three amounts.
Taxable supply value and VAT payable for 1–June of 2026
Taxable supply value and actual calculated VAT payable for 7–September of 2026
The October preliminary assessment amount issued by the National Tax Service
If the comparison shows that the statutory requirements are met, the taxpayer can reflect actual business performance by filing a preliminary return.
Conversely, if the preliminary filing requirements are not met, the taxpayer should prepare for the preliminary assessment payment deadline and the subsequent reconciliation through the final VAT return.
If Sales Have Declined, the Key Is to Calculate Whether You Meet the 1-in-3 Threshold Before Deciding to Pay the Amount Stated in the Notice
Before the 2026-10-26 preliminary filing deadline, it is advisable to review your assessment details and actual filing records in Hometax. If eligibility is unclear, consult the relevant tax office or a tax professional to confirm how the rules apply to your individual circumstances.
※ This article is provided for reference to help readers understand market trends and does not constitute an investment recommendation for any particular security or asset. Final investment decisions and responsibility rest with the individual.