

October 2026 VAT Advance Notice: Conditions for Canceling the Assessed Tax Amount When Sales Decline and the Filing Deadline
Even sole proprietors who have received a October 2026 VAT advance payment notice may be able to cancel the assessed tax amount by filing a preliminary VAT return if their sales or tax payable have fallen significantly below a specified threshold. However, a slight decline in sales does not automatically cancel the assessment. They must check the threshold of less than 1/3 of the previous taxable period's amount and the October 26 preliminary filing deadline.
In its 2026-10-05 announcement, the National Tax Service (NTS) explained the preliminary VAT filing system to business owners facing increased tax burdens due to poor business performance.
This time, it is important to distinguish between the two dates because the preliminary VAT filing and payment deadline differs from the advance notice payment deadline.
How Much Must Sales Decline to Cancel an Advance VAT Assessment?
Businesses may qualify to file a preliminary VAT return if their taxable sales value or tax payable during the 2026 2th preliminary filing period, from July 1 to September 30, is less than 1/3 of the corresponding amount for the previous taxable period.
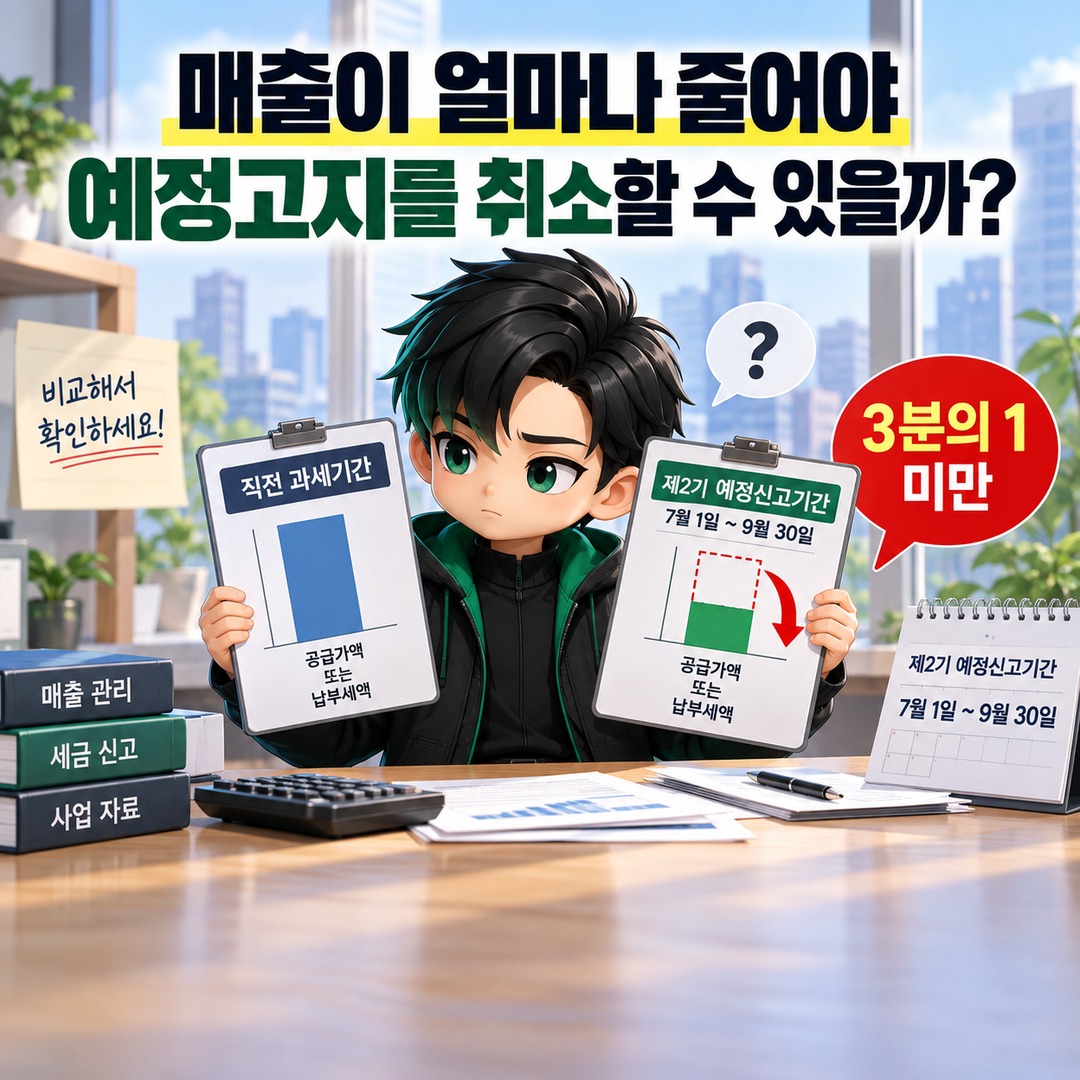
Article 90 of the Enforcement Decree of the Value-Added Tax Act grants this filing option to businesses whose performance has deteriorated due to temporary closure, poor business conditions, or similar circumstances.
The important point is not simply the percentage decline in sales, but the basis used for comparison.
For the October 2026 preliminary VAT filing, the periods compared are as follows.
| Category | Comparison Period |
|---|---|
| Previous taxable period | 2026-01-01~June 30 |
| Current preliminary filing period | 2026-07-01~September 30 |
| Eligibility threshold for filing | Taxable sales value or tax payable is less than 1/3 of the previous taxable period's amount |
Taxable sales value refers to sales revenue excluding VAT.
For example, if the taxable sales value for the first half of 2026 was KRW 90,000,000, the business would check whether its taxable sales value during the current preliminary filing period was below KRW 30,000,000.
7~September taxable sales value of KRW 25,000,000: Meets the threshold of less than 1/3.
7~September taxable sales value of KRW 30,000,000: Exactly 1/3, so it does not meet the below-threshold requirement.
7~September taxable sales value of KRW 40,000,000: Does not qualify based on taxable sales value.
These are hypothetical calculations intended to illustrate the conditions.
Even if a business does not meet the taxable sales value threshold, it can separately examine whether it meets the tax payable threshold.
Businesses that become eligible for an early VAT refund during the preliminary filing period may also choose to file a preliminary return.
What Happens to the Assessed Tax Amount After Filing a Preliminary VAT Return?
When a business files a preliminary VAT return after meeting the statutory requirements, the existing advance assessment is treated as though it had never been issued.
This treatment is prescribed by Article 48, Paragraph 4 of the Value-Added Tax Act.
Therefore, instead of paying the amount shown on the advance payment notice, the business pays based on the tax calculated in its preliminary return, reflecting actual sales and purchases during 7~September.
For example, if a business with an advance VAT assessment of KRW 2,000,000 legally files a preliminary return reporting tax payable of KRW 700,000, the original assessed amount of KRW 2,000,000 and the actual declared tax of KRW 700,000 are treated separately.
The difference of KRW 1,300,000 in this example is a hypothetical calculation and does not mean that every business will experience the same tax reduction.
Even when sales decline, the actual tax payable may vary depending on input VAT and eligibility for deductions.
The important point is that canceling an advance VAT assessment does not eliminate the underlying obligation to pay VAT.
A preliminary return calculates the tax for the actual reporting period, so tax may still be payable depending on the filing results.
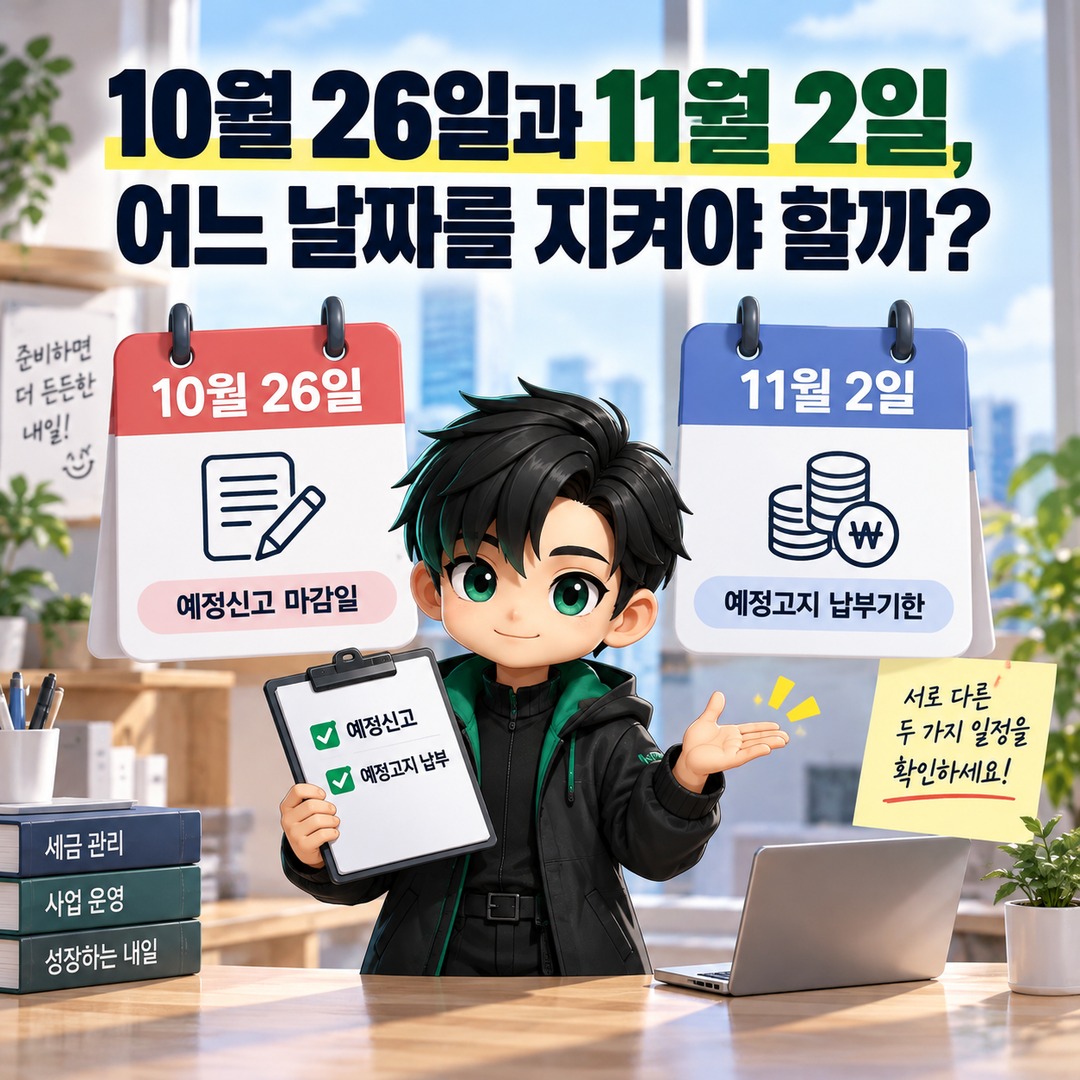
October 26 or November 2: Which Deadline Must You Meet?
For October 2026 VAT obligations, the preliminary filing deadline must be distinguished from the deadline for paying an advance assessment.
The schedule announced by the National Tax Service in October 5 is as follows.
| Category | 2026 Deadline |
|---|---|
| 2th preliminary VAT filing and payment | October 26, Monday |
| Payment of advance-assessed VAT | November 2, Monday |
Businesses choosing to file a preliminary return because of poor business performance must prepare according to the October 26 deadline.
The November 2 date printed on an advance payment notice is the deadline for paying the assessed amount. It does not mean that the preliminary filing deadline for businesses experiencing poor performance has been extended to November 2.
Therefore, businesses that wait until November 2 to prepare a preliminary return because the advance assessment is financially burdensome may miss the filing deadline.
What Should You Check and File Through Hometax?
Businesses considering a preliminary VAT return should first distinguish between the existing assessed amount and their actual business performance.
First, check the VAT advance assessment details on Hometax. After confirming the assessed amount and business information, determine whether the business qualifies for the current preliminary filing.
Second, compare the taxable sales value for the first half of 2026 with the taxable sales value for 7~September. If taxable sales value alone is insufficient to determine eligibility, compare the tax payable for each period as well.
Third, organize sales and purchase records for 7~September. This involves reviewing electronic tax invoices, credit card sales, cash receipts, and other sales- and purchase-related records.
Fourth, if the business meets the preliminary filing requirements, prepare and submit the return through the VAT preliminary filing procedure on Hometax.
After completing the filing, verify the submission result and the amount of tax payable.
In particular, do not assume that the assessed amount has automatically disappeared simply because sales have declined. It is important to confirm that a preliminary return meeting the statutory requirements has been filed.
What If Sales Have Not Fallen Below 1/3?
If neither taxable sales value nor tax payable meets the statutory threshold and there is no qualifying reason for an early refund, a business cannot choose to file a preliminary return merely because its sales have declined.
Advance VAT assessments are calculated based on the tax paid during the previous taxable period, so the assessed amount may differ from the business's current performance.
Under Article 48 of the Value-Added Tax Act, the advance-assessed VAT amount is generally calculated based on 50% of the tax paid during the previous taxable period.
However, the actual treatment may differ depending on whether the business is subject to advance assessment and whether any grounds for exclusion apply.
If sales have declined but the business does not qualify for preliminary filing, it should review its existing advance assessment and determine whether it qualifies for a separate payment deadline extension or deferment of tax collection.
The National Tax Service has also announced payment deadline extensions for certain affected businesses in connection with the October 2026 filing period. However, this payment relief and preliminary filing due to poor business performance are separate systems.
Can You File a Preliminary VAT Return After Already Receiving an Advance Payment Notice?
Receiving an advance payment notice does not, by itself, prevent a business from filing a preliminary VAT return.
When a business meeting the statutory requirements files a preliminary return, the existing advance assessment is treated as though it had never been issued.
However, actual business performance and the filing deadline are more important than whether the advance payment notice has been received.
If you are considering filing a preliminary return as of 2026-10-09, it is advisable to first check whether the taxable sales value or tax payable for 7~September is less than 1/3 of the corresponding amount for the previous taxable period.
If the threshold is met, you can prepare a preliminary return reflecting actual sales and purchases by October 26. If your tax classification or filing eligibility is unclear, it is safer to confirm the details with your local tax office or the National Tax Consultation Center.
※ This article is provided for reference to help readers understand market trends and does not constitute an investment recommendation concerning any particular stock or asset. Final investment decisions and responsibility rest with the individual.