

Voluntary National Pension Enrollment for Housewives Without Income and People in Their 50s: Monthly Contributions Start at KRW 96,230 in 2026
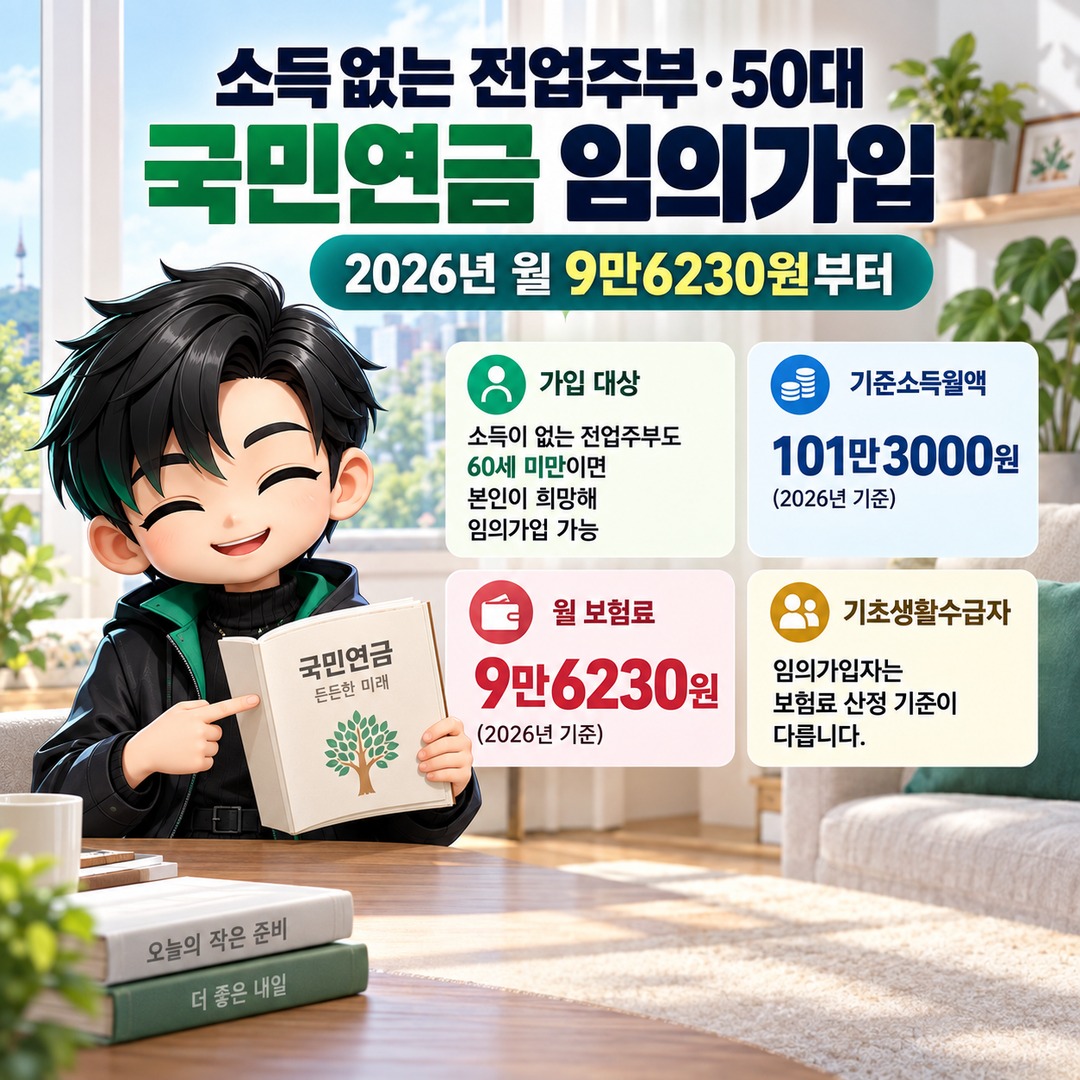
Homemakers without income who are exempt from mandatory National Pension enrollment can still enroll voluntarily if they are under age 60. As of October 2026, the standard monthly income base for ordinary voluntary participants is KRW 1,013,000, and the monthly contribution is KRW 96,230. However, different contribution calculation rules apply to voluntary participants receiving National Basic Livelihood Security benefits.
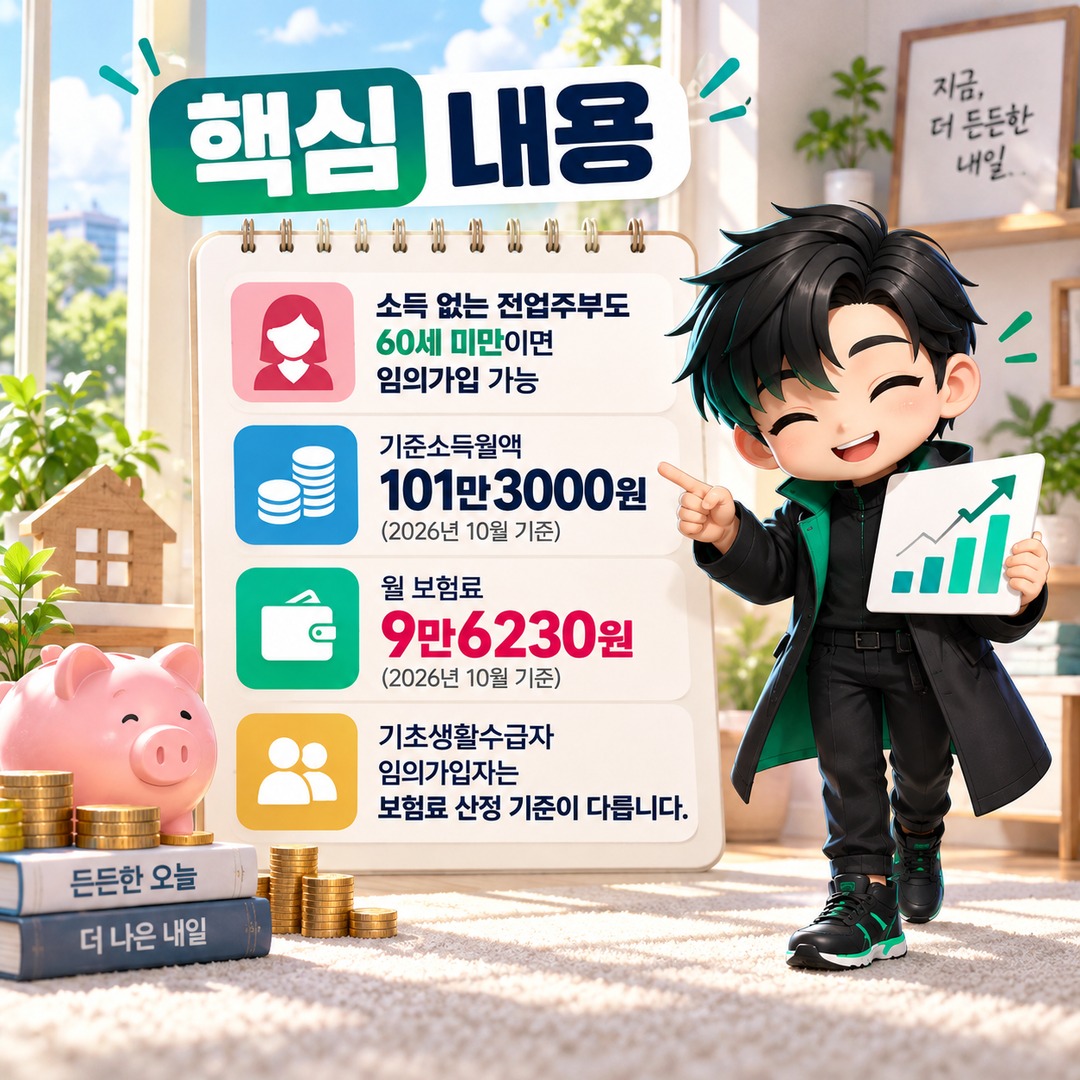
Why Is the Contribution KRW 96,230 in 2026?
Voluntary participants without actual income are not automatically assessed using KRW 410,000, the minimum standard monthly income base applicable to National Pension participants overall.
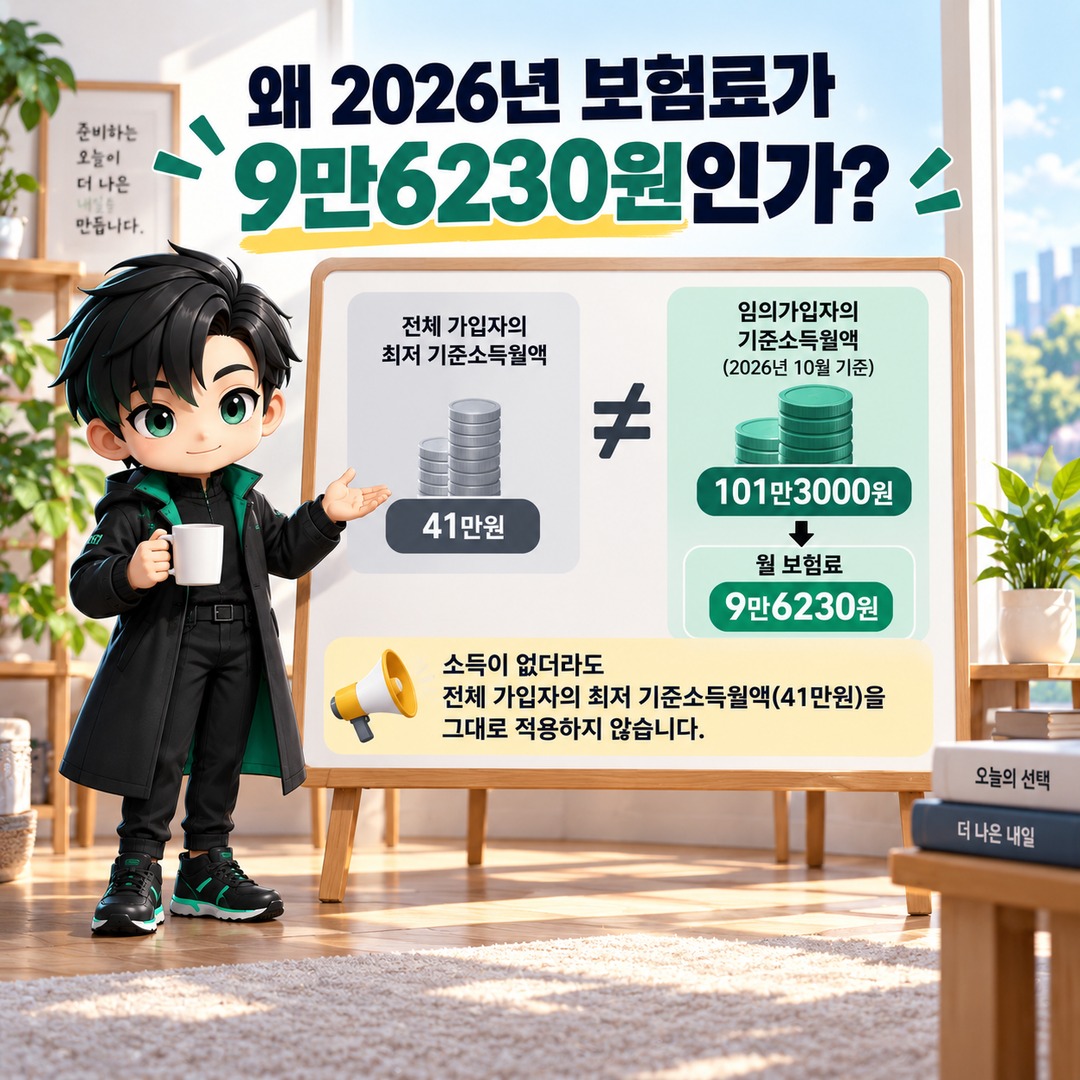
The standard monthly income base for ordinary voluntary participants is determined using the median income base of individually insured participants. The median standard monthly income base applicable from 2026-04-01 through 2027-03-31 is KRW 1,013,000.
The National Pension contribution rate for 2026 is 9.5%. The 2026 contribution table published by South Korea's National Pension Service (NPS) also confirms that the pension contribution corresponding to a standard monthly income base of KRW 1,013,000 is KRW 96,230 per month.
The calculation is as follows:
KRW 1,013,000 × 9.5% = KRW 96,235
Under National Pension contribution calculation rules, amounts below KRW 10 are discarded, resulting in an actual monthly contribution of KRW 96,230.
Therefore, as of October 2026, an ordinary homemaker without income who is considering voluntary enrollment should use KRW 96,230 per month as the starting contribution amount.
How Much Has It Increased Compared With KRW 90,000 in 2025?
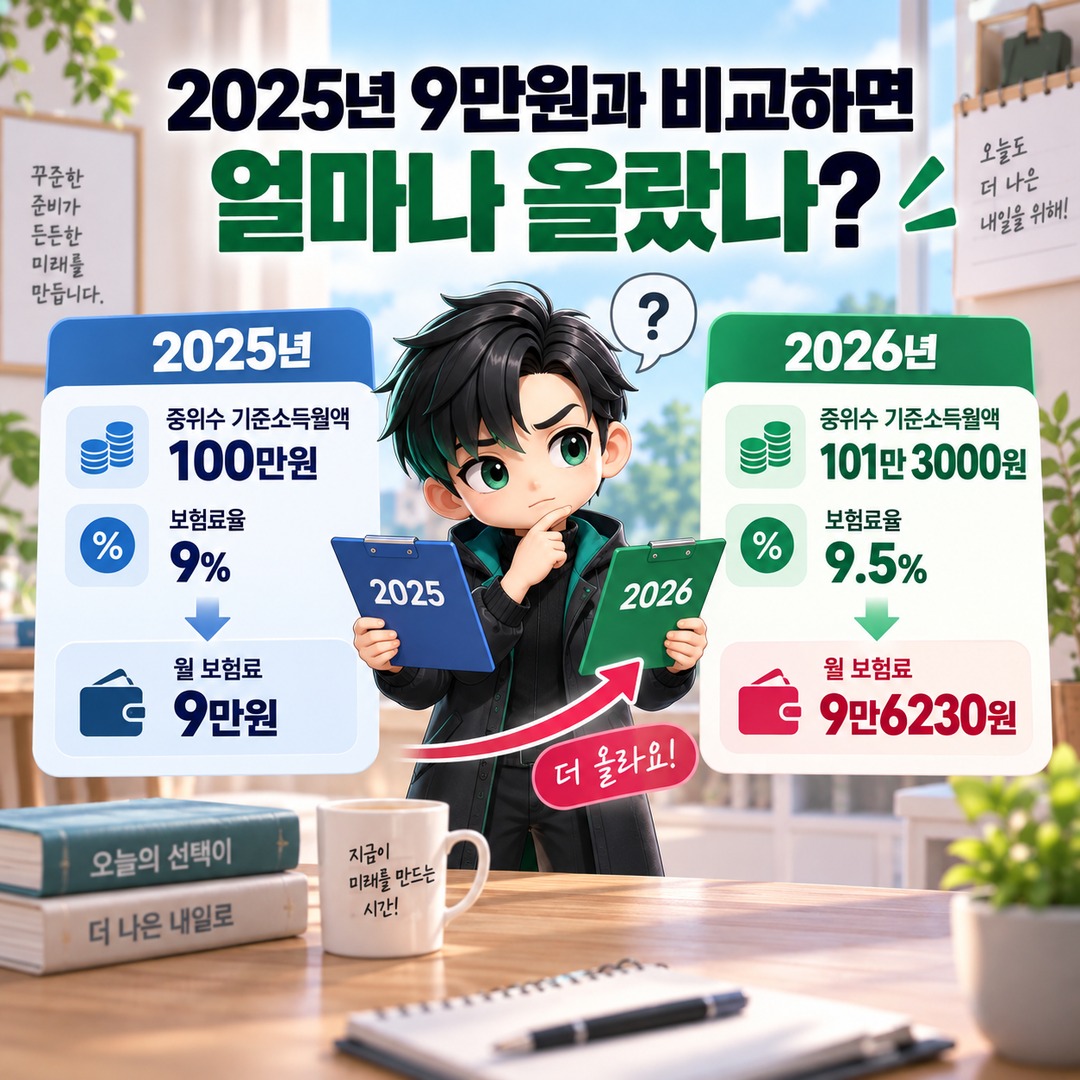
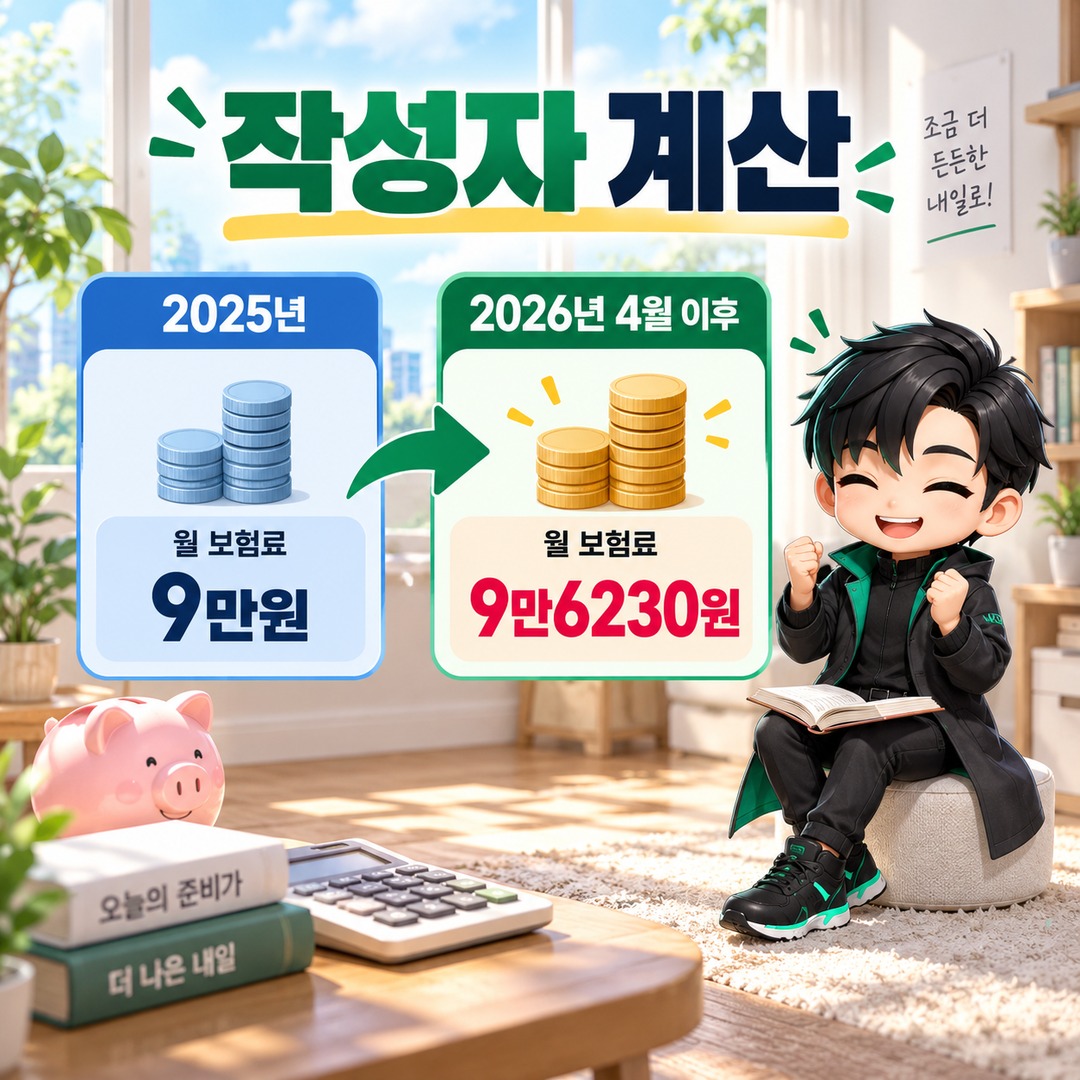
In 2025, the median standard monthly income base for voluntary participants was KRW 1,000,000, and the contribution rate was 9%. The resulting monthly contribution was KRW 90,000. In 2026, the contribution rate increased to 9.5%, while the median standard monthly income base for voluntary participants changed to KRW 1,013,000 beginning April.
Author's Calculation
2025: KRW 90,000 per month → From April 2026: KRW 96,230 per month
Monthly difference: KRW 6,230
If contributions were paid at these fixed monthly amounts for 1 years, a simple calculation shows a difference of KRW 74,760 compared with the monthly contribution in 2025.
However, in 2026, the contribution rate and the median standard monthly income base for voluntary participants changed at different times. The 2026 contribution rate of 9.5% took effect on January, while the KRW 1,013,000 income-base standard for voluntary participants took effect on April 1. Therefore, it would be inaccurate to compare the entire year using a single monthly contribution amount.
Do Homemakers in Their 50s Pay the Same Amount?
Being in your 50s does not, by itself, make National Pension contributions more expensive. For ordinary homemakers under age 60 who qualify for voluntary enrollment, age itself does not determine the monthly contribution.
Voluntary enrollment in South Korea's National Pension is available to people aged 18 or older but under 60 who cannot enroll as workplace-insured or individually insured participants and wish to participate voluntarily. People without separate income who are spouses of National Pension participants or members or beneficiaries of other public pension systems may also qualify.
Therefore, being 51, 55, or 58 years old does not mean that a different minimum contribution applies to each age.
The important factors are current enrollment eligibility and whether the person has income, rather than age alone.
Can You Pay Just KRW 38,950 per Month, Calculated as 9.5% of KRW 410,000?
When calculating voluntary National Pension contributions for an ordinary homemaker without income, using KRW 410,000 as the income base and applying a monthly contribution of KRW 38,950 would be incorrect.
KRW 410,000 is the overall minimum standard monthly income base for the National Pension, applicable from July 2026 through June 2027. By contrast, ordinary voluntary participants generally use the median standard monthly income base of individually insured participants, which is KRW 1,013,000 beginning April 2026.
The National Pension Service's 2026 materials also distinguish between these two amounts.
The monthly contribution for a standard monthly income base of KRW 410,000 is KRW 38,950, whereas the monthly contribution for a standard monthly income base of KRW 1,013,000 is KRW 96,230.
However, voluntary participants receiving National Basic Livelihood Security benefits are an exception. When a recipient of these benefits without income enrolls voluntarily, the minimum standard monthly income base may apply. Their contributions therefore should not be calculated in the same way as those of ordinary homemakers.
Can You Contribute More Than KRW 96,230?
Yes. Ordinary voluntary participants generally use the median standard monthly income base, but they may declare a higher standard monthly income base, and that higher declared amount can be accepted.
For example, the National Pension Service's 2026 contribution table shows how monthly contributions vary according to the standard monthly income base:
KRW 1,013,000 → KRW 96,230 per month
KRW 1,100,000 → KRW 104,500 per month
KRW 1,200,000 → KRW 114,000 per month
KRW 1,500,000 → KRW 142,500 per month
KRW 2,000,000 → KRW 190,000 per month
Beginning July 2026, the upper limit of the standard monthly income base is KRW 6,590,000. Applying the contribution rate of 9.5% results in a maximum monthly contribution of KRW 626,050.
Paying higher contributions means the standard monthly income base on which those contributions were paid will also be reflected in future pension calculations. However, the actual old-age pension benefit depends on factors including the contribution period, income during different enrollment periods, and the calculation rules applicable when pension payments begin. Future pension benefits cannot be determined solely from the current contribution amount.
People in Their 50s Should Also Check Their Contribution History
If you are considering voluntary National Pension enrollment for the first time in your 50s, it is advisable to check not only the monthly contribution of KRW 96,230 but also how many months of National Pension contributions you have already paid.
Voluntary enrollment is available until you reach age 60. After reaching 60, you are no longer eligible for ordinary voluntary enrollment. However, a separate voluntary continued enrollment program allows eligible individuals to apply before reaching age 65, subject to certain conditions.
Therefore, people in their 50s should consider both their current age and previous contribution history when deciding whether to enroll.
For example, if you previously paid National Pension contributions while employed, you should consider those contribution periods together with the additional periods you expect to contribute in the future. If you are in your late 50s and have relatively little time remaining before reaching age 60, it is also worth checking whether voluntary continued enrollment may be available.
How Do You Apply?
You can apply for voluntary National Pension enrollment through the National Pension Service website, its mobile app 'National Pension by My Side' (내 곁에 국민연금), an in-person visit, postal mail, fax, or a telephone call that allows identity verification.
Because voluntary enrollment is not mandatory, participants may withdraw if they wish. However, failure to pay contributions for 6 consecutive months or longer may result in administrative termination of enrollment.
To summarize as of October 2026, monthly voluntary National Pension contributions for ordinary homemakers without income and people in their 50s start at KRW 96,230. It is important not to confuse this with KRW 38,950, which is calculated using KRW 410,000 as the standard monthly income base.
However, the applicable enrollment category and contribution calculation rules may differ if you receive National Basic Livelihood Security benefits, currently qualify for workplace or individual enrollment, or have reached age 60. You should therefore verify your eligibility and contribution requirements against your personal enrollment history.