

Turtle Trading 2N Stop-Loss Calculation: What Are the Stop Price and Position Size When Entering Bitcoin at KRW 100,000,000?
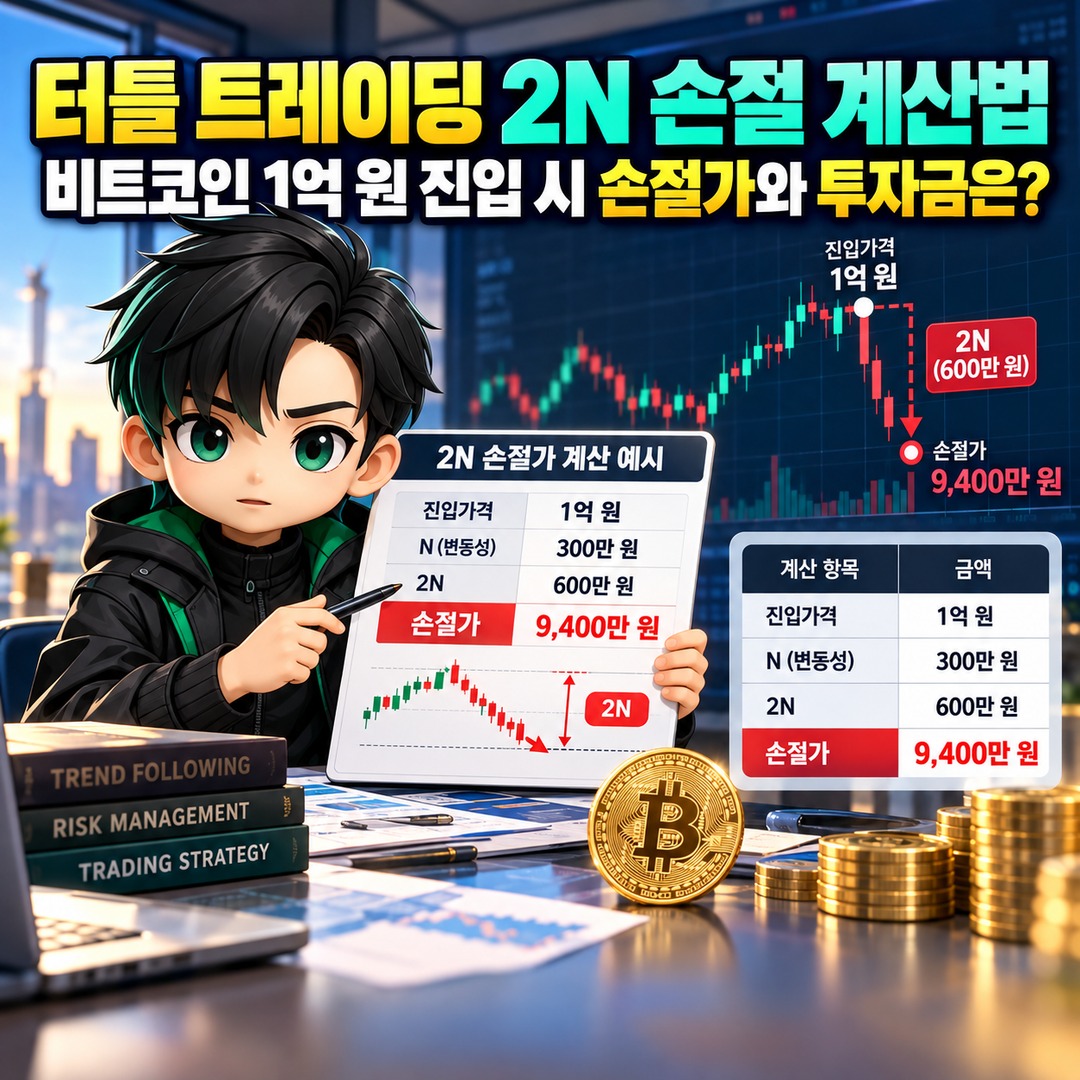
In Turtle Trading, the stop-loss price is calculated by subtracting 2 times N, a volatility measure, from the entry price. If Bitcoin is purchased at KRW 100,000,000 and N is KRW 3,000,000, the stop-loss reference price is KRW 94,000,000. However, setting a stop-loss price and limiting the actual amount lost are two separate matters.
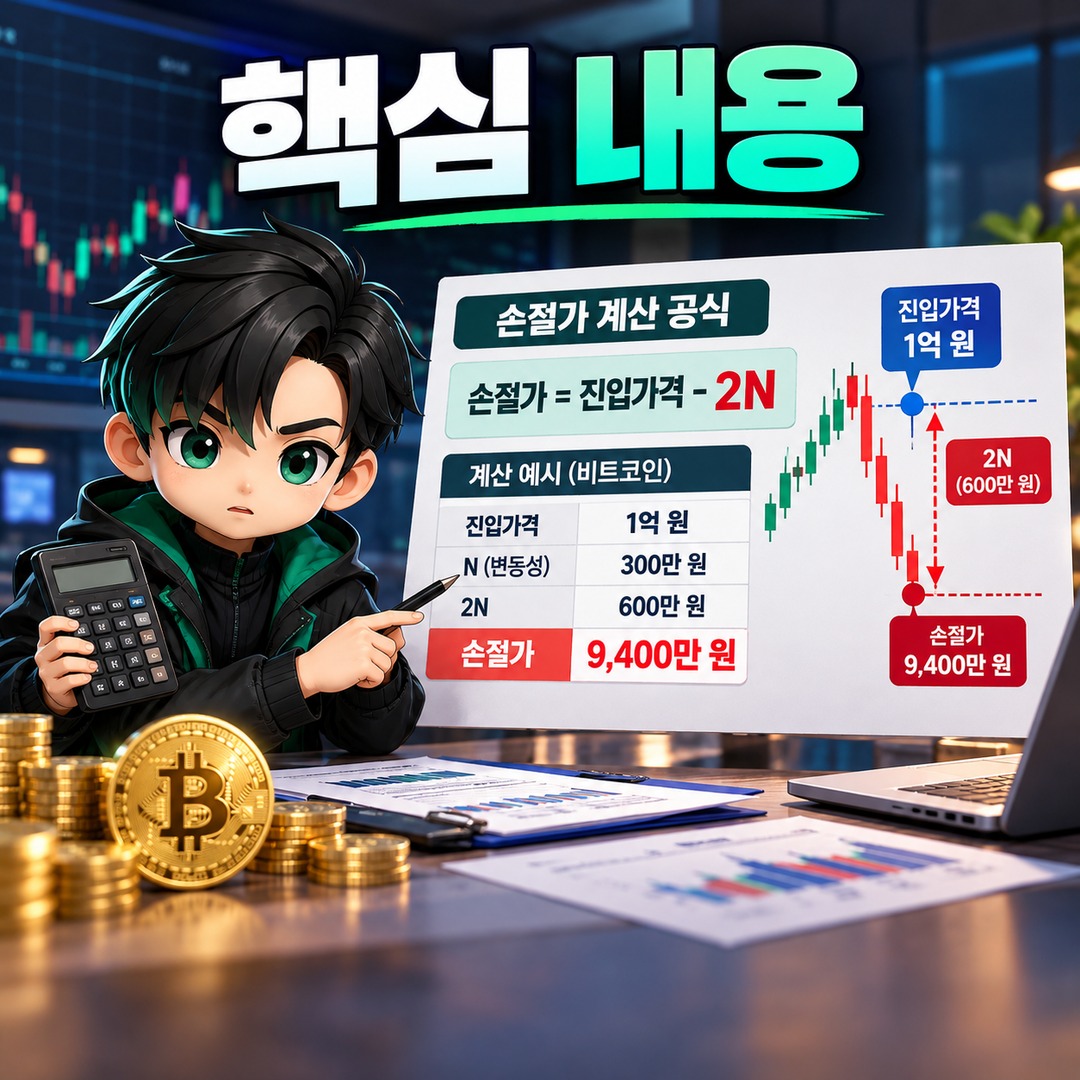
As of 2026-10-21, the most important consideration when applying the publicly documented Turtle Trading principles to Bitcoin spot trading is calculating both the 2N stop-loss distance and the quantity to purchase.
1. What Is N in Turtle Trading, and Why Is It Multiplied by 2?
In Turtle Trading, N is a measure of daily market volatility. It is similar to the commonly used Average True Range (ATR), and the original Turtle system incorporated price fluctuations over the most recent 20 trading days.
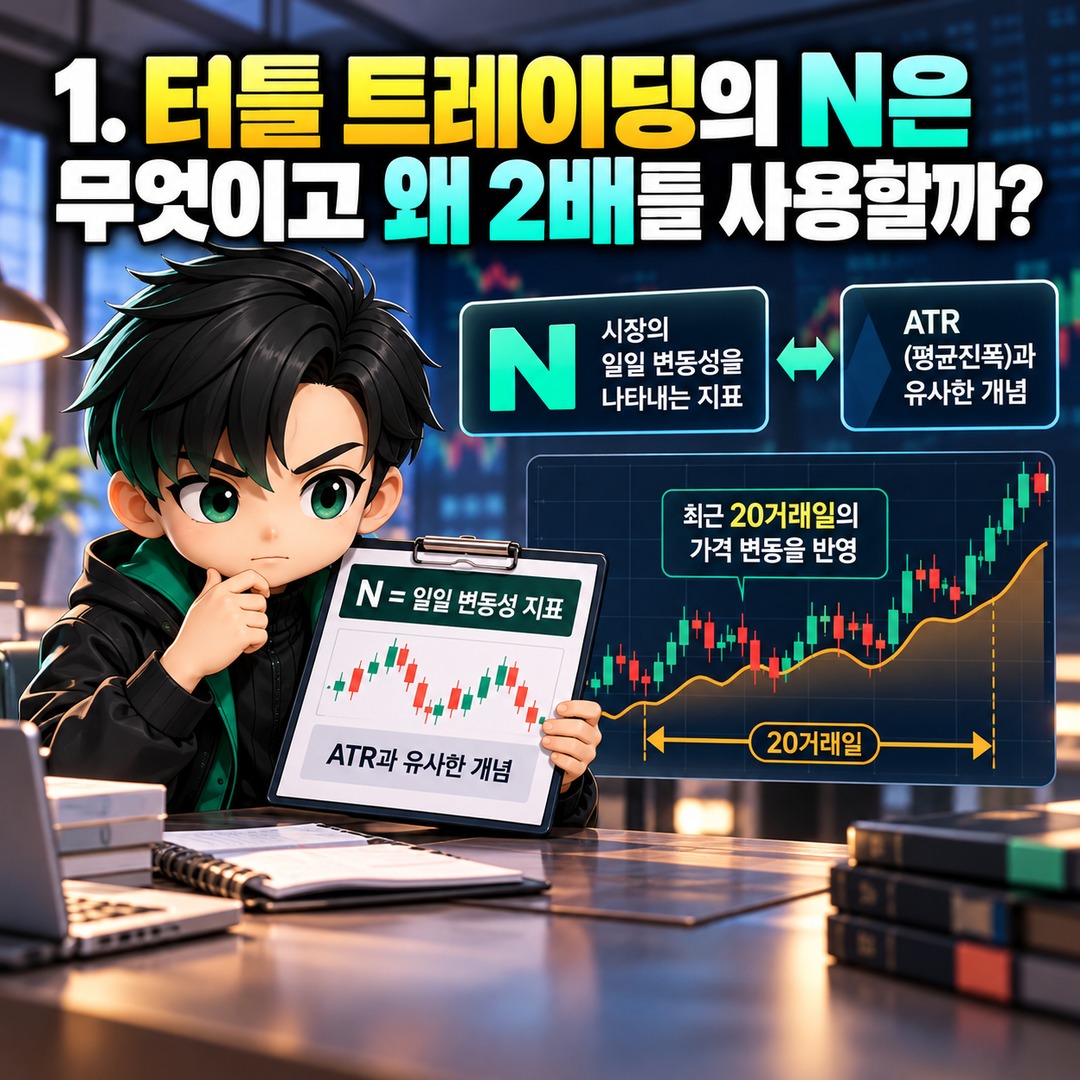
Under the original rules, N is calculated as follows.
Today's N = (Previous day's N × 19 + Today's TR) ÷ 20
Here, TR (True Range) is the largest of the following three values:
Today's high − Today's low
|Today's high − Previous day's close|
|Today's low − Previous day's close|
The initial N is calculated using the simple average of TR over 20 periods.
The Turtle system used 2N as its stop-loss reference to account for normal market fluctuations. When volatility increases, the stop-loss distance widens. When volatility decreases, the distance narrows.
However, 2N is not a magic number that prevents losses. In sideways markets where no clear trend develops, stop-loss orders may be triggered repeatedly.
For reference, TradingView's default ATR period is 14, while the original Turtle rules use N calculated over 20 periods. Even on the same chart, different settings can produce different stop-loss levels.
2. What Is the 2N Stop-Loss Price When Entering Bitcoin at KRW 100,000,000?
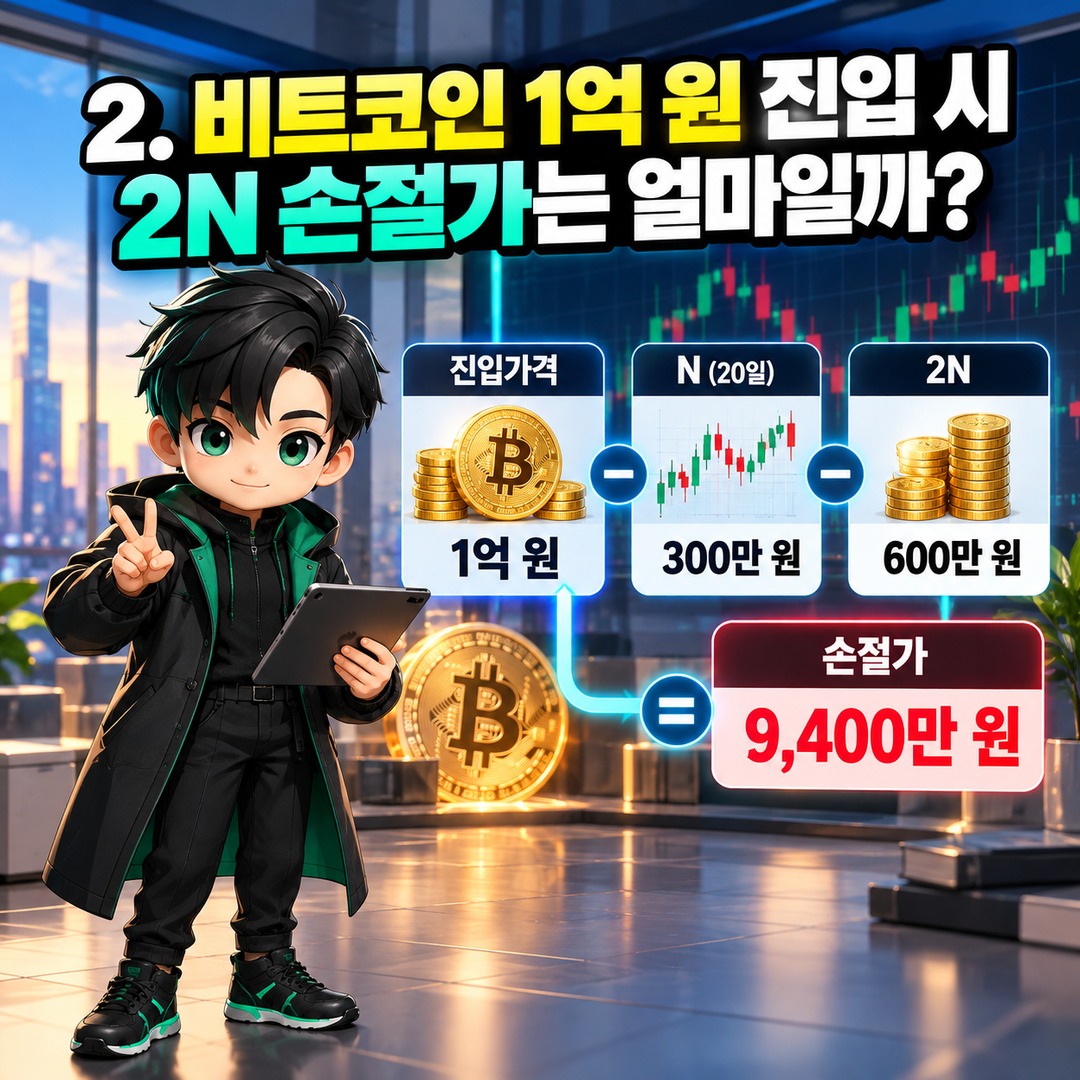
Assume that Bitcoin is priced at KRW 100,000,000 and its 20-day N is KRW 3,000,000. This is a hypothetical calculation, not an actual market quotation as of 2026-10-21.
The formula for a long position is:
Stop-loss reference price = Entry price − (2 × N)
The calculation produces the following results:
Entry price: KRW 100,000,000
N: KRW 3,000,000
2N: KRW 6,000,000
Stop-loss reference price: KRW 94,000,000
Stop-loss distance relative to entry price: 6%
Example of a Bitcoin 2N stop-loss calculation
For a short position, the calculation works in the opposite direction.
Short-position stop-loss reference price = Entry price + 2N
For example, if a short position is opened at KRW 100,000,000 and N is KRW 3,000,000, the stop-loss reference price is KRW 106,000,000.
The important point is that 2N is not a fixed percentage of the price. If N decreases to KRW 2,000,000, the stop-loss distance becomes 4%. If N increases to KRW 5,000,000, the stop-loss distance becomes 10%.
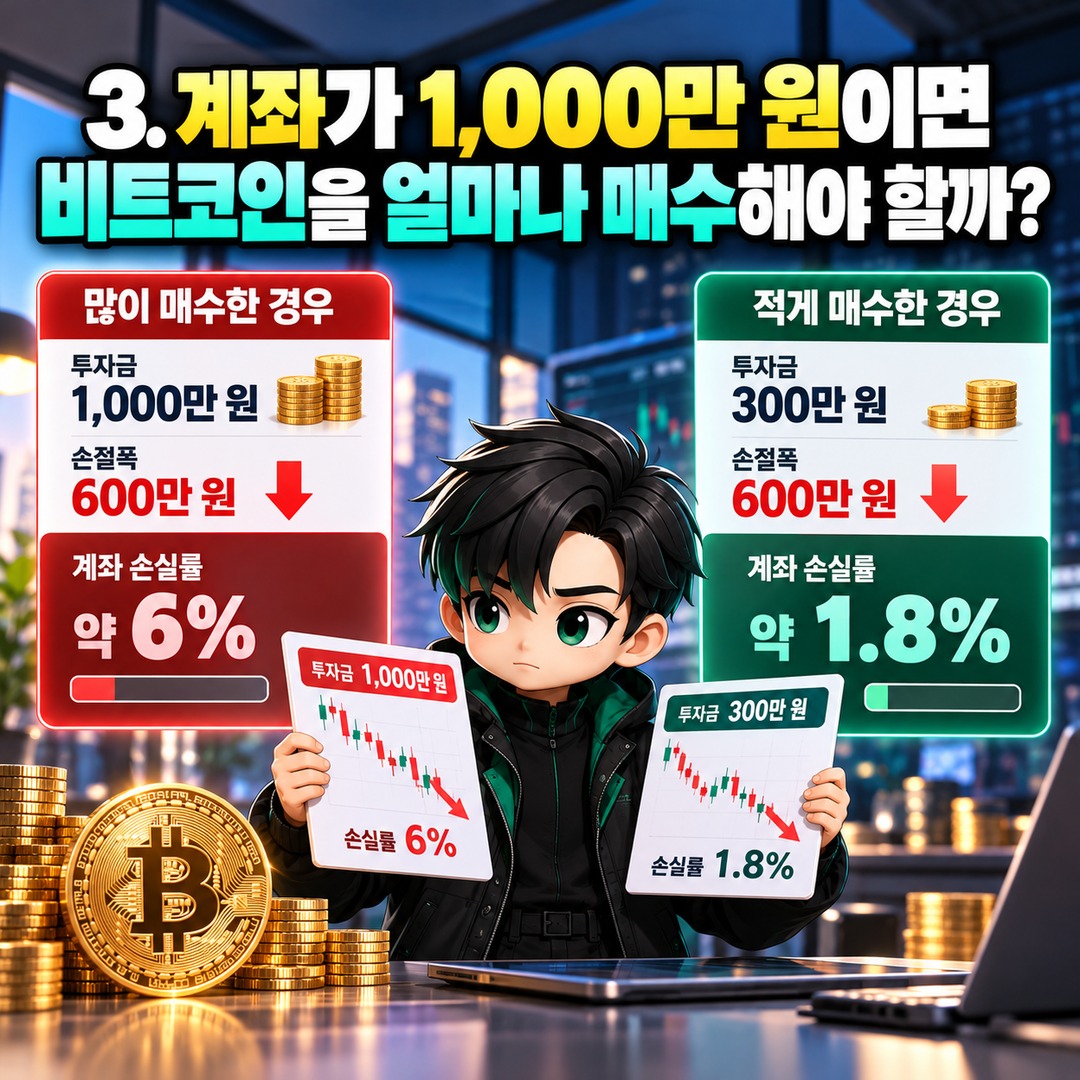
3. How Much Bitcoin Should You Buy With an Account Balance of KRW 10,000,000?
A stop-loss reference price of KRW 94,000,000 does not mean you must lose 6% of your entire account. By reducing the purchase quantity, you can design a position that produces a smaller account-level loss even with the same stop-loss distance.
The original Turtle system determined the size of one Unit so that a price movement of 1N would correspond to approximately 1% of account equity.
Therefore, under the original rules, stopping out one Unit at 2N produces an expected loss of approximately 2% of the account. This is a theoretical figure that excludes trading costs and slippage.
For comparison, we will also calculate a modified example that reduces the account loss limit to 1%.
Position Size Calculator for an Account of KRW 10,000,000
Assumptions: Entry price KRW 100,000,000 · N KRW 3,000,000 · Stop-loss distance KRW 6,000,000
Allowed account loss percentage 0.5% 1% 2% Target loss limit
KRW 100,000
Calculated purchase quantity
0.01667 BTC
Notional purchase amount: approximately KRW 1,666,667. Fees and slippage are excluded, and the actual executed quantity may vary depending on the exchange's order increments.
The formula is straightforward.
Purchase quantity (BTC) = Permitted account loss ÷ Stop-loss distance per 1 BTC
For an account of KRW 10,000,000, setting KRW 100,000, equivalent to 1%, as the risk limit gives the following calculation:
KRW 100,000 ÷ KRW 6,000,000 = approximately 0.01667 BTC
In other words, the calculation results in purchasing approximately KRW 1,667,000 worth of Bitcoin.
This is a modified example that uses approximately half the risk of one Unit under the original Turtle system. Actual losses may exceed KRW 100,000 depending on order execution conditions.
4. What to Watch for When Configuring ATR in TradingView
To view an N value similar to the original Turtle system in TradingView, change the ATR period to 20 and examine the daily chart.
Follow these steps:
1. Open a Bitcoin trading chart quoted in Korean won or US dollars.
2. Set the chart timeframe to 1 day.
3. Search for and add the ATR indicator.
4. Change the ATR period from its default value of 14 to 20.
5. Confirm that the displayed ATR value uses the same currency unit as the entry price.
In particular, distinguish between BTC/KRW charts, where ATR is denominated in Korean won, and BTC/USDT charts, where ATR is denominated in USDT.
TradingView uses Wilder's RMA method by default to calculate ATR. However, differences in initial calculation values and data providers may prevent its values from matching the original Turtle N exactly.
ATR is not an indicator that predicts price direction. Rather than showing whether prices are likely to rise, it indicates how large recent price fluctuations have been.
5. How Does a 2N Stop-Loss Differ From 10-Day and 20-Day Exits?
Turtle Trading has separate rules for stop-losses and trend exits.
A 2N stop-loss is a mechanism for controlling downside risk immediately after entering a position. In contrast, a breakout in the opposite direction over 10 days or 20 days is an exit rule for closing an existing trend-following position.
| Category | Original Turtle Rule | Purpose |
|---|---|---|
| Initial stop-loss | 2N against the position from the entry price | Control downside risk |
| System 1 exit | 10-day breakout in the opposite direction | Identify the end of a short-term trend |
| System 2 exit | 20-day breakout in the opposite direction | Identify the end of a long-term trend |
For example, assume Bitcoin is purchased at KRW 100,000,000 and the 2N stop-loss reference price is set at KRW 94,000,000.
If the price subsequently rises and the 10-day low moves up to KRW 105,000,000, the exit condition for System 1 may be triggered first.
Conversely, if the price drops sharply immediately after entry, the 2N stop-loss may be triggered before there is any need to wait for the 10-day low.
The original Turtle system did not automatically take profits at a fixed target return while a trend continued. Instead, it used exits based on breakouts in the opposite direction.
6. Situations Where a 2N Stop-Loss Can Fail in Cryptocurrency Markets
A 2N stop-loss provides a basis for calculating potential losses, but it cannot guarantee a strict limit on actual losses.
When an Order Executes Below the Stop-Loss Price During a Sharp Decline
Even if an order is configured to sell Bitcoin when the price reaches KRW 94,000,000, a rapid decline combined with insufficient liquidity may result in execution at a lower price.
This is known as slippage.
For example, if you hold 0.01667 BTC and the entire position is executed at KRW 93,000,000 instead of KRW 94,000,000, the loss resulting from the price difference is approximately KRW 116,690. That is approximately 16.7% more than the originally expected KRW 100,000.
When Stop-Losses Are Repeatedly Triggered in a Sideways Market
In a market where prices fluctuate within a defined range, false breakouts can occur when the price reverses shortly after breaking through a level.
Repeated 2N stop-losses under these conditions can produce substantial cumulative losses, even when each individual loss is controlled.
When Fees and Trading Costs Are Overlooked
Assume a hypothetical purchase amount of KRW 1,667,000 and a trading fee of 0.05% on both the buy and sell transactions. The total round-trip fee would be approximately KRW 1,617. This is the author's calculation, combining an estimated purchase fee of KRW 833 and an estimated selling fee of KRW 784 at the stop-loss reference price.
Actual fees vary by exchange, membership tier, and order type.
Futures trading also requires consideration of funding fees, leverage, and liquidation risk. In particular, if the liquidation price would be reached before the planned stop-loss price, the 2N stop-loss strategy may not function as intended.
7. What to Check Before Applying a 2N Stop-Loss to Real Trades
The essence of Turtle Trading goes beyond calculating a single stop-loss price.
Entry conditions, position sizing, stop-losses, additional entries, and trend exits must be connected within one consistent set of rules.
Before committing real capital, consider checking the following:
When calculating N over 20 periods, did you use daily candles and consistent price units?
Did you calculate the stop-loss price using N at the time of entry?
Did you set the loss limit to include trading fees and slippage?
Did you recalculate the risk of the entire position when adding to it?
Did you test the strategy against sufficient historical data, including sideways markets and sharp declines?
The original Turtle rules were designed primarily for futures markets. Applying them to cryptocurrency markets that trade 24 hours does not mean they will produce identical results.
Testing should account for actual exchange fees, order increments, and execution feasibility. Backtesting with historical data also does not guarantee future returns.
Conclusion: Determine Your Acceptable Loss Before Setting the Stop-Loss Price
If the Bitcoin entry price is KRW 100,000,000 and N is KRW 3,000,000, the 2N stop-loss reference price is KRW 94,000,000.
However, having KRW 10,000,000 in your account does not mean you must purchase KRW 10,000,000 worth of Bitcoin.
If you plan to limit your account loss to approximately 1%, the theoretical purchase quantity, excluding fees and other costs, is approximately 0.01667 BTC.
The 2N stop-loss in Turtle Trading is not a price prediction technique. It is a risk management rule that connects volatility with position size.
Just as important as calculating the stop-loss price is trading at a size you can afford to sustain even when the market moves against your expectations.
※ This article is provided for informational purposes to help readers understand market behavior. It is not an investment recommendation concerning any particular security or asset. All final investment decisions and responsibility rest with the individual investor.
Related Articles
Drawing Trendlines on Bitcoin Charts for Beginners: How to Start by Connecting 2 Lows and 2 Highs
Bitcoin Outlook: What Needs to Change for a Rebound Around USD 80,000?