

Why Doesn’t Turtle Trading Buy After a 20-Day Breakout? The Rule That Skips the Next Signal If the Previous Breakout Was Profitable
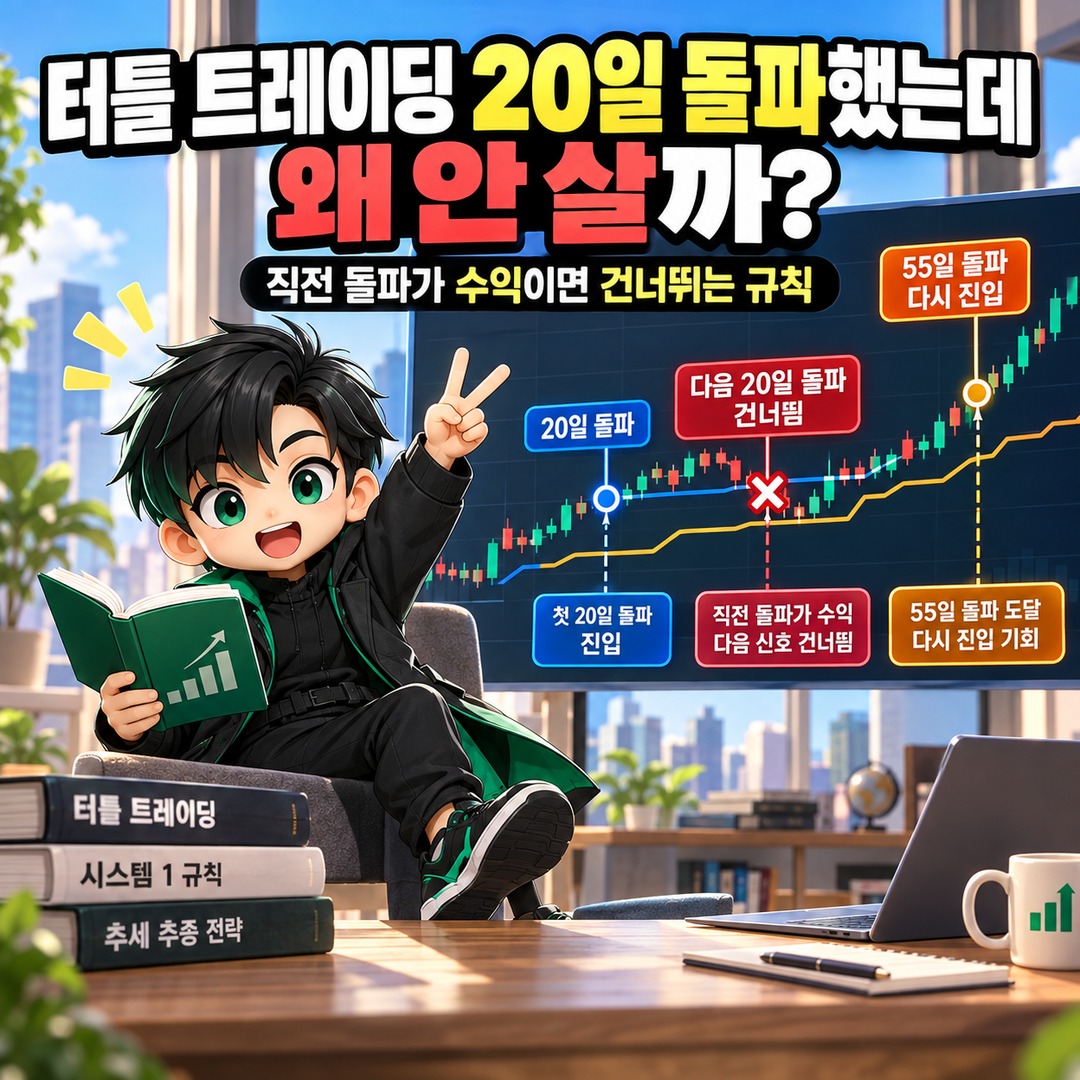
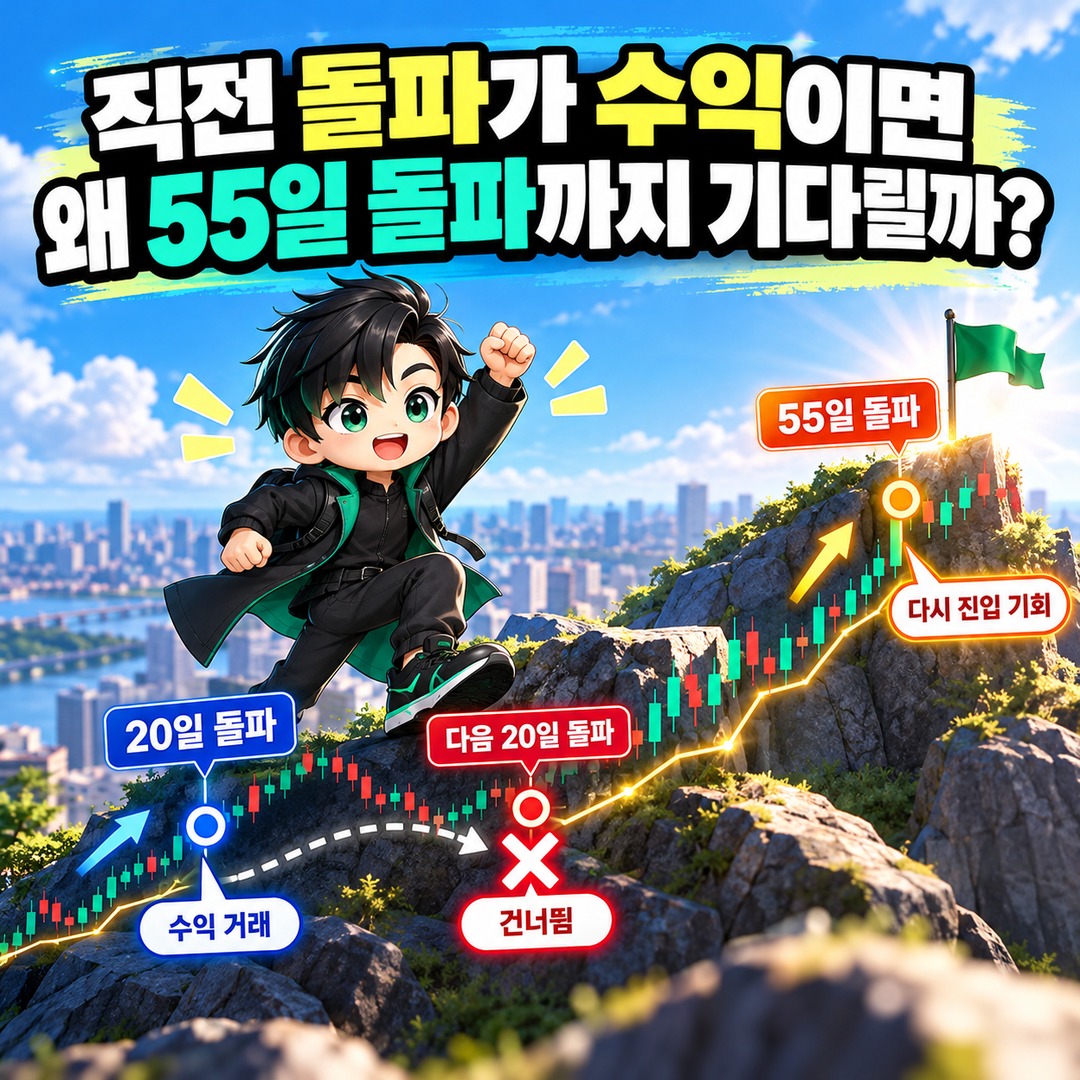
Turtle Trading System 1 does not automatically enter just because price breaks above the 20-day high. If the previous breakout was classified as profitable, the next 20-day breakout signal is skipped. Instead, if price continues moving and reaches a 55-day breakout, another entry opportunity appears under the ‘Failsafe Breakout’ rule.
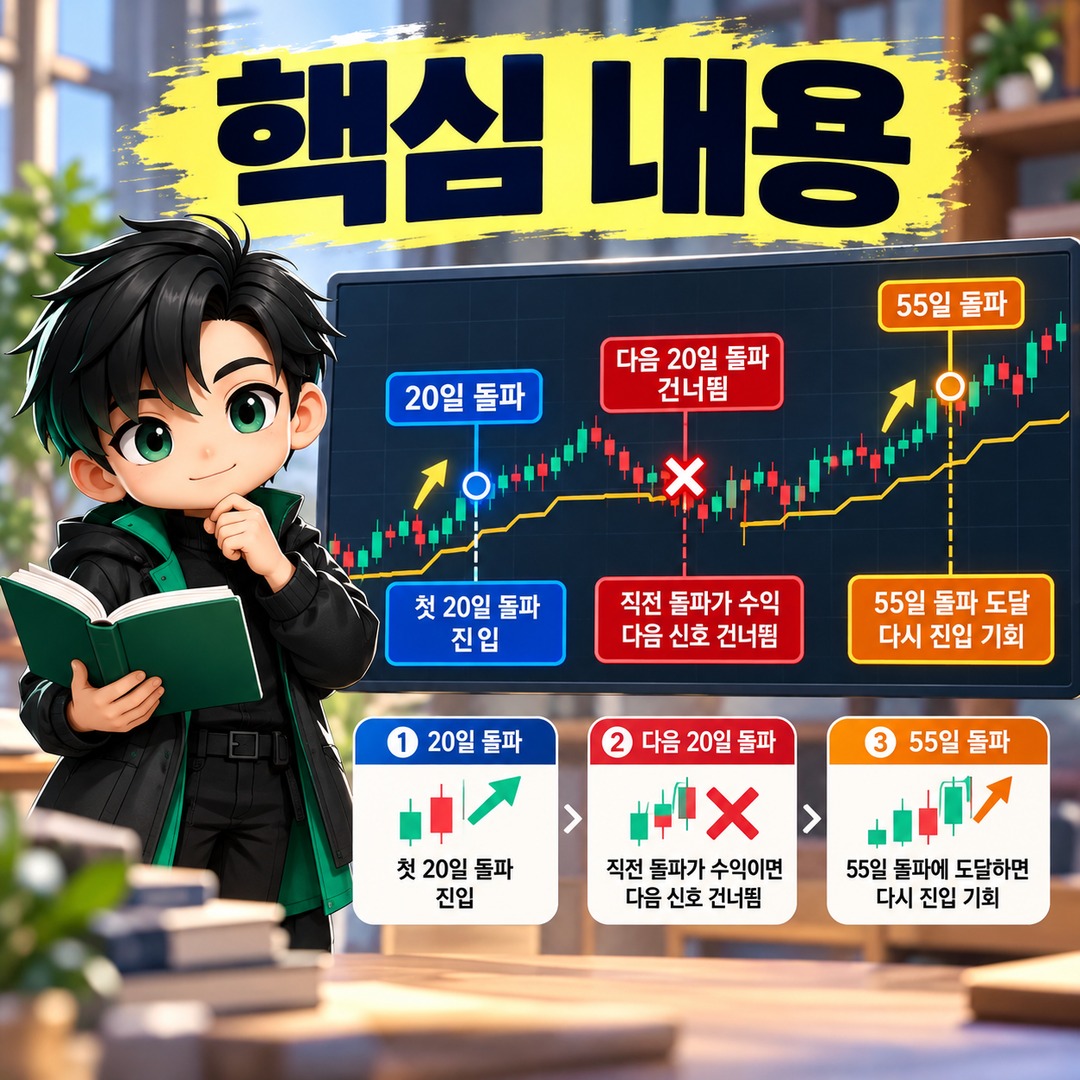
Therefore, viewing 20 days and 55 days simply as numbers for choosing between a faster entry and a slower entry differs from the original rules.
There Is One Condition Under Which a 20-Day Breakout Is Not Entered
In 『The Original Turtle Trading Rules』 released in 2003, System 1 specifies that if the previous 20-day breakout became a profitable trade, the next breakout signal should be ignored.
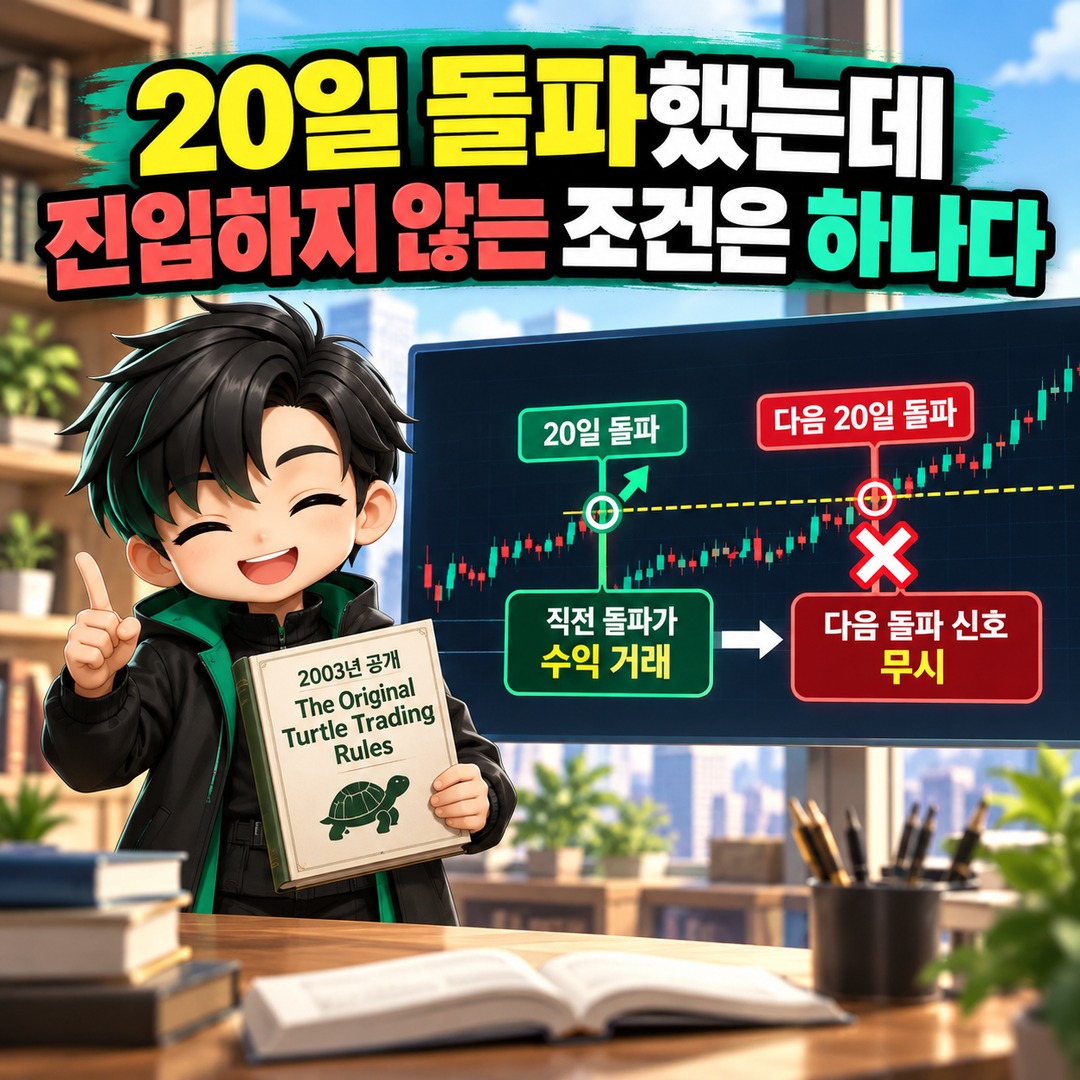
The basic flow is as follows.
| Result of Previous Breakout | Next 20-Day Breakout | Subsequent 55-Day Breakout |
|---|---|---|
| Classified as a loss | Entry allowed | Applied according to the system |
| Classified as profitable | Skipped | Failsafe entry |
| System 2 | No such filter | Enter on every 55-day breakout |
What matters here is that the system tracks the outcome of the previous breakout signal itself, not whether the previous trade was actually taken.
The original text explains that the result should be calculated regardless of whether the previous breakout in that market was actually traded or was skipped because of an earlier filter. Even the direction of the previous breakout does not matter. The result of the most recent signal, whether an upside breakout or a downside breakout, is evaluated.
How Is ‘The Previous Breakout Was Profitable’ Determined?
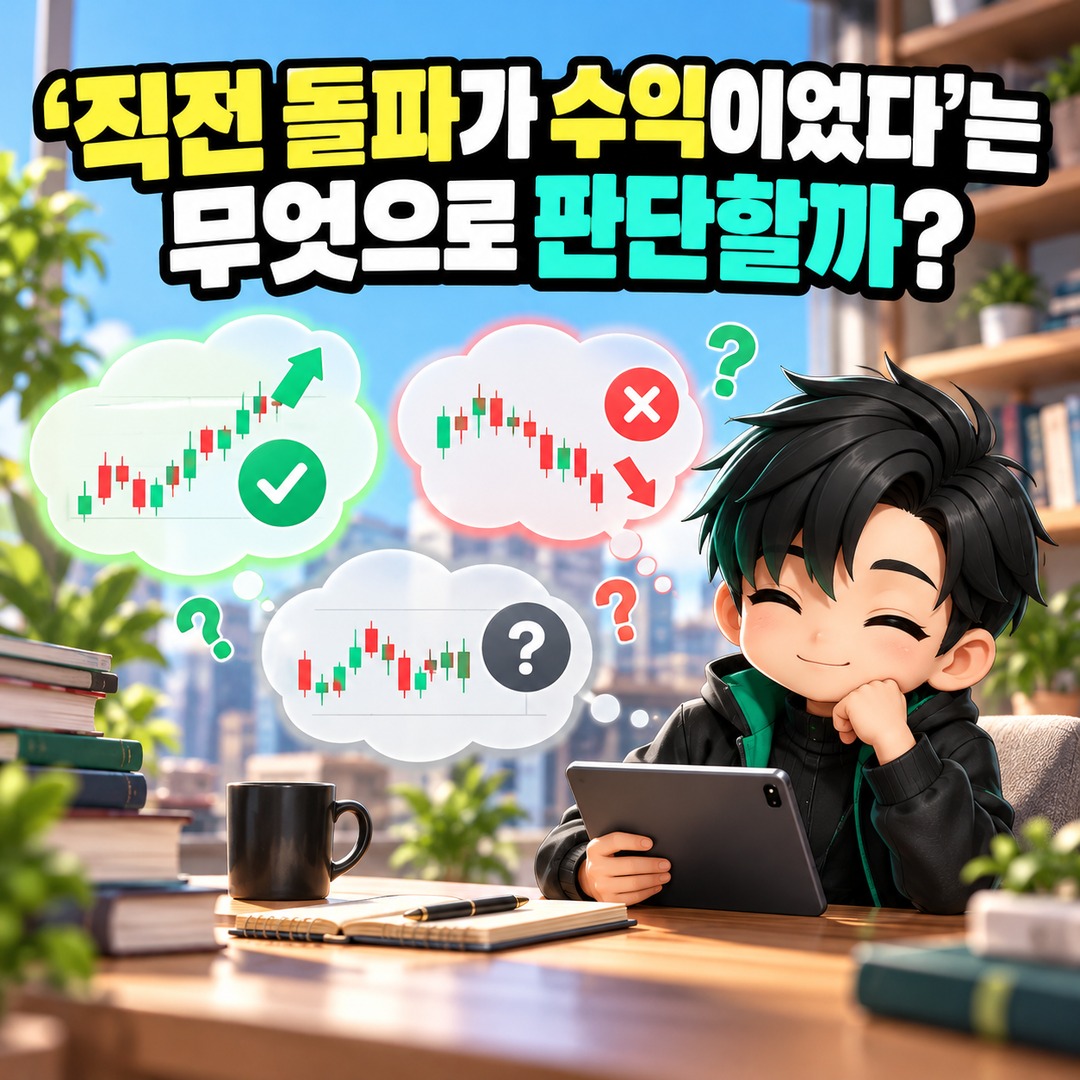
This is where a common misunderstanding arises.
It does not mean, “If I made money last time, I skip this 20-day breakout.”
The original Turtle rules determine whether the previous breakout was a winner or loser based on whether a profitable 10-day exit condition occurred after the previous breakout before price moved adversely by 2N. Conversely, if price moved adversely by 2N before a profitable 10-day exit occurred, it was treated as a losing breakout.
N is the unit used to represent volatility in the Turtle system. The published rules used the 20-day exponential average of True Range as N, a concept related to what is commonly called ATR today.
In other words, judging it simply by any of the following can differ from the original rules.
Whether you actually made money on the previous trade
Whether the closing price is above the entry price
Whether the stock price rose a few days later
Whether you arbitrarily took profits midway through the trade
The Turtle system uses the result obtained by continuously tracking the previous breakout under the same rules, not an individual trader’s actual trading outcome.
If the Previous Breakout Was Profitable, Why Wait Until a 55-Day Breakout?
In System 1, if the previous breakout was profitable, the next 20-day breakout is skipped. However, if price continues rising afterward and exceeds the 55-day high, the system no longer waits because of the 20-day filter.
The published original rules describe this 55-day level as the Failsafe Breakout point. It is a mechanism designed to prevent the system from filtering out a 20-day signal and then missing an entire major trend.
For example, suppose a hypothetical stock followed this sequence.
1. First 20-day high breakout occurs
2. That breakout is classified as profitable under the rules
3. A new 20-day high breakout later occurs
4. System 1 skips the second signal
5. The rise continues and a 55-day high breakout occurs
6. Entry is made under the Failsafe rule
Therefore, it is also incorrect to say, “Once the 20-day breakout is ignored, that instrument is never traded again.”
It is a structure that filters 20-day signals while still rejoining a strong continuing trend at a 55-day breakout.
The 55-Day Breakout in System 2 Works Differently
System 2 is simpler.
Without checking whether the previous breakout was profitable or losing, it takes every breakout signal that moves one tick beyond the highest high or lowest low of the previous 55 days. The published original rules explicitly state that System 2 takes every breakout regardless of whether the previous breakout was a winner or loser.
So if 20 days and 55 days are compared only at a surface level, the key difference is missed.
System 1
20-day breakout → Check previous breakout result → Skip signal if necessary → 55-day Failsafe exists
System 2
55-day breakout → Enter without filtering based on whether the previous breakout won or lost
The original Turtle participants could also allocate capital differently between System 1 and System 2. The published rules record examples of using only System 2, or allocating 50% each to System 1 and System 2.
Confirming Breakouts at the Close Differs From the Original Rules
This is especially important when implementing the Turtle strategy on stock charts.
Under the original rules, a breakout did not mean that the closing price finished above the 20-day or 55-day high.
According to the published original rules, the Turtles considered it a breakout the moment the intraday price moved one tick beyond the previous 20-day or 55-day high or low. If the market opened beyond the breakout price because of a gap, the entry was made at the opening price.
Therefore, the following two strategies cannot be assumed to produce the same results.
| Implementation Method | Entry Determination |
|---|---|
| Original Turtle rules | Intraday breakout of the previous N-day high or low |
| Closing-confirmation variation | Confirm that the close finishes beyond the breakout level |
A closing-confirmation version may be used as a variation in backtesting or an individual strategy, but its results should not be directly compared with the performance of the original Turtle rules.
Before Applying It Directly to Stocks, Costs and Market Differences Must Also Be Considered
The Turtle system taught by Richard Dennis and William Eckhardt was originally a system that diversified trading across multiple highly liquid U.S. futures markets. That trading environment is not the same as applying only 20-day and 55-day breakout lines to a single stock today.
At a minimum, actual testing should include the following elements.
First, trading costs and slippage. The breakout price and the actual execution price can differ. The difference can be even larger during gap-ups and gap-downs.
Second, position sizing. The original system did not buy the same quantity in every market. It used N to reduce position size in more volatile markets.
Third, stop-loss and exit rules. Taking only the entry rules does not create a complete Turtle system. In the original System 1, profitable positions were exited on an opposite-direction 10-day breakout, while System 2 used an opposite-direction 20-day breakout.
Fourth, repeated failed signals. The original Turtle rules themselves explain that most breakouts do not develop into trends. In trend following, the structure must be able to endure multiple small losses without missing the rare large trend.
What Should Ultimately Be Recorded on the Chart?
To test System 1 in a way that closely matches the original rules, displaying only the 20-day highest-high and lowest-low lines is not enough.
At a minimum, the following information should be recorded by date.
1. Previous 20-day high and low
2. Whether a 20-day breakout occurred
3. Hypothetical trade result of the previous breakout
4. Whether the previous breakout reached the 2N loss condition first
5. Whether a profitable 10-day exit condition occurred first
6. Whether the next 20-day signal was entered or skipped
7. Whether a 55-day Failsafe breakout occurred after the signal was skipped
8. Fees and slippage if actual execution is assumed
It is particularly important that breakouts that were not traded must also be recorded.
If tracking stops simply because the previous signal was skipped, the validity of the next signal cannot be determined correctly.
The Core of the Rule for Skipping a 20-Day Breakout
In Turtle Trading System 1, a 20-day breakout is not a standalone buy or sell signal.
The structure is: if the previous breakout was a loss, take the next 20-day breakout; if the previous breakout was profitable, skip the next 20-day breakout; and if a subsequent 55-day breakout occurs, enter again under the Failsafe rule.
System 2, by contrast, takes every 55-day breakout without this filter.
Therefore, if a Turtle strategy backtest implements only “buy on a 20-day high breakout,” it is testing a strategy different from the original System 1.
These rules are provided as material for understanding a historical trend-following system and are not a buy or sell signal for any specific stock, ETF, or futures contract. The original system itself was structured to tolerate losing trades and the giveback of large unrealized gains, and in today’s markets it should be tested separately while accounting for trading costs, taxes, liquidity, gaps, and product structure.
Reference Source Material
※ This article is for reference in understanding market behavior and is not an investment recommendation for any specific security or asset. Final decisions and investment responsibility rest with the individual investor.