

Switching from the Youth Leap Account to the Youth Future Savings Account Preserves Existing Government Contributions and Tax Benefits
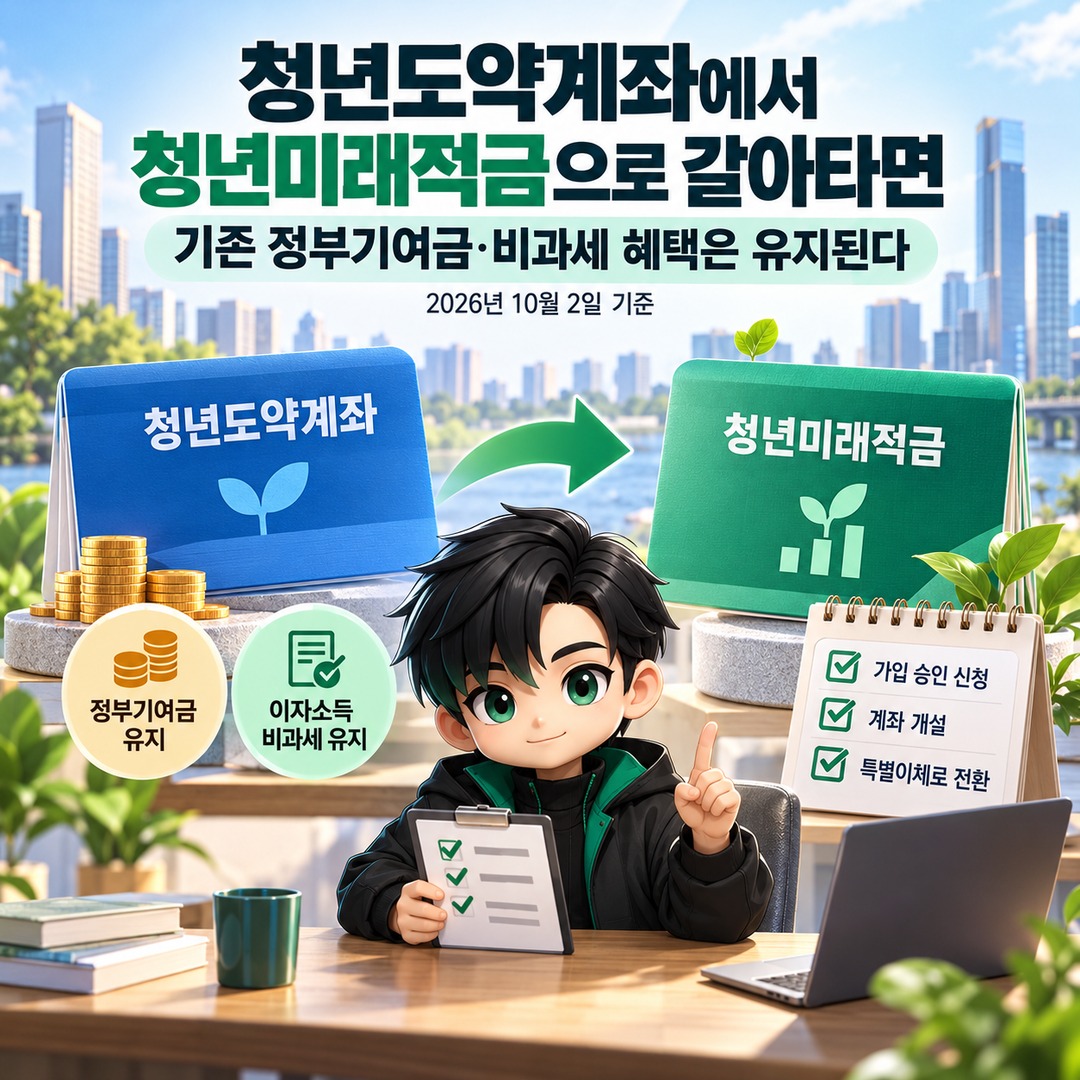
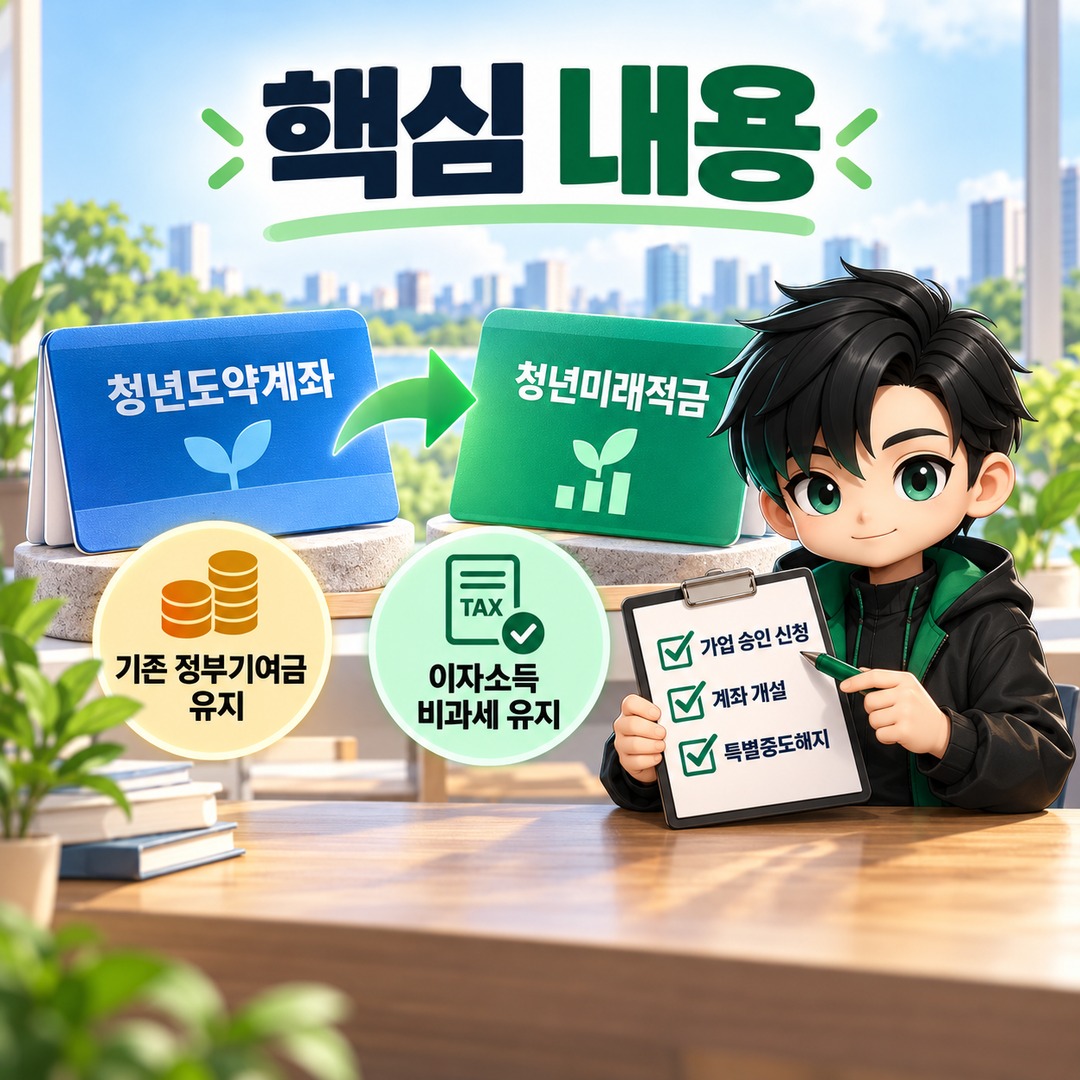
As of 2026-10-02, Youth Leap Account holders who switch to the Youth Future Savings Account through the prescribed transfer procedure retain the government contributions and income tax exemptions on interest earned on their existing Youth Leap Account deposits. However, they must not first close their Youth Leap Account through an ordinary early termination. Instead, they must receive approval to join the Youth Future Savings Account, open the new account, and then complete a 'special early termination for the purpose of joining the Youth Future Savings Account.'
Government Contributions Received Through the Youth Leap Account Will Not Disappear
When an account holder switches to the Youth Future Savings Account through the official procedure, the government contributions associated with deposits made into the existing Youth Leap Account are preserved. Financial authorities designed the switching arrangement for this 2th enrollment round to allow existing Youth Leap Account holders to change products while retaining their government contributions and tax benefits.
The important distinction is that switching accounts and ordinary early termination are not the same type of account closure.
Closing a Youth Leap Account to join the Youth Future Savings Account is handled through a separate special early termination procedure. Therefore, account holders should not assume that they can simply close their Youth Leap Account first and then open a new Youth Future Savings Account.
Tax Exemptions on the Existing Youth Leap Account Are Also Preserved
In addition to government contributions, the income tax exemption on interest earned from deposits made into the existing Youth Leap Account is also preserved.
The Financial Services Commission's guidance for the 2th enrollment round explicitly states that completing a special early termination for the purpose of joining the Youth Future Savings Account allows account holders to retain government contributions and income tax exemptions on interest associated with their existing Youth Leap Account deposits.
This means that switching accounts does not require participants to give up all the benefits they have accumulated through the Youth Leap Account.
However, this explanation applies only when the account holder successfully completes the government-designated linked enrollment procedure from the Youth Leap Account to the Youth Future Savings Account.
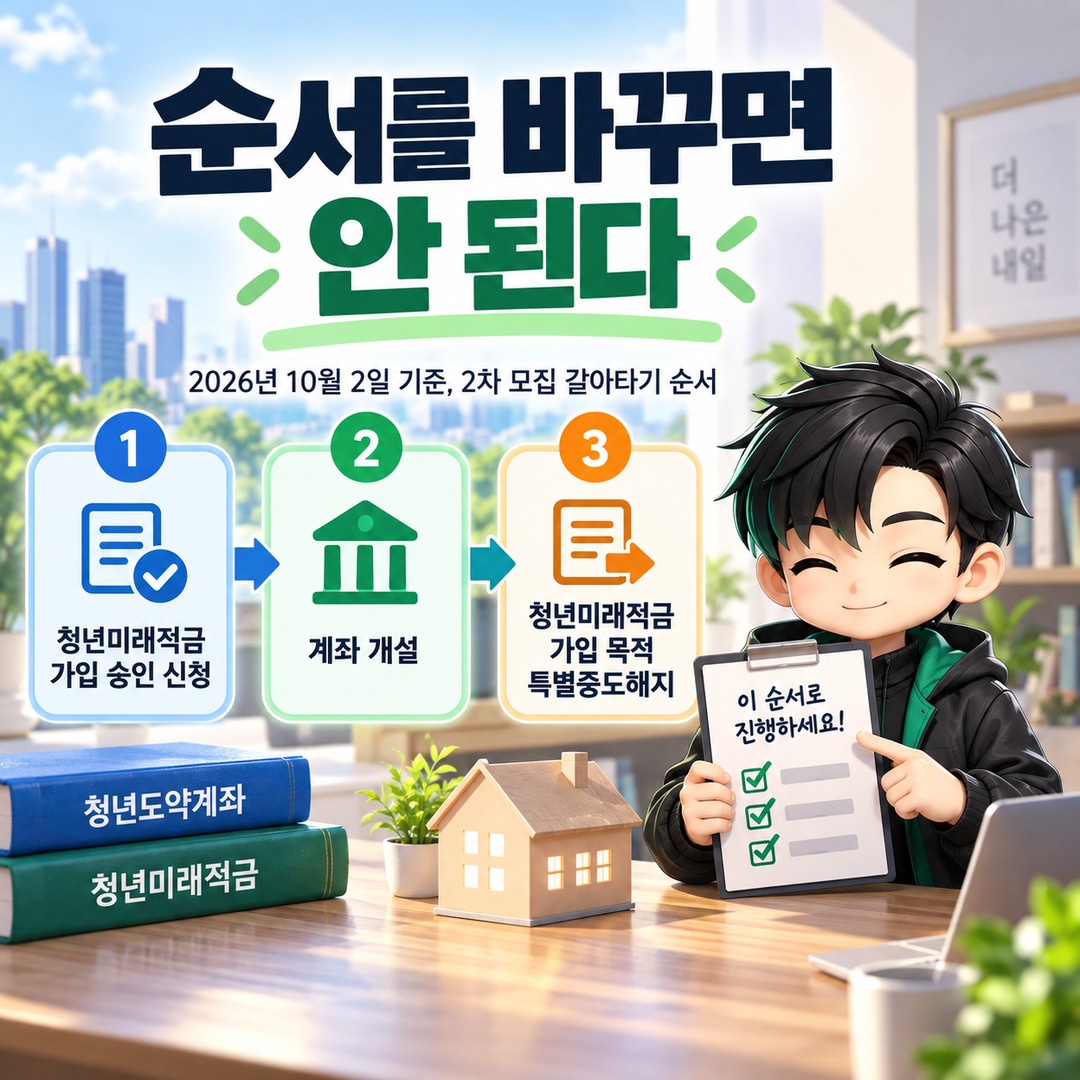
The Required Sequence Must Not Be Changed
As of 2026-10-02, the switching procedure announced for the 2th enrollment round is as follows.
1. Apply to join the Youth Future Savings Account.
2. Complete the eligibility screening and receive confirmation that enrollment is permitted.
3. Open the Youth Future Savings Account first.
4. Apply for special early termination of the existing Youth Leap Account for the purpose of joining the Youth Future Savings Account.
5. Begin making deposits into the Youth Future Savings Account after the special early termination has been processed.
This sequence is necessary because simultaneous enrollment in the Youth Leap Account and the Youth Future Savings Account is not permitted. If the account holder fails to complete the special early termination of the Youth Leap Account within the prescribed period after opening the Youth Future Savings Account, deposits cannot be made into the new account. If the switching process has not been completed, the existing Youth Leap Account remains in place.
According to the official guidance, special early termination of the Youth Leap Account must be requested through the app of the bank where the account was originally opened.
You Cannot Deposit the Entire Youth Leap Account Closure Proceeds into the Youth Future Savings Account at Once
Switching is not a direct account-to-account transfer of all the money held in the existing account.
The program does not support depositing the entire amount received from the special early termination of a Youth Leap Account into the Youth Future Savings Account as a single lump-sum payment. Financial authorities also stated in their guidance for the 1th enrollment round that lump-sum deposits of Youth Leap Account closure proceeds into the Youth Future Savings Account are not supported.
The Youth Future Savings Account is a 3-year maturity product that allows flexible monthly deposits of up to KRW 500,000. Depending on the enrollment category and other conditions, government contributions are calculated at 6% or 12% of the deposited amount. Some income brackets may qualify only for tax benefits, without government contributions.
In other words,
The account holder completes a special early termination while retaining the benefits earned through the existing Youth Leap Account → then begins making new deposits into the Youth Future Savings Account as a separate savings product.
This is the correct way to understand the switching arrangement.
When Should You Apply to Switch During October?
Applications for the 2th enrollment round of the Youth Future Savings Account are accepted from 2026-10-07 through 16. Applicants who pass the eligibility screening can open their accounts from November 16 through 27.
Young people whose birth years end in an odd digit may apply on October 7, while those whose birth years end in an even digit may apply on October 8. From October 12 through 16, applications are accepted regardless of birth year.
Existing Youth Leap Account holders who wish to switch must also satisfy the eligibility requirements for the Youth Future Savings Account and pass the screening process. Simply holding a Youth Leap Account does not automatically establish eligibility for the Youth Future Savings Account.
The New Product's Terms Apply After Enrollment in the Youth Future Savings Account
It is important to distinguish between benefits accumulated through the Youth Leap Account before switching and benefits newly earned through the Youth Future Savings Account afterward.
The Youth Future Savings Account is a flexible-installment savings product with a 3-year maturity and a maximum monthly deposit of KRW 500,000. The current government contribution matching rates are 6% for the standard category and 12% for the preferential category. Interest income also qualifies for a tax exemption.
The government's 2027 budget proposal includes raising the preferential government contribution rate from 12% to 15% and applying 25% to employees of small and medium-sized enterprises in regional areas. However, as of 2026-10-02, these measures remain proposals within a budget bill that must undergo National Assembly review. The Financial Services Commission has indicated that, if the budget proposal is finalized, the increased preferential contributions are expected to be paid retroactively to existing Youth Future Savings Account subscribers as well.
Therefore, anyone deciding whether to enroll now should not calculate the proposed 2027 increase in government contributions as though it were already a confirmed benefit.
Two Things to Check Before Actually Switching
The first is whether you have passed the eligibility screening for the Youth Future Savings Account. Rather than closing your Youth Leap Account first, the official procedure is to apply for the Youth Future Savings Account, undergo screening, receive confirmation of eligibility, and open the new account before proceeding with the special early termination.
The second is to compare the terms of your current Youth Leap Account separately from the benefits you would receive through the Youth Future Savings Account. The Youth Leap Account allows monthly deposits of up to KRW 700,000 and has a 5-year maturity, with government contributions determined according to income brackets. The Youth Future Savings Account allows monthly deposits of up to KRW 500,000 and has a 3-year maturity. Its current government contribution structure provides 6% for the standard category and 12% for the preferential category.
Therefore, preserving existing benefits and determining which product's future terms are better suited to an individual's circumstances are two separate questions.
As of 2026-10-02, one point is clearly confirmed: By following the official switching procedure, account holders can move from the Youth Leap Account to the Youth Future Savings Account while preserving government contributions and income tax exemptions on interest associated with amounts already deposited into the Youth Leap Account.