

Switching from the Youth Leap Account to the Youth Future Savings Account: Why You Should Not Close Your Existing Account First and the November Application Process
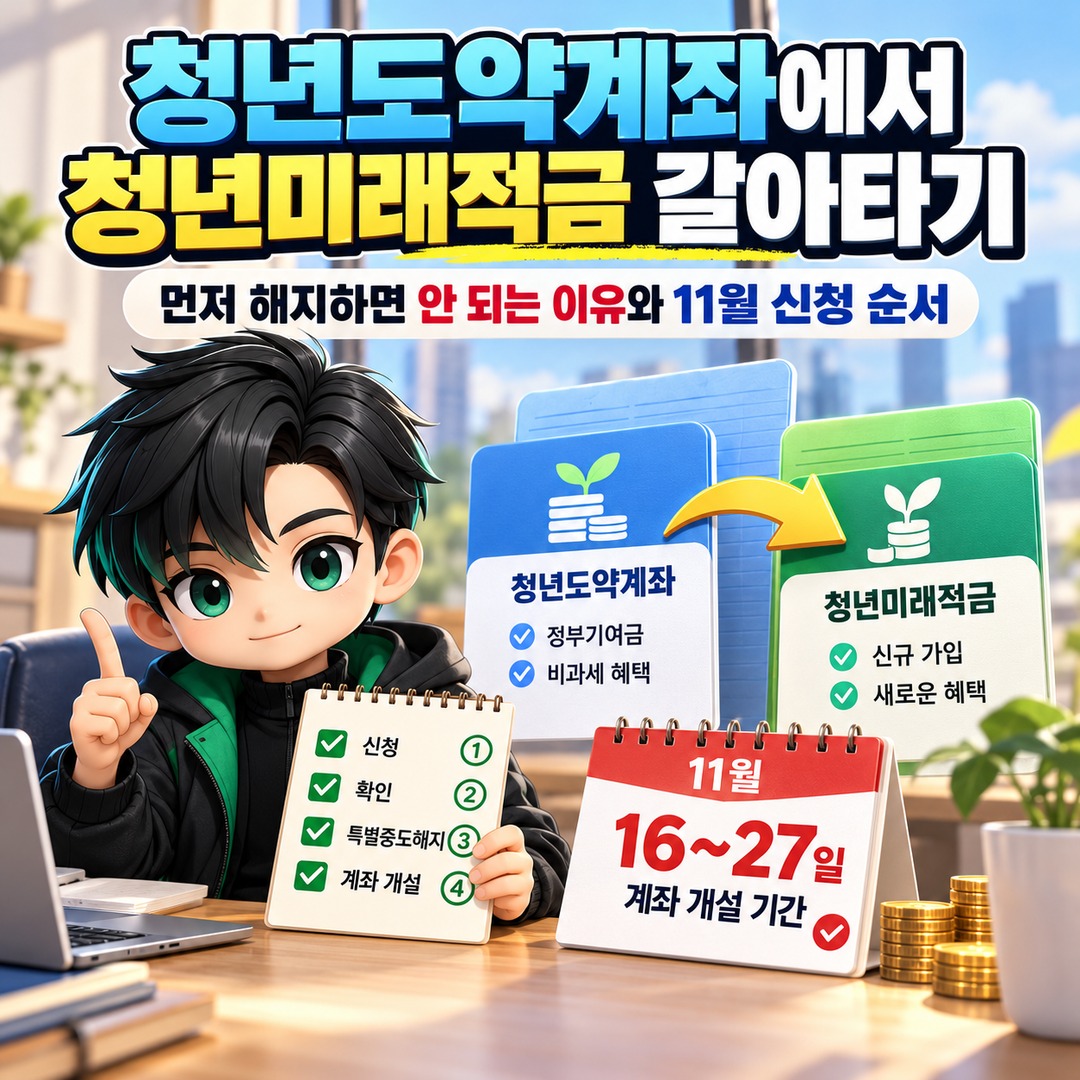
Youth Leap Account holders who completed the 2 round of Youth Future Savings Account applications in October 2026 should not close their existing accounts first. They should confirm their eligibility for the Youth Future Savings Account before proceeding with the switch. The transition process for both products can be completed during the November account-opening period, from 16 to 27. To retain existing government contributions and tax-exempt benefits, account holders must complete a special early termination through the prescribed procedure.
One particularly important distinction is that ordinary early termination and special early termination for switching accounts are not the same.
*Information verified as of 2026-10-19, based on official guidance from the Financial Services Commission and the Korea Inclusive Finance Agency.*
1. Why Could Closing Your Youth Leap Account First Cause Problems?
The most important requirement when moving from the Youth Leap Account to the Youth Future Savings Account is meeting the conditions for special early termination.
The Youth Leap Account is generally a savings product with a 5-year maturity. If it is closed before maturity, the benefits available may vary depending on the reason for termination and how long the account has been maintained.
However, using the government's official switching procedure for the Youth Future Savings Account allows account holders to retain government contributions and income tax exemptions on interest from their existing accounts through special early termination.
| Category | Ordinary Early Termination | Official Account Switch |
|---|---|---|
| Termination method | Ordinary account closure | Special early termination |
| Government contributions | Vary by holding period and reason | Special termination benefits apply |
| Income tax exemption on interest | Varies according to eligibility requirements | Tax-exempt benefits retained |
| Timing | Account holder's choice | Designated switching period |
| Important consideration | Potential reduction in benefits | Approval for the new account required |
Therefore, account holders should avoid closing their existing Youth Leap Accounts simply because they want to join the Youth Future Savings Account.
If an account has already been closed through ordinary early termination, subsequently joining the Youth Future Savings Account does not automatically convert that previous closure into a special early termination. Account holders must separately check with their original bank whether the relevant benefits can still apply.
2. What Is the November 2026 Switching Schedule?
According to the 2 recruitment schedule announced by the Financial Services Commission, applications, eligibility reviews, and account openings for the Youth Future Savings Account take place during separate periods.
| Stage | Schedule |
|---|---|
| 2 application round | October, 7–16 |
| Income and eligibility review | October 19–November 13 |
| Account opening | November, 16–27 |
| Switching from the Youth Leap Account | November, 16–27 |
As of October 19, the application period has ended and eligibility reviews are underway.
Existing Youth Leap Account holders do not need to close their accounts before receiving their eligibility review results.
During the November account-opening period, applicants must complete both the Youth Future Savings Account enrollment process and the special early termination procedure for their Youth Leap Accounts.
However, the schedule may be adjusted depending on the progress of eligibility reviews and other circumstances. Applicants should check the instructions in their banking apps before proceeding.
3. Step-by-Step Process for Switching from the Youth Leap Account to the Youth Future Savings Account
The basic procedure announced for the 2 application round in 2026 is as follows.
Step One: Apply for the Youth Future Savings Account
Applicants should have submitted their applications through a participating financial institution's app during the application period from 7 to 16 in October.
Holding a Youth Leap Account does not exempt applicants from the Youth Future Savings Account eligibility review.
Step Two: Check the Youth Future Savings Account Eligibility Review Results
Applicants should confirm whether they are eligible to open an account based on the review results announced in November.
The Youth Future Savings Account requires applicants to meet eligibility conditions involving age, personal income or business revenue, household income, and other criteria.
Step Three: Open a Youth Future Savings Account
Applicants who receive confirmation of eligibility should open their new accounts between 16 and 27 in November.
Step Four: Complete Special Early Termination of the Existing Youth Leap Account
After opening the Youth Future Savings Account, applicants must complete the special early termination procedure for their Youth Leap Accounts within the same period.
The 2026-10-01 guidance provided by the Government Civil Complaints Information Call Center also explains that the Youth Leap Account should be closed through special early termination within the same period after the Youth Future Savings Account has been opened.
In other words, the essential sequence is as follows.
Apply for the Youth Future Savings Account → Pass the Eligibility Review → Open the New Account → Complete Special Early Termination of the Existing Youth Leap Account
This is different from closing the existing account first.
4. Is Switching from the Youth Leap Account Always More Advantageous?
Not necessarily.
The Youth Future Savings Account has a 3-year maturity, while the Youth Leap Account has a 5-year maturity. Although the shorter maturity can be an advantage, the actual financial benefit depends on factors including the existing account's contribution period, interest rate, and government contributions.
The basic structure of the Youth Future Savings Account is as follows.
| Item | Youth Future Savings Account |
|---|---|
| Maturity | 3 years |
| Monthly contribution limit | KRW 500,000 |
| Government contribution for the standard type | 6% of contributions |
| Government contribution for the preferential type | 12% of contributions |
| Tax benefits | Income tax exemption on interest |
For example, assume that an account holder contributes KRW 500,000 every month for 36 months.
<text weight="medium">Standard Type</text>
Personal contribution principal: KRW 18,000,000
Government contributions: KRW 1,080,000
Total principal and government contributions: KRW 19,080,000
<text weight="medium">Preferential Type</text>
Personal contribution principal: KRW 18,000,000
Government contributions: KRW 2,160,000
Total principal and government contributions: KRW 20,160,000
These amounts are calculated on the assumption that the full KRW 500,000 is contributed every month and that the respective government contribution rates apply. Bank interest is not included.
The difference in government contributions between the two types is KRW 1,080,000.
However, this calculation alone is not enough to determine whether switching from the Youth Leap Account would be financially advantageous.
If an account holder has already contributed to the existing Youth Leap Account for a substantial period, the remaining time until maturity and the benefits they would receive by continuing the account must also be compared.
In particular, the annual 14%-range or 19%-range equivalent returns described by the Financial Services Commission for the Youth Future Savings Account are comparative figures that convert government contributions, tax exemptions, and other benefits into an annualized equivalent. They do not mean that banks directly pay interest at those rates.
5. What Happens to the Money Already Saved in the Existing Youth Leap Account?
When a Youth Leap Account is closed through special early termination, the account holder receives the principal contributed to the existing account, applicable interest, government contributions, and other amounts according to the termination settlement rules.
Importantly, account holders should not assume that the accumulated balance in their existing Youth Leap Account will automatically transfer to the Youth Future Savings Account.
The Youth Future Savings Account is a separate savings product with a 3-year maturity and a maximum monthly contribution of KRW 500,000.
Therefore, account holders should not assume that they can deposit the entire amount received from closing their existing accounts into the Youth Future Savings Account in a single payment.
Anyone considering switching should distinguish between the following two amounts.
The actual termination proceeds received from the existing Youth Leap Account
The amount they plan to contribute to the new Youth Future Savings Account going forward
Account holders should check their estimated termination proceeds with their existing bank and plan future contributions according to the new account's monthly contribution limit.
6. What Happens to the Existing Account If the Youth Future Savings Account Application Is Rejected?
Applicants who do not pass the Youth Future Savings Account eligibility review do not need to close their existing Youth Leap Accounts for switching purposes.
This is because the switching procedure begins only after applicants receive confirmation that they are eligible to join the Youth Future Savings Account.
The appropriate response depends on the applicant's situation.
| Current Situation | Recommended Action |
|---|---|
| Youth Future Savings Account eligibility review underway | Keep the existing account |
| Not eligible for the Youth Future Savings Account | Consider keeping the existing account |
| Eligible for the Youth Future Savings Account | Open the new account, then complete special early termination |
| Existing account already closed through ordinary termination | Check applicable benefits with the original bank |
In particular, existing Youth Leap Account holders are not automatically approved for the Youth Future Savings Account simply because they previously enrolled in the older product.
Furthermore, simultaneous enrollment in both products is generally not permitted. Applicants who choose to switch must therefore complete the designated special early termination procedure.
7. 4 Things You Must Check Before Switching
Whether moving to the Youth Future Savings Account is financially advantageous depends on the current status of the existing Youth Leap Account.
Check the following items first.
1. Remaining maturity of the Youth Leap Account: If you have already been contributing for a long time, compare the benefits of keeping your existing account.
2. Current government contributions: Check the contribution rate applicable to your income bracket and the amount you are expected to receive in the future.
3. Youth Future Savings Account enrollment type: Government contribution rates differ depending on whether you qualify for the standard or preferential type.
4. Actual interest rates offered by each bank: Look beyond the advertised maximum rate and determine whether you can meet preferential interest rate conditions, such as salary transfers or card spending requirements.
In particular, if your existing Youth Leap Account is approaching maturity, switching simply because the Youth Future Savings Account advertises a higher maximum return may not be appropriate.
It is important to compare the remaining terms and actual expected proceeds of both products on a consistent basis.
8. Frequently Asked Questions
Q. Can I Keep My Youth Leap Account While Also Joining the Youth Future Savings Account?
Generally, no.
The Financial Services Commission does not permit simultaneous enrollment in both products and has established a separate switching procedure for existing Youth Leap Account holders who want to move to the Youth Future Savings Account.
Q. Can I Open a New Youth Future Savings Account After My Youth Leap Account Reaches Maturity?
According to the Financial Services Commission's stated policy, applicants cannot join the Youth Future Savings Account even after their Youth Leap Account reaches maturity.
However, the special switching procedure established for existing Youth Leap Account holders applies separately.
Q. Will I Lose All My Youth Leap Account Government Contributions If I Switch?
No.
If you meet the special early termination requirements for joining the Youth Future Savings Account, the government contributions associated with your existing Youth Leap Account deposits and the income tax exemption on interest will be retained.
The actual amount received upon termination will depend on the contribution history of the existing account and the bank's settlement rules.
Q. Can I Still Switch After November 27?
The officially announced account-opening and switching period for the 2 application round in 2026 runs from November 16 through 27.
Additional opportunities after this period are not guaranteed. Applicants should check separate announcements from the Financial Services Commission and the Korea Inclusive Finance Agency for any schedule changes or extensions.
9. What Should You Do First Right Now?
As of 2026-10-19, applicants planning to switch from the Youth Leap Account to the Youth Future Savings Account should not close their existing accounts yet.
The official procedure is to wait for the eligibility review results in November, receive confirmation of eligibility, and then proceed with opening the new account and completing special early termination.
The Key Is Not to Close Your Youth Leap Account First and to Confirm the November Switching Period from 16 to 27.
For details on the termination procedure and estimated proceeds, contact the bank where your existing account is held. For questions about Youth Future Savings Account applications and eligibility reviews, contact the Korea Inclusive Finance Agency's Youth Finance Call Center at 1397 (shortcut 3).