

Mortgage Prepayment Penalties: The Cost of Repaying Before 3 Years and the Interest Difference When Waiting Until the Waiver Date
Even if 3 years have not passed since you took out your mortgage, it may be more advantageous to repay early and pay the prepayment penalty. The penalty depends on the repayment amount, the contractual penalty rate, and the remaining penalty period. If the interest incurred while waiting until the waiver date exceeds the penalty, early repayment is more beneficial.
As of 2026-10-14, the key factors are the loan origination date and contractual terms. Although the calculation standards for prepayment penalties changed starting in 2025, the new penalty rates do not automatically apply to all previously issued loans.
How Much Is the Mortgage Prepayment Penalty in 2026?
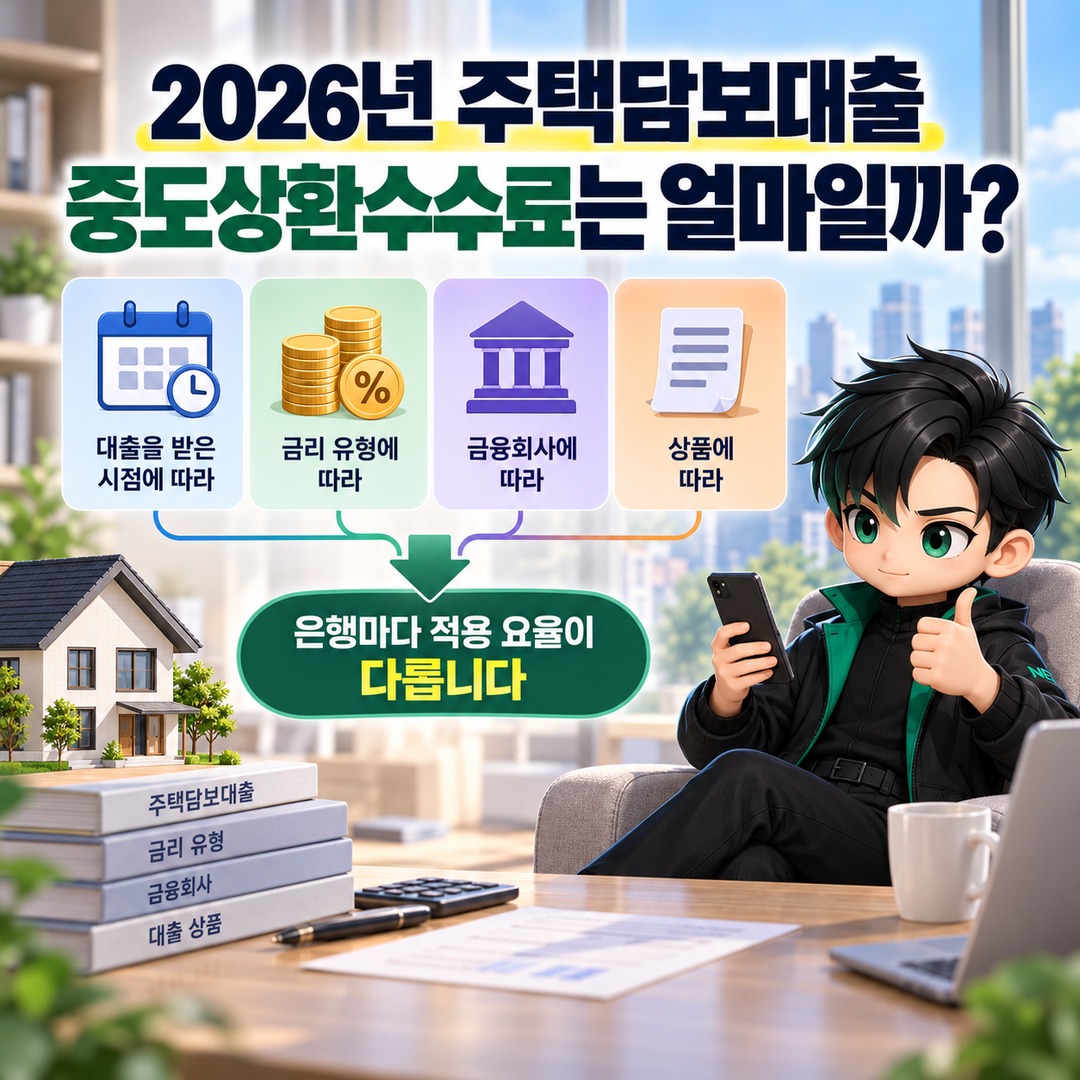
Mortgage prepayment penalties are not calculated at the same rate across all banks. The applicable rate varies depending on when the loan was originated, the interest rate type, the financial institution, and the loan product.
The differences are clear in the real estate-secured loan standards published by KB Kookmin Bank on July 2026.
| Loan origination period | Variable interest rate | Other interest rate types |
|---|---|---|
| Before 2025-01-12 | 1.20% | 1.40% |
| 2025-01-13–December 31 | 0.58% | 0.58% |
| From 2026-01-01 onward | 0.55% | 0.75% |
Here, 'other interest rate types' follow the bank's classification criteria concerning interest rate adjustment intervals, fixed-rate periods, and related conditions.
A new KB Kookmin Bank variable-rate mortgage originated in 2026 can be calculated using 0.55%. However, if your mortgage is with another bank, you must check the contractual penalty rate applicable to that financial institution.
In particular, someone who took out a loan in 2024 does not automatically qualify for the prepayment penalty rate on new loans issued in 2026 simply because they repay the loan in 2026.
How Much Is the Penalty for Repaying KRW 100,000,000 Before 3 Years Have Passed?
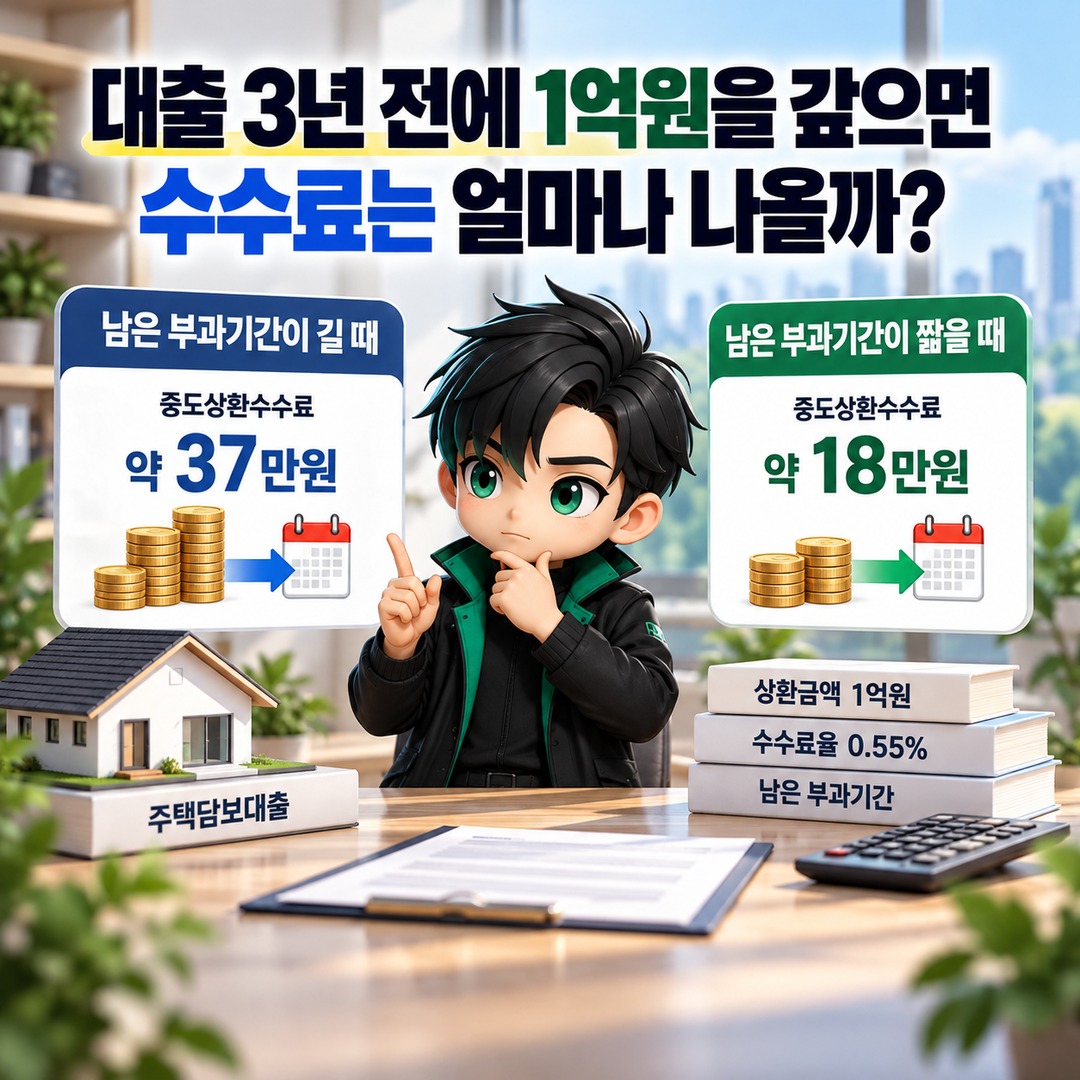
Using the 0.55% penalty rate for a new KB Kookmin Bank variable-rate mortgage originated in 2026 as an example, the penalty for repaying KRW 100,000,000 could be approximately 18 ten-thousand-won units to KRW 370,000, depending on the remaining penalty period.
The general calculation formula is as follows.
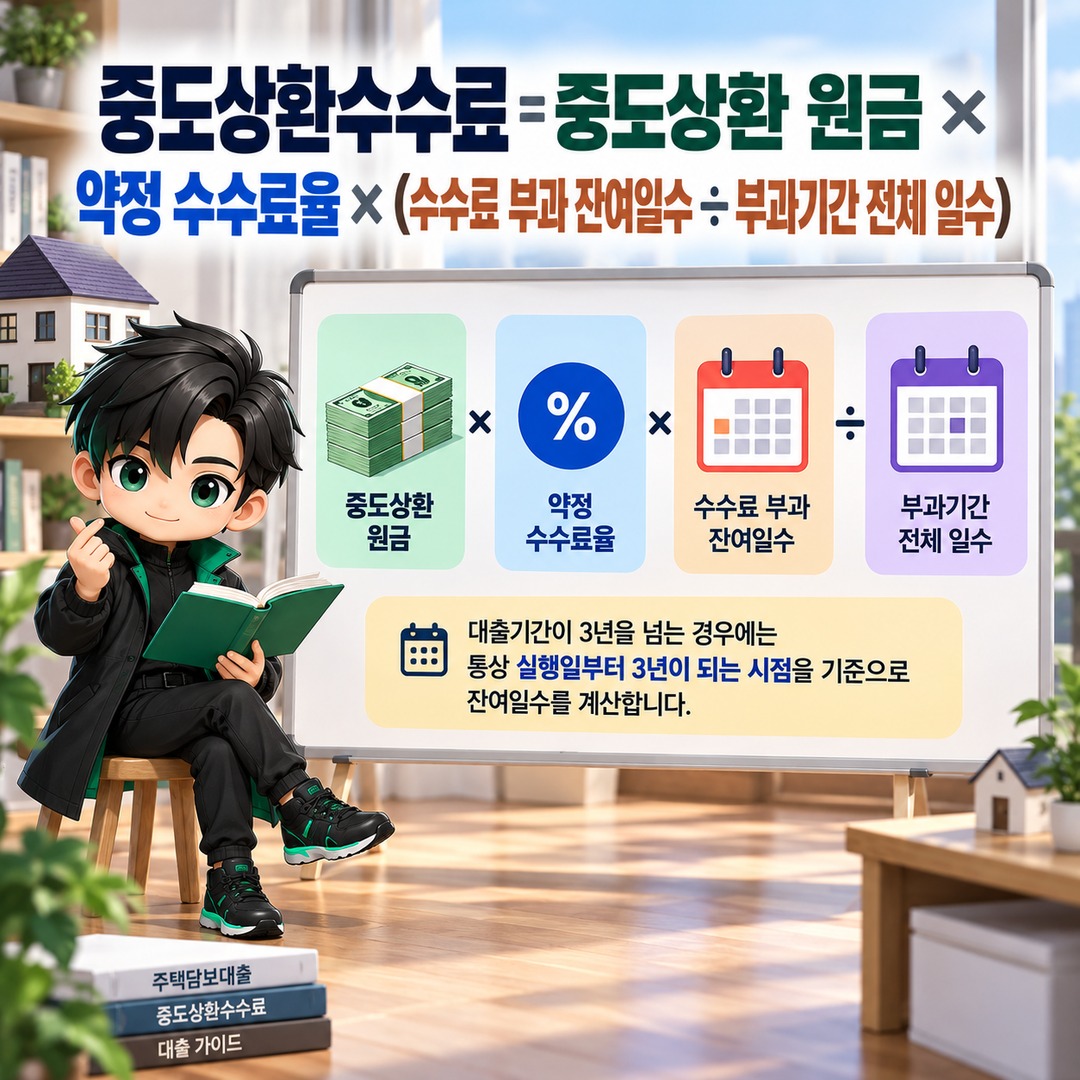
Prepayment Penalty = Principal Repaid Early × Contractual Penalty Rate × (Remaining Days in the Penalty Period ÷ Total Days in the Penalty Period)
When the loan term exceeds 3 years, the remaining days are generally calculated based on the point when 3 years have elapsed from the loan origination date.
Assuming a repayment principal of KRW 100,000,000, a penalty rate of 0.55%, and a penalty period of 3 years, the results are as follows.
| Repayment timing | Remaining penalty period | Estimated penalty |
|---|---|---|
| 1 years after origination | Approximately 2 years | Approximately KRW 367,000 |
| 2 years after origination | Approximately 1 years | Approximately KRW 183,000 |
| 2 years and 6 months after origination | Approximately 6 months | Approximately KRW 92,000 |
| After 3 years have elapsed since origination | None | KRW 0 |
The amounts above are simplified calculations assuming 1,095 days over 3 years. Actual amounts vary depending on leap years, origination and repayment dates, day-count calculations, and each bank's processing standards.
Also, the penalty is calculated based on the principal actually repaid early, not the entire original loan amount.
Even if the outstanding loan balance is KRW 300,000,000, repaying only KRW 100,000,000 means the penalty is generally calculated based on KRW 100,000,000. If a penalty-free repayment allowance applies, the amount subject to the penalty may be even smaller.
If the Penalty Is KRW 0 After the Waiver Date, Why Might Repaying Early Be Better?
Saving on prepayment penalties and reducing the total cost of a loan are two different considerations.
Interest continues to accrue while the loan remains outstanding. Therefore, you need to compare the additional interest payable while waiting until the waiver date with the penalty incurred by repaying now.
For example, assume the following conditions.
Principal to repay now: KRW 100,000,000
Current loan interest rate: 4.0% annually
Prepayment penalty rate: 0.55%
Time elapsed since loan origination: 2 years
Time remaining until the penalty waiver: Approximately 1 years
Under these conditions, the prepayment penalty is approximately KRW 183,000.
By contrast, if you do not repay KRW 100,000,000 and keep that amount outstanding for another 1 years, approximately KRW 4,000,000 in interest will accrue under a simple interest calculation.
Penalty for repaying now
Approximately KRW 183,000.0
Simple interest from waiting 1 years
Approximately KRW 4,000,000
Cost Comparison Based on Repayment Principal of KRW 100,000,000
Assumes an annual interest rate of 4%, a penalty rate of 0.55%, and approximately 1 years remaining until the waiver date
| Item | Cost (ten thousand KRW) |
|---|---|
| Penalty for repaying now | 18.3 |
| Interest from keeping the loan for 1 years | 400 |
Author's calculation. This is a simplified comparison assuming the principal of KRW 100,000,000 remains unchanged for 1 years. The actual interest difference must be calculated separately according to the repayment method.
In this example, repaying now substantially reduces borrowing costs compared with waiting until the prepayment penalty waiver date.
However, using all available cash for repayment could leave you without sufficient emergency funds. Therefore, the actual decision should also account for living expenses that need to be retained and the after-tax returns available from deposits and other financial products.
Does the Decision Change If Only 30 Days Remain Until the Waiver Date?
If only 30 days remain until the waiver date, the penalty itself will also have decreased considerably. In this situation, you can compare the interest for 30 days with the remaining penalty.
Assume a repayment principal of KRW 100,000,000, an annual interest rate of 4.0%, a prepayment penalty rate of 0.55%, and a penalty period of 1,095 days over 3 years.
The simple interest accrued over 30 days is calculated as follows.
KRW 100,000,000 × 4.0% × 30 days ÷ 365 days = Approximately KRW 329,000
The prepayment penalty corresponding to the same period is calculated as follows.
KRW 100,000,000 × 0.55% × 30 days ÷ 1,095 days = Approximately KRW 15,000
Waiting until the waiver date would avoid approximately KRW 15,000 in penalties, but approximately KRW 329,000 in additional interest would accrue during that time.
The difference between the two amounts is approximately KRW 314,000.
This calculation assumes that the principal remains constant, the interest rate does not change, and the available cash earns no return.
A short remaining period until the waiver date does not necessarily mean waiting is more advantageous.
Do You Have to Pay a Penalty Even If You Repay Only Part of the Loan?
A prepayment penalty may apply even when you repay only part of the loan. However, some loan products allow you to repay up to a certain amount without incurring a penalty.
For general real estate-secured loans offered by KB Kookmin Bank, the bank provides a penalty waiver for annual repayments of up to 10% of the original loan amount. The waiver percentage may differ for certain group loans used to finance the final payment on newly occupied properties.
For example, if the original loan amount is KRW 300,000,000 and an annual waiver allowance of 10% applies, you could repay up to KRW 30,000,000 without a penalty, assuming no other early repayments have been made during that year.
Using this provision can reduce the outstanding principal and interest burden even before 3 years have elapsed.
However, you should verify the annual waiver allowance, whether unused allowances can be carried forward, and your previous repayment history for the specific loan product. KB Kookmin Bank's general guidance should not be assumed to apply identically to every financial institution.
Is It Better to Wait 3 Years Before Refinancing Your Mortgage?
If you plan to refinance into a mortgage with a lower interest rate, you need to compare the prepayment penalty on the existing loan with the interest savings from the new loan.
Repaying an existing loan with a new loan also counts as early repayment, so a penalty may apply if the existing loan is still within its penalty period.
For example, assume you refinance an outstanding loan balance of KRW 200,000,000 from an annual interest rate of 4.5% to 3.8% annually.
The interest rate difference is 0.7% percentage points annually.
Under a simplified calculation in which the principal remains unchanged, the interest savings over 1 years would be KRW 1,400,000.
If the existing loan's prepayment penalty is KRW 400,000 and other associated expenses are KRW 200,000, the initial cost would be KRW 600,000.
Under these conditions, the interest savings over approximately 5.1 months would equal the initial cost of KRW 600,000.
However, actual mortgage savings vary depending on the principal and interest repayment method, interest rate changes, the term of the new loan, and preferential interest rate conditions. You must also separately verify whether refinancing is possible under the current loan approval requirements.
Where Can You Check the Prepayment Penalty Waiver Date and Actual Repayment Amount?
The most accurate method is to use the lending financial institution's app or visit a branch to request an estimated repayment amount for a specific date.
Before deciding to repay, it is advisable to check the following information.
1. Loan origination date: The reference date used to calculate the 3-year penalty period
2. Contractual penalty rate: The rate applicable to your own contract, rather than the rate advertised for new loans
3. Penalty waiver date: The first date on which no prepayment penalty is charged
4. Penalty-free early repayment allowance: The amount of the waiver allowance already used and the amount remaining
5. Estimated repayment amount: The actual amount payable, including principal, penalties, and interest accrued through the repayment date
Changing the repayment date by even one day can affect both interest and penalties, so it is most accurate to request a new estimate based on the date you actually intend to repay.
In addition, government-supported mortgage products such as Didimdol Loans and Bogeumjari Loans may have different penalty standards or separate waiver conditions from ordinary bank mortgages.
Repaying Before 3 Years or Waiting Until the Waiver Date: What Should Determine Your Decision?
The central consideration is not the penalty rate itself but the difference in total future costs.
Repaying the loan now may incur a prepayment penalty, but it reduces future interest on the principal that has been repaid.
Conversely, waiting until the waiver date can save the penalty but results in additional loan interest.
Therefore, you can compare the following two amounts.
Cost of Repaying Now = Prepayment Penalty + Returns Forgone by Using Cash for Repayment, etc. Cost of Waiting = Additional Loan Interest Accrued Until the Waiver Date
By also considering liquidity needs and refinancing costs, you can make a decision suited to your actual circumstances.
In particular, if your loan was originated before 2025, you should first verify the contractual penalty rate that applied at the time. Using the reduced rates for new loans issued in 2026 to calculate the cost of repaying your own loan could produce an estimate that differs significantly from the actual amount.
Once you know how much you intend to repay and how many days remain until the waiver date, the most reliable starting point is to obtain the bank's estimated prepayment amount for the intended repayment date.