

Mortgage Loan Limits by Annual Salary: In 2026, DSR 40% and Regional Stress Interest Rates Make the Difference
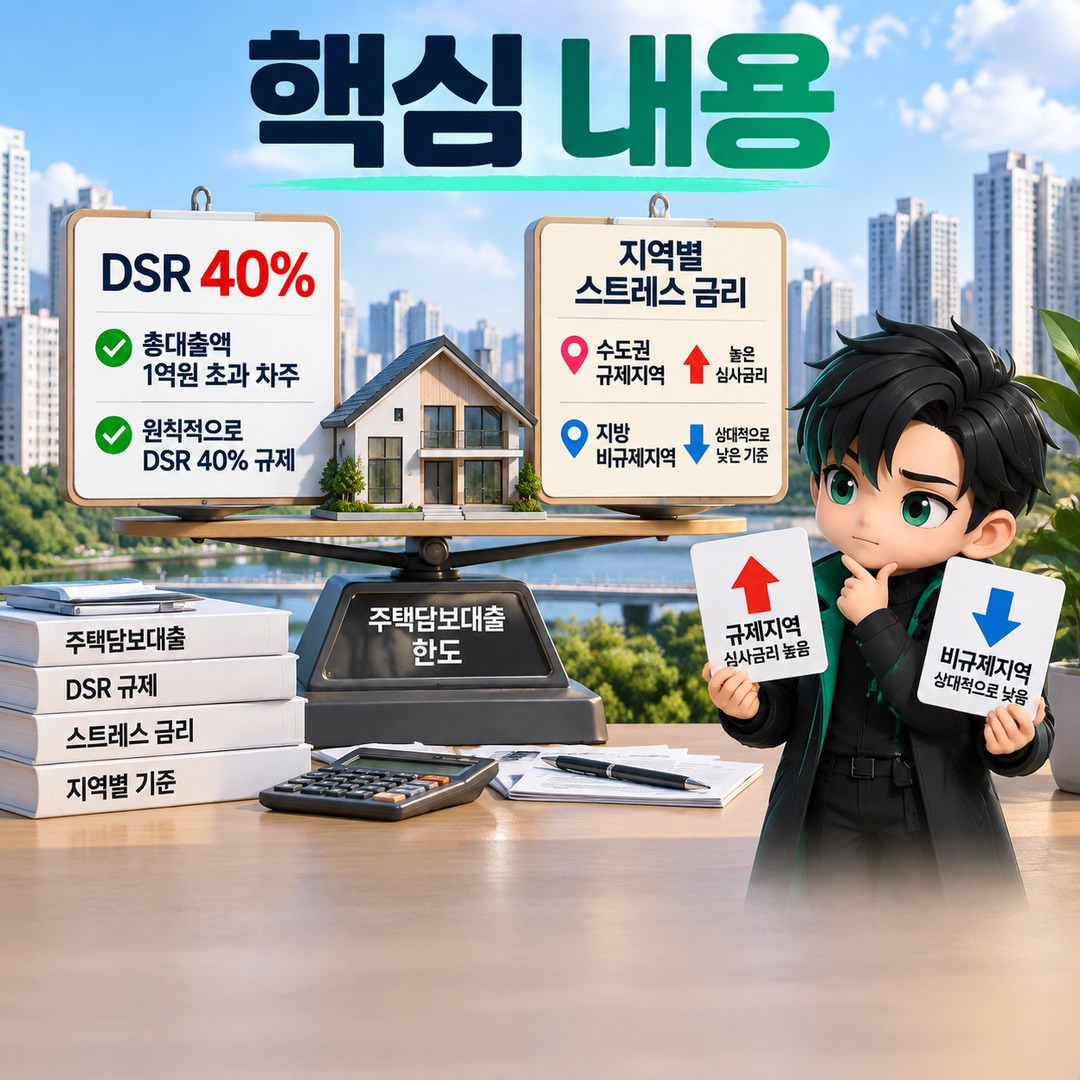
Mortgage loan limits are not fixed at a certain multiple of annual salary. Under 2026-09-29 banking-sector standards, borrowers whose total outstanding loans exceed KRW 100,000,000 must generally comply with the DSR 40% regulation. Mortgage loans are also subject to stress DSR calculations that vary by region and interest rate structure. In the Seoul metropolitan area and regulated regions, loan limits are calculated using an assessment interest rate higher than the actual borrowing rate, which can result in different limits even for borrowers with the same annual income compared with those in non-regulated regions outside the metropolitan area.
How Much Can You Borrow with an Annual Salary of 5 Thousand Won?
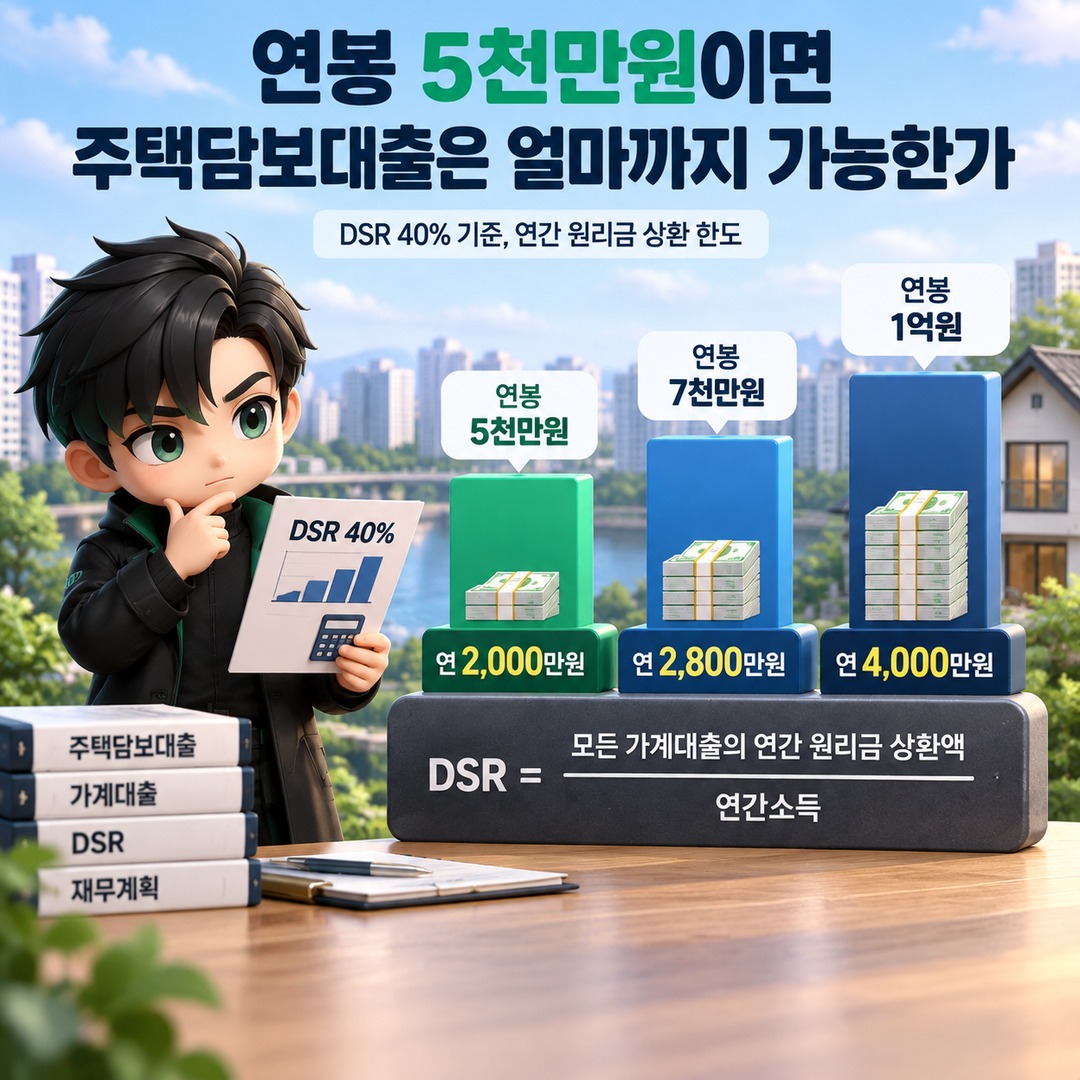
Looking only at the banking-sector DSR 40% requirement, someone earning KRW 50,000,000 annually must keep their combined annual principal and interest repayments on all loans within KRW 20,000,000. For annual incomes of KRW 70,000,000 and KRW 100,000,000, the corresponding annual repayment limits are KRW 28,000,000 and KRW 40,000,000, respectively. DSR is calculated by dividing the annual principal and interest repayments on all household loans by annual income.
However, knowing your annual salary alone does not immediately determine your final mortgage loan amount. Other factors are considered, including the interest rate and maturity of the new mortgage, whether it has a floating, hybrid, or periodically resetting interest rate, and existing debts such as personal loans and car installment financing.
For comparison, the following calculations use identical assumptions: banking-sector DSR 40%, no existing loans, equal monthly principal and interest repayments, a 30-year maturity, an actual annual borrowing rate of 4.0%, and a floating interest rate.
| Annual Income Before Tax | Seoul Metropolitan Area and Regulated Regions | Non-Regulated Regions Outside the Metropolitan Area |
|---|---|---|
| KRW 30,000,000 | Approximately KRW 150,300,000 | Approximately KRW 191,700,000 |
| KRW 40,000,000 | Approximately KRW 200,400,000 | Approximately KRW 255,600,000 |
| KRW 50,000,000 | Approximately KRW 250,500,000 | Approximately KRW 319,500,000 |
| KRW 60,000,000 | Approximately KRW 300,600,000 | Approximately KRW 383,400,000 |
| KRW 70,000,000 | Approximately KRW 350,700,000 | Approximately KRW 447,300,000 |
| KRW 80,000,000 | Approximately KRW 400,800,000 | Approximately KRW 511,200,000 |
| KRW 100,000,000 | Approximately KRW 501,000,000 | Approximately KRW 639,000,000 |
The figures above are illustrative calculations prepared by the author. For the Seoul metropolitan area and regulated regions, the calculations assume an assessment rate of 7.0%, reflecting the actual interest rate of 4.0% plus a floating-rate stress adjustment of 3.0% percentage points. For non-regulated regions outside the metropolitan area, the assumed assessment rate is 4.75%, incorporating 0.75% percentage points under the standards applicable through the end of 2026. The stress interest rate is not an additional rate charged on the loan. It is used solely to calculate the DSR-based borrowing limit.
Therefore, this table is not a guaranteed approval chart stating that everyone with a particular annual salary can borrow the indicated amount. If the actual borrowing rate exceeds 4% or the borrower has existing loans, the DSR-based limit may be lower. The extent to which stress interest rates are reflected also varies depending on the interest rate structure, including hybrid and periodically resetting products.
Why Mortgage Limits Are Lower in the Seoul Metropolitan Area Even with the Same Salary
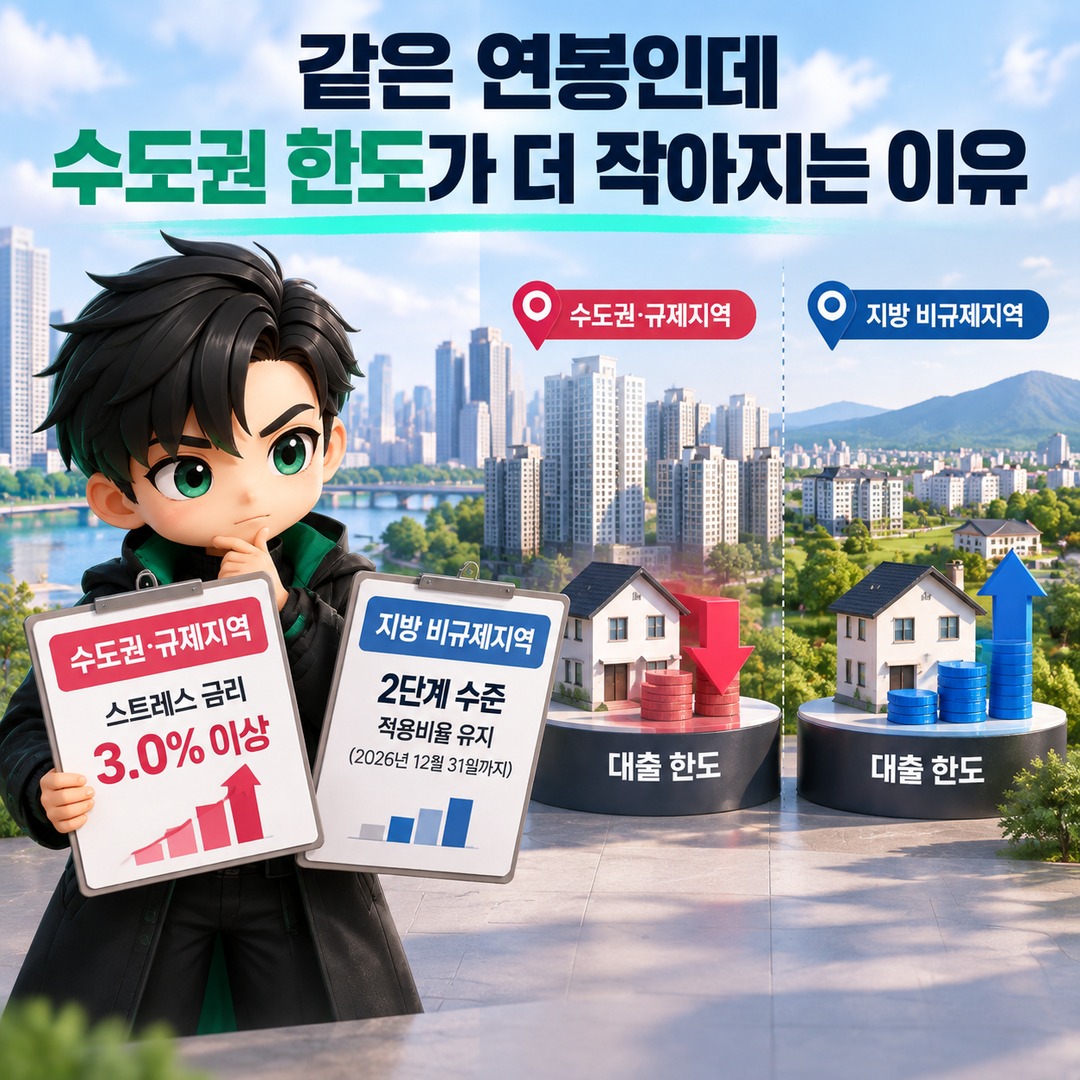
During the second half of 2026, stress DSR requirements differ between the Seoul metropolitan area and regulated regions and non-regulated regions outside the metropolitan area. Mortgage loans in the Seoul metropolitan area and regulated regions are subject to a stress interest rate of at least 3.0%, while mortgages outside these areas retain the application ratio corresponding to 2-stage standards through 2026-12-31.
For example, if a floating-rate mortgage has an actual annual interest rate of 4.0%, the DSR limit in the Seoul metropolitan area and regulated regions would be calculated using an annual rate of 7.0%. For an otherwise identical mortgage in a non-regulated region outside the metropolitan area, an illustrative calculation could use an annual rate of 4.75%.
This also explains the approximately KRW 69,000,000 difference between the previously calculated limits of approximately KRW 250,500,000 and KRW 319,500,000 for someone earning KRW 50,000,000 annually. This is an illustrative comparison calculated by the author, using identical income, actual interest rates, and a 30-year maturity, with only the regional stress interest rate differing.
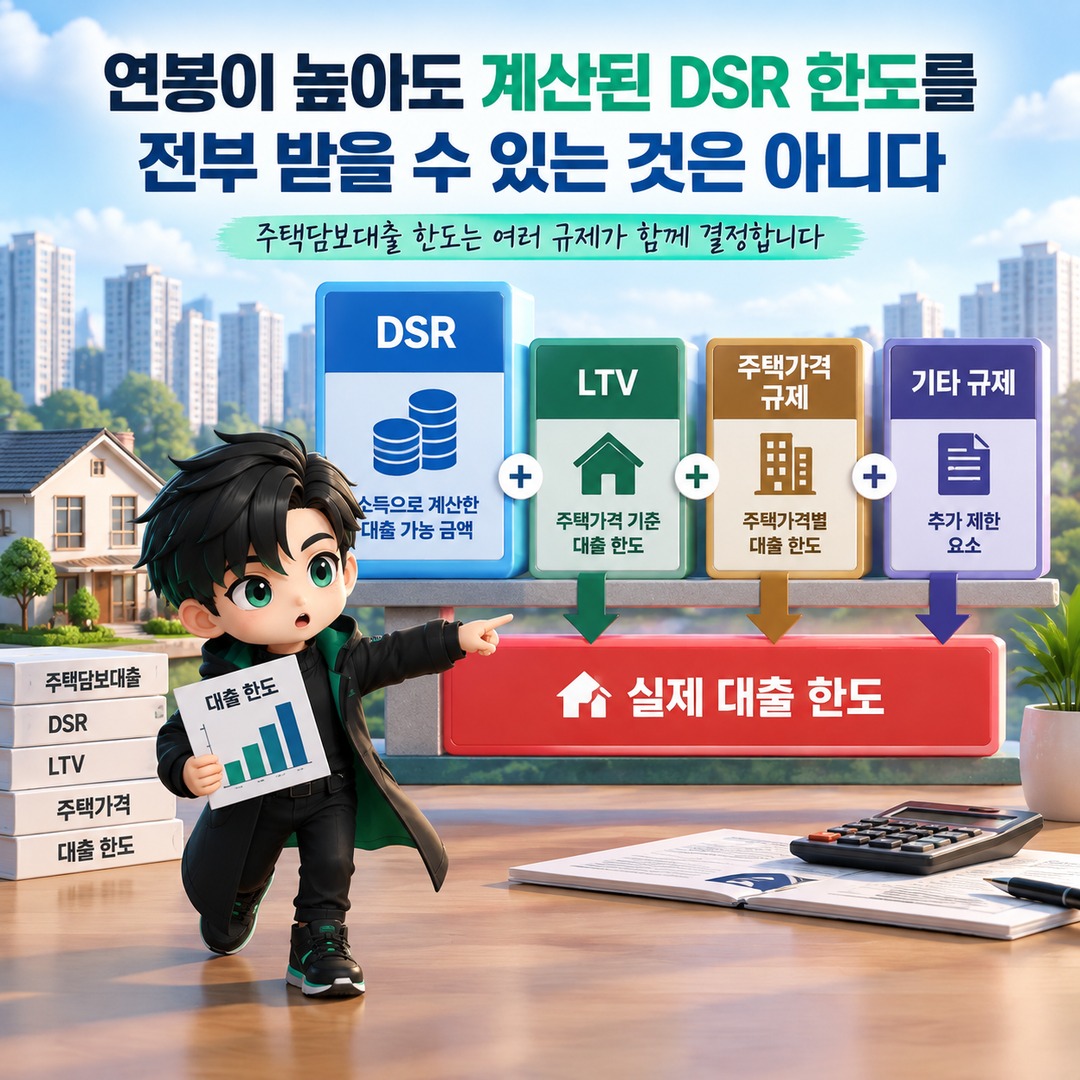
Even High-Income Borrowers May Not Qualify for the Full DSR-Based Loan Amount
The final mortgage limit is not determined by income alone. Even if the DSR calculation produces a sufficiently large borrowing amount, other regulations, such as loan-to-value (LTV) limits and property-price-based lending caps, may impose a lower ceiling. In that case, the lower limit determines how much can actually be borrowed.
For home-purchase mortgages in the Seoul metropolitan area and regulated regions, the maximum loan amount varies by the property's market value. If the market value is KRW 1,500,000,000 or less, the maximum is KRW 600,000,000. If it exceeds KRW 1,500,000,000 but does not exceed KRW 2,500,000,000, the maximum is KRW 400,000,000. If it exceeds KRW 2,500,000,000, the maximum is KRW 200,000,000. Even within these ceilings, the actual loan amount depends on applicable conditions, including LTV, DTI, and DSR requirements.
For example, even if a borrower's high annual income allows a DSR-based loan amount of KRW 700,000,000, purchasing a home with a market value of KRW 2,000,000,000 in the Seoul metropolitan area or a regulated region requires consideration of the separate property-price-based maximum of KRW 400,000,000.
Conversely, lower-income borrowers may reach their DSR-based borrowing limit before reaching the maximum allowed under the property-price-based rules.
In the Seoul Metropolitan Area, Be Careful About Using a 40-Year Mortgage Term to Increase Your Borrowing Limit
Since 2025-06-28, mortgage maturities in the Seoul metropolitan area and regulated regions have been restricted to 30 years or less. Therefore, when purchasing a home in the Seoul metropolitan area, using a basic mortgage calculator with a 40-year or 50-year repayment term to increase the estimated borrowing amount may not reflect current regulations.
A longer maturity can reduce the annual principal and interest repayment burden for the same loan amount, potentially increasing the borrowing limit under the DSR calculation. This is why borrowers should first confirm the maximum maturity actually permitted in their region before calculating their borrowing capacity.
If You Have Existing Personal Loans, Check Them Before Relying on Salary-Based Mortgage Tables
DSR does not calculate repayment capacity based solely on the new mortgage being requested. It considers existing household loans from financial institutions together with the new application. Borrower-level DSR requirements apply when total outstanding loans exceed KRW 100,000,000.
Therefore, earning KRW 50,000,000 annually does not mean that the entire KRW 20,000,000 annual principal and interest repayment allowance can be allocated to a new mortgage. If existing loans already contribute to the borrower's DSR calculation, the available repayment capacity for the new mortgage decreases accordingly.
Borrowers should also avoid assessing revolving credit lines solely by the amount currently drawn. Under the rules for determining total loan exposure, credit-line loans are assessed based on their approved limits rather than the amounts actually used. Existing debts should therefore be reviewed together before applying for a new mortgage.
Follow These Steps to Check Your Mortgage Borrowing Limit
First, confirm the annual income before tax recognized by the financial institution. Next, review existing household debts, including personal loans and revolving credit lines, and determine whether the property you intend to purchase is located in the Seoul metropolitan area, a regulated region, or a non-regulated region outside the metropolitan area.
Then check the actual interest rate of the proposed mortgage, whether it has a floating, hybrid, or periodically resetting rate, and the available repayment term to calculate the stress DSR. Finally, compare the result with the applicable LTV requirements and the property-price-based maximum mortgage limits for the Seoul metropolitan area and regulated regions.
Ultimately, rather than relying on a single formula such as 'My annual salary is this much, so I can borrow this amount,' it is more accurate to compare the DSR limit with collateral-based and regional lending restrictions in sequence. In particular, during the second half of 2026, different stress DSR requirements in the Seoul metropolitan area and regulated regions versus non-regulated regions outside the metropolitan area can produce different results even when annual income and actual interest rates are identical.
At the actual application stage, results may vary depending on the income recognized by the financial institution, how existing debts are reflected in DSR calculations, the loan product's interest rate structure, and collateral conditions. Borrowers should therefore reconfirm their borrowing limits with the relevant financial institution before signing a contract.
※ This article is provided for informational purposes to help readers understand market conditions and does not constitute an investment recommendation for any particular security or asset. Final decisions and responsibility for investment outcomes rest with the individual.
Related Articles
Can the iPhone Duo Really Not Use a Physical SIM Card at All?