

Mortgage Refinancing: Can You Reset the Term to 30 Years After Already Repaying 7 Years? Eligibility Requirements Explained
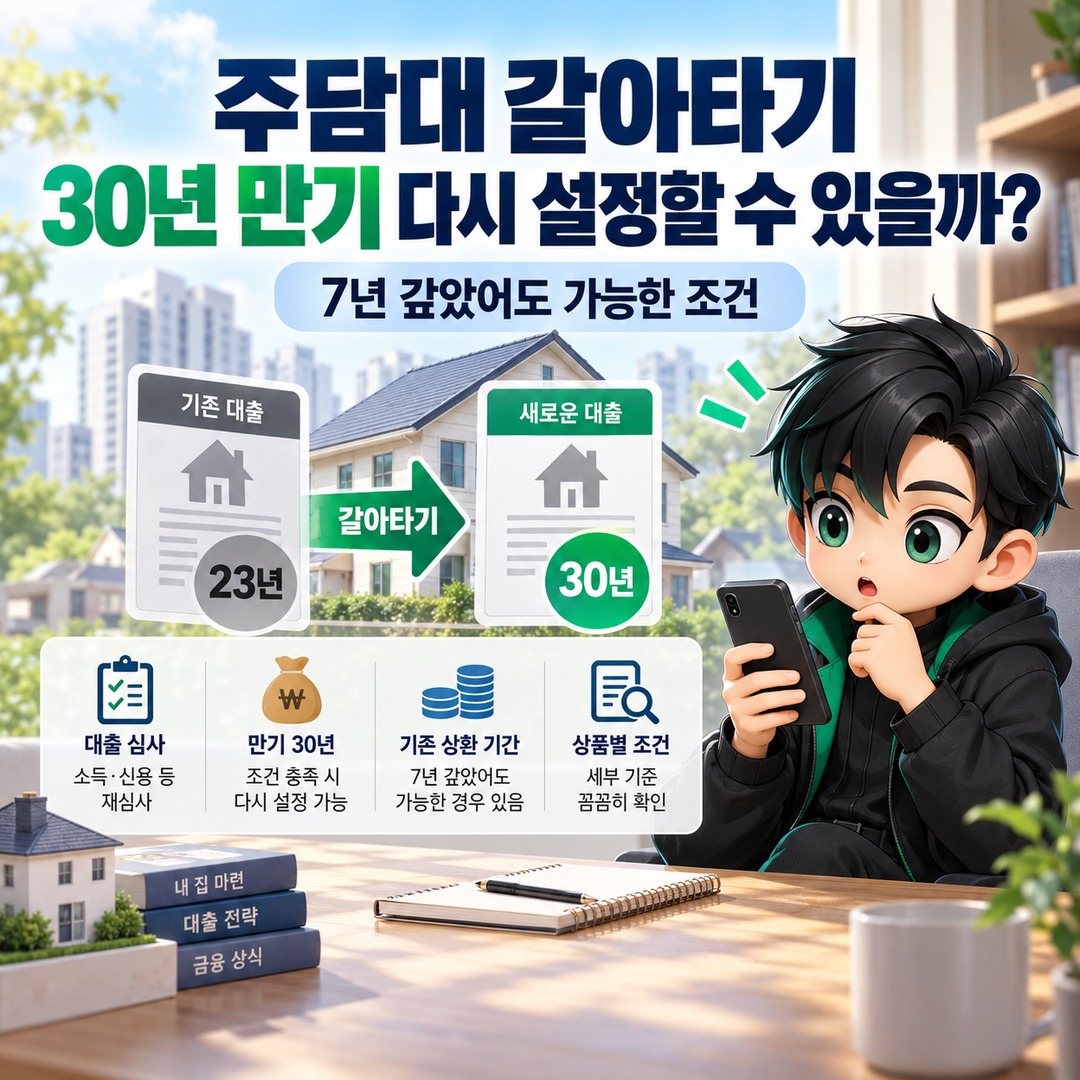
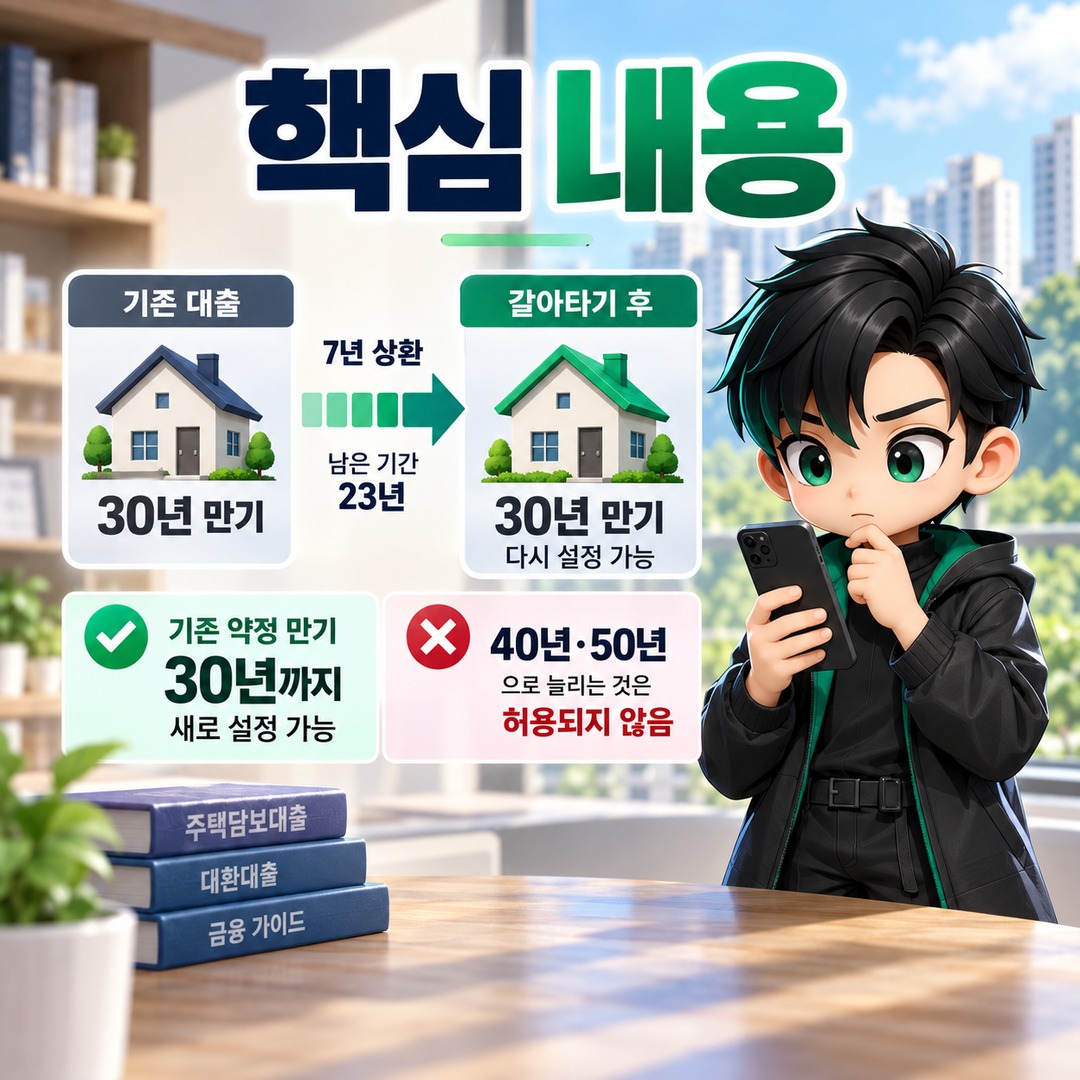
If you originally took out a mortgage with a 30-year term and have been repaying it for 7 years, must you choose only the remaining 23 years when refinancing? Under the Financial Services Commission's operating rules for its online loan refinancing service, you can set a new repayment term of up to 30 years, matching the original contractual term. However, extending the term to 40 years or 50 years is not permitted, and the actual approved term depends on the bank's assessment and applicable lending regulations.
When comparing mortgage interest rates, it is easy to overlook the repayment period. Even if your interest rate falls, the term you choose can significantly affect both your monthly payments and your total interest costs.
*Information verified as of: 2026-10-09 / Residential mortgage loans in South Korea*
1. Can You Refinance Back to a 30-Year Term After Repaying 7 Years of a 30-Year Mortgage?
The refinancing framework allows this. Under the online apartment mortgage refinancing plan announced by the Financial Services Commission on January 2024, the maturity of a new loan is limited to the original contractual term of the existing loan.
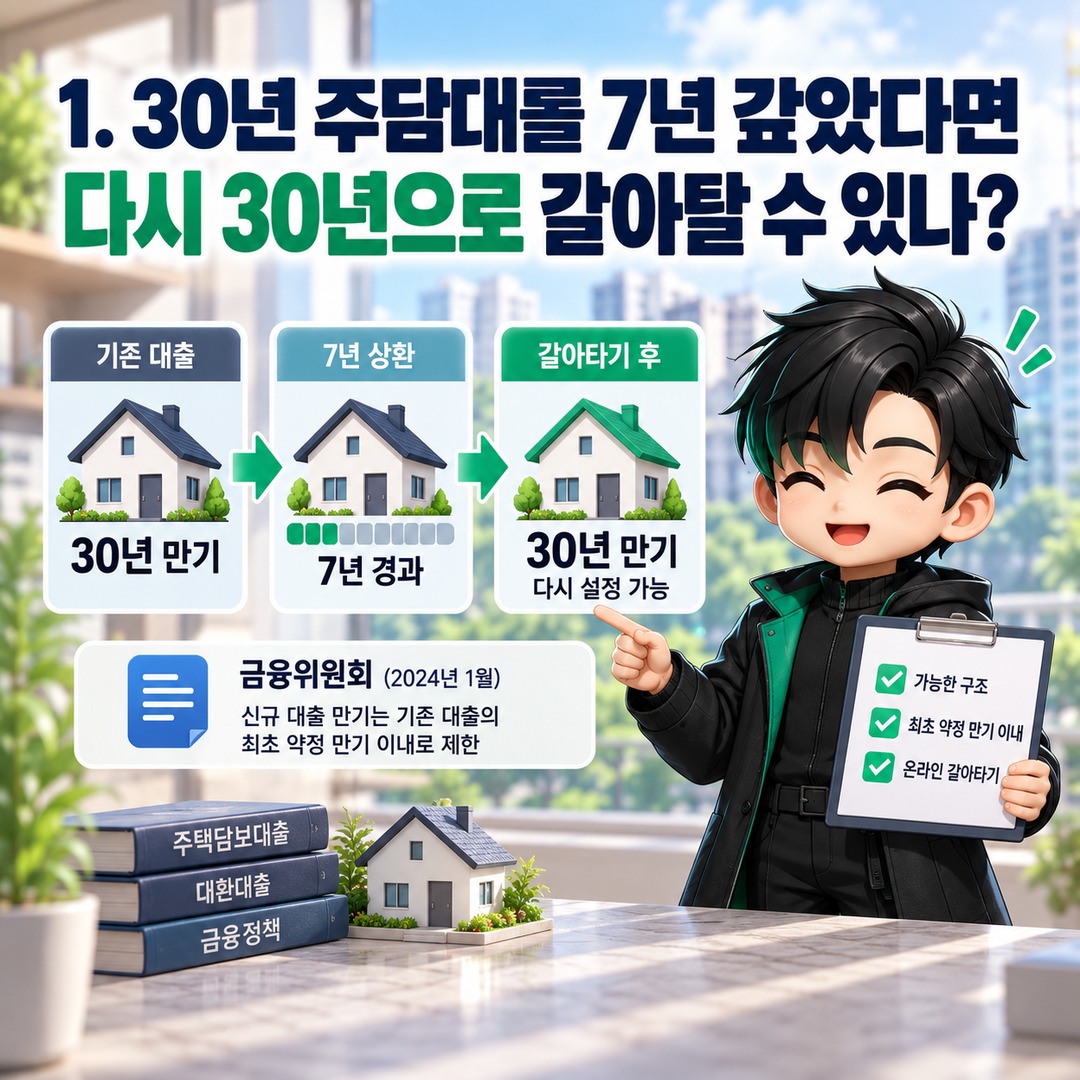
The Financial Services Commission itself provided an example involving a 30-year mortgage that had already been repaid for 7 years.
| Category | Period |
|---|---|
| Original contractual mortgage term | 30 years |
| Repayment period already completed | 7 years |
| Remaining term of the existing mortgage | 23 years |
| Maximum term available when refinancing | 30 years |
| Extension to 40 or 50 years | Not permitted |
There is an important distinction here.
The remaining 23-year repayment period and a newly established 30-year repayment term are two different concepts.
If you keep the existing mortgage, you continue repaying principal and interest over 23 years. If you refinance into a new mortgage with a 30-year term, the repayment schedule starts again from the new loan's disbursement date and extends over 30 years.
However, this explanation concerns the operating rules of the online loan refinancing infrastructure. It does not mean that every mortgage product will approve a 30-year term.
Actual eligibility depends on the borrower's age, income, repayment capacity, collateral conditions, product-specific maturity limits, and regulations in effect when the application is submitted.
Official source: Financial Services Commission: Operating Plan for Mortgage and Jeonse Loan Refinancing Services
2. How Much Can Monthly Payments Decrease If You Extend the Repayment Term Back to 30 Years?
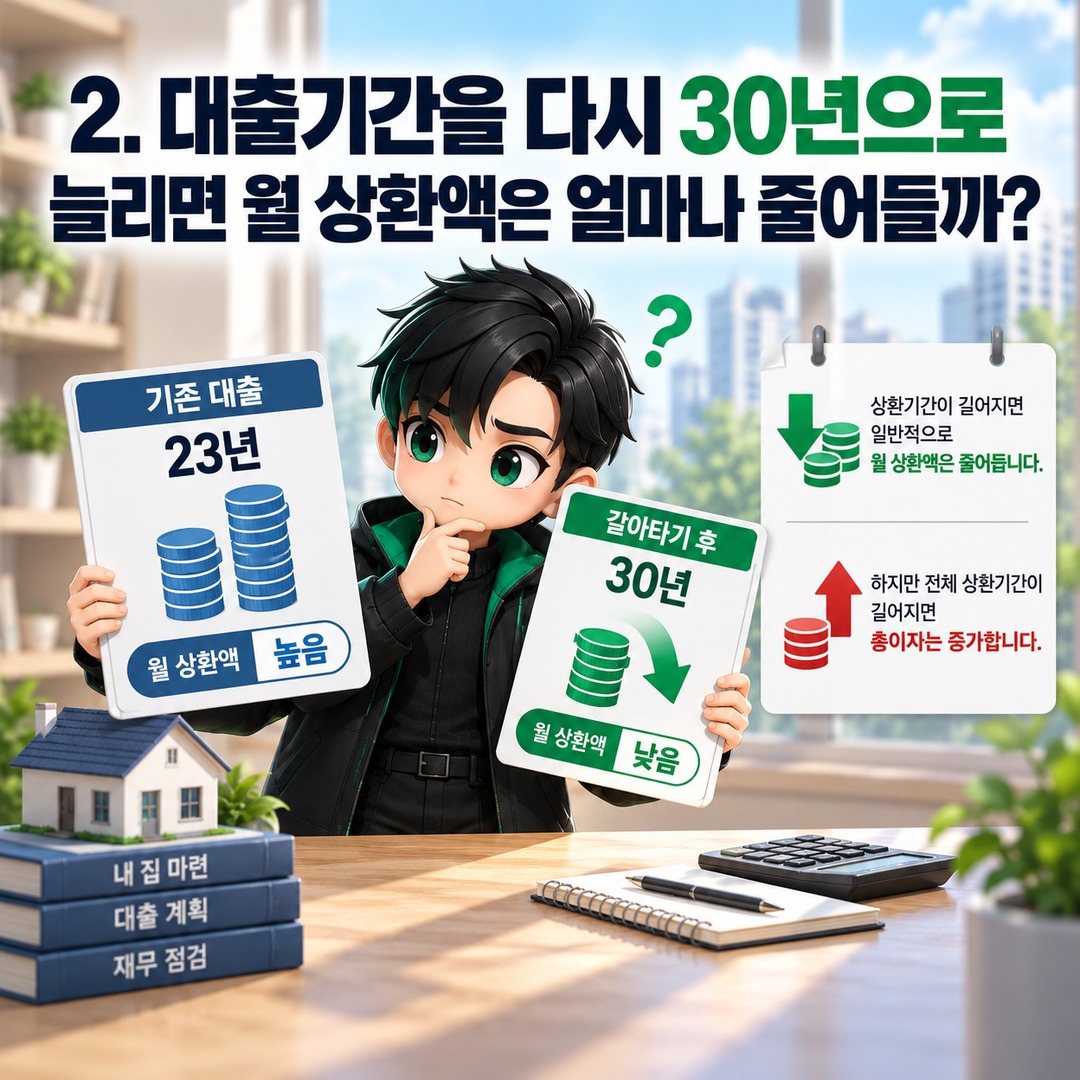
Extending the repayment period generally reduces monthly payments. However, even with the same interest rate and loan principal, a longer repayment period increases the total interest paid.
The following is a hypothetical calculation to illustrate the difference.
Calculation assumptions
Outstanding loan balance to refinance: KRW 300,000,000
New loan interest rate: 4.0% per year
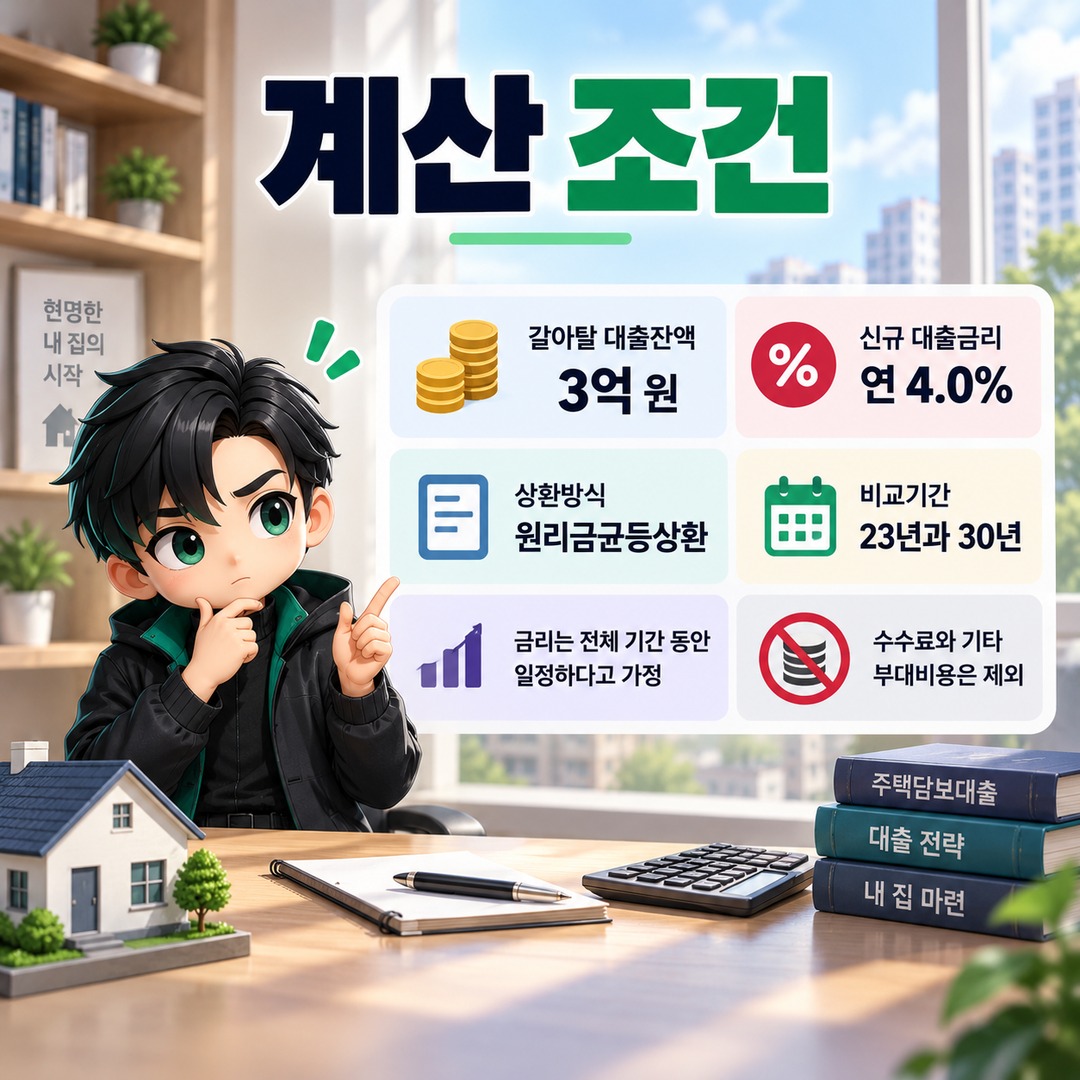
Repayment method: Equal monthly payments of principal and interest
Comparison periods: 23 years and 30 years
The interest rate is assumed to remain constant throughout the entire repayment period
Fees and other incidental expenses are excluded
| Category | 23-Year Repayment | 30-Year Repayment |
|---|---|---|
| Monthly payment | Approximately KRW 1,665,000.0 | Approximately KRW 1,432,000.0 |
| Total future interest payments | Approximately KRW 159,610,000 | Approximately KRW 215,610,000 |
| Total repayment period | 276 months | 360 months |
Author's calculations using the equal principal-and-interest repayment formula. Figures are calculated in won and rounded. Actual bank repayment schedules may differ.
Even when borrowing the same KRW 300,000,000 at an annual interest rate of 4%, choosing a 30-year repayment term reduces the monthly payment by approximately KRW 230,000.
On the other hand, total future interest costs increase by approximately KRW 56,000,000.
A 30-year term is more favorable for reducing monthly repayment pressure, while a 23-year term is more favorable for minimizing total interest expenses.
Importantly, the comparison above examines different repayment terms using the same new interest rate and loan principal. To determine whether refinancing actually saves money, you must separately account for the interest rate and remaining repayment period of your existing mortgage.
3. Extending the Repayment Term Is Different From Increasing the Loan Amount
Being allowed to extend your mortgage term does not mean you can borrow additional money.
The Financial Services Commission established a rule limiting the amount of a new mortgage obtained through the online refinancing service to the outstanding balance of the existing mortgage.
For example:
| Situation | Online Refinancing Rule |
|---|---|
| Refinancing an existing balance of KRW 300,000,000 with a new loan of KRW 300,000,000 | Subject to eligibility assessment |
| Refinancing an existing balance of KRW 300,000,000 with an increased loan amount of 3 hundred million 5 thousand won | Not permitted |
| Resetting an original 30-year contractual term to a new 30-year term | Subject to eligibility assessment |
| Extending an original 30-year contractual term to a new 40-year term | Not permitted |
In other words, refinancing an existing outstanding balance must be distinguished from taking out a new loan to obtain additional funds.
Furthermore, a longer repayment period does not guarantee that the borrower will pass the debt service ratio (DSR) assessment.
Banks review applicants' income, existing debts, applicable stress DSR requirements, and product conditions. Even if the calculated monthly payment decreases, the maximum term permitted during underwriting may be shorter.
4. Why a 30-Year Term May Not Be Available in Your Banking App
Even if your original contractual mortgage term was 30 years, your banking app may not offer a 30-year option.
Common reasons include:
Product-specific maturity limits: The new bank's mortgage product may have a shorter maximum repayment term.
Borrower age and repayment capacity: The bank's underwriting criteria may restrict the available repayment period.
Collateral conditions: The type of property or the results of its collateral valuation may affect product eligibility.
Lending regulations: Rules applying to the region, loan purpose, or borrower circumstances at the time of application may restrict the loan term.
Existing loan type: Government-supported mortgage products and other policy mortgages may follow different refinancing procedures from ordinary bank mortgages.
In particular, borrowers should not confuse the rules governing the online refinancing infrastructure with the conditions for new secured loans offered separately through bank branches.
If your preferred term does not appear in the app, it is worth asking the bank the following specific question:
"My existing mortgage had an original contractual term of 30 years, and its remaining term is currently 23 years. Could you confirm whether I can select a 30-year term when applying through the online refinancing service? If not, please clarify whether the restriction comes from the mortgage product's conditions or lending regulations."
This type of inquiry can help you identify the precise reason for the restriction rather than simply receiving a notice that your loan application was rejected.
5. 5 Things to Check Before Applying for Mortgage Refinancing
If you plan to reset your repayment period, do not make your decision based solely on the interest rate comparison screen.
[ ] Check the original contractual term and current remaining term of your existing mortgage
[ ] Confirm the maximum repayment term the new bank can approve
[ ] Compare monthly payments and total interest for 23-year and 30-year terms
[ ] Check early repayment penalties, stamp duty, and mortgage registration-related expenses
[ ] Confirm the interest rate application period and the conditions for maintaining preferential interest rates on the new loan
You should also compare the existing and new loans using the same repayment method. Equal principal-and-interest payments and equal principal repayments produce different patterns of monthly payments.
If the new loan's interest rate is fixed for 5 years, you should not assume that the same rate will apply throughout the entire 30-year repayment period.
When comparing actual borrowing costs, the bank's repayment schedule and contractual loan terms should serve as the final reference.
6. Frequently Asked Questions
Q. If I Have Already Repaid 10 Years of a Mortgage Originally Taken Out for 30 Years, Can I Refinance Into Another 30-Year Term?
Under the original contractual maturity rule governing online refinancing, the framework allows a new term of up to 30 years. However, the permitted period may be shorter depending on the regulations applicable at the time of application and the bank's underwriting decision.
Q. Can I Refinance a Mortgage Originally Taken Out for 40 Years Into a 30-Year Mortgage?
Changing to a shorter 30-year term is consistent with the rule restricting new loan maturities to the original contractual term. Whether the refinancing can actually proceed depends on the new bank's product conditions and underwriting assessment.
Q. Does Extending the Mortgage Term Eliminate Early Repayment Penalties?
No. An early repayment penalty incurred when paying off an existing mortgage ahead of schedule is separate from the repayment period of the new loan. You must check the existing loan agreement and the conditions for any penalty exemption.
Q. Is Refinancing Always Beneficial if Monthly Payments Decrease?
Not necessarily. Monthly payments may decrease while total interest expenses increase because of the longer repayment period. You should also consider how many years you plan to keep the mortgage.
7. Conclusion: Being Able to Reset the Term to 30 Years Does Not Necessarily Make It the Best Choice
If you originally took out a mortgage with a 30-year term and have already repaid it for 7 years, the Financial Services Commission's online refinancing operating rules allow you to establish a new repayment term of up to 30 years.
However, extending the term does not automatically mean saving on interest.
In the hypothetical example of repaying KRW 300,000,000 at an annual interest rate of 4%, choosing 30 years instead of 23 years reduces monthly payments by approximately KRW 230,000 but increases total interest costs by approximately KRW 56,000,000.
Therefore, when deciding whether to refinance your mortgage, you should compare not only the new interest rate but also the new repayment term, monthly payments, total interest costs, and additional expenses.
The best choice may differ between households prioritizing monthly cash flow and those seeking to minimize total interest costs.
---
Financial Services Commission: Launch of the Apartment Mortgage Refinancing Service (2024.1.8.)
KB Kookmin Bank: Real Estate Secured Loan Products and Additional Costs
This article references publicly available information as of 2026-10-09. The basic rules concerning loan maturities are based on official Financial Services Commission guidance. Borrowers should confirm their individually approved repayment terms and applicable regulations with their financial institution at the time of application.