

Fixed Deposit Rates of 3.5% vs. 3.7%: After-Tax Interest Difference on 1 Thousand Won Deposited for 1 Year Is KRW 16,920
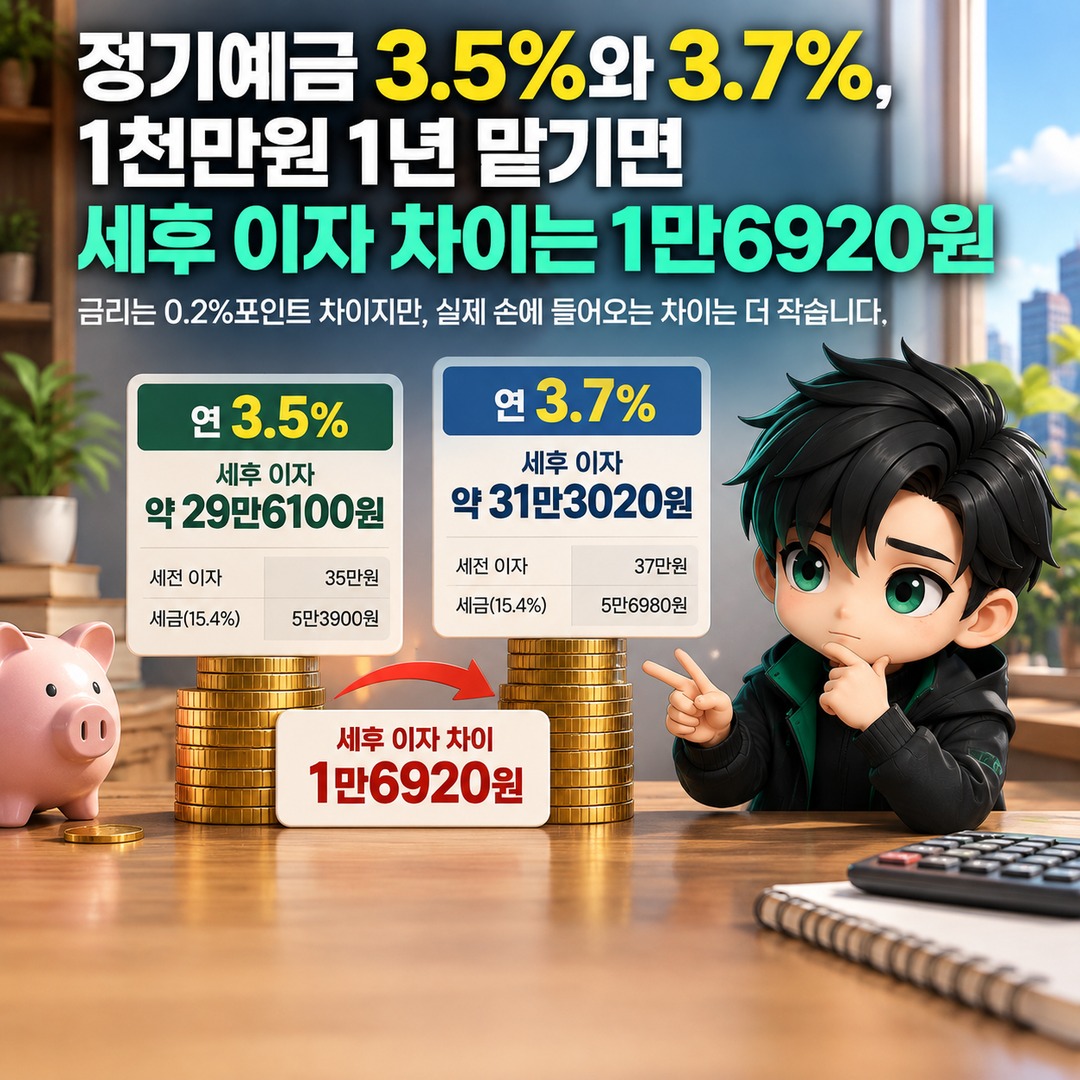
Assuming 1 thousand won is placed in a fixed deposit for 1 year, an annual rate of 3.5% produces approximately KRW 296,100 in after-tax interest, while an annual rate of 3.7% produces approximately KRW 313,020. After applying the standard tax rate of 15.4%, the difference is KRW 16,920. Although the interest rates differ by 0.2% percentage points, the actual difference received is smaller than the pre-tax difference of KRW 20,000.
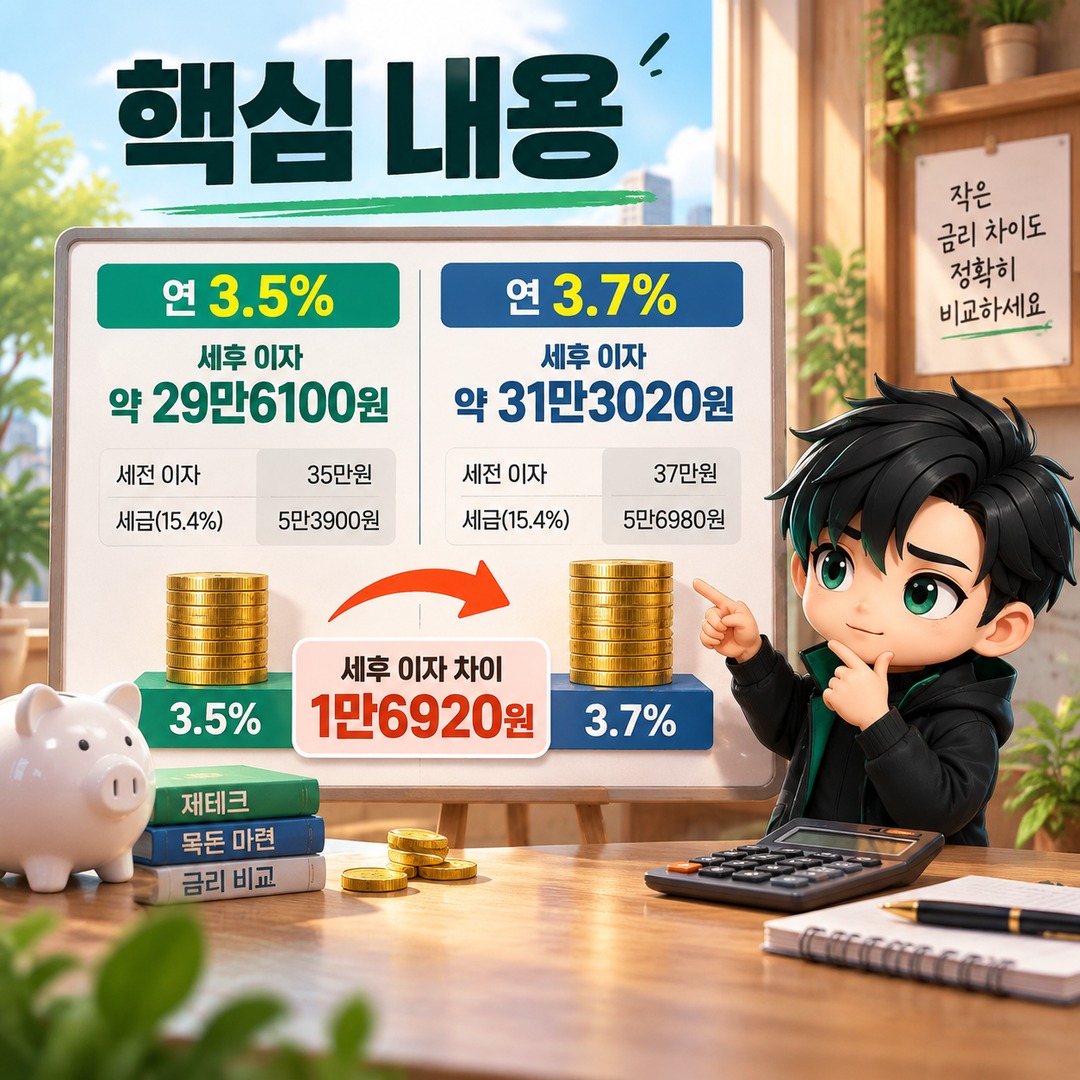
A 0.2%-Percentage-Point Rate Difference Means Exactly KRW 20,000 Before Tax
The calculation is straightforward. Simply assume that 1 thousand won remains deposited for 12 months and calculate the interest using a simple annual interest rate.
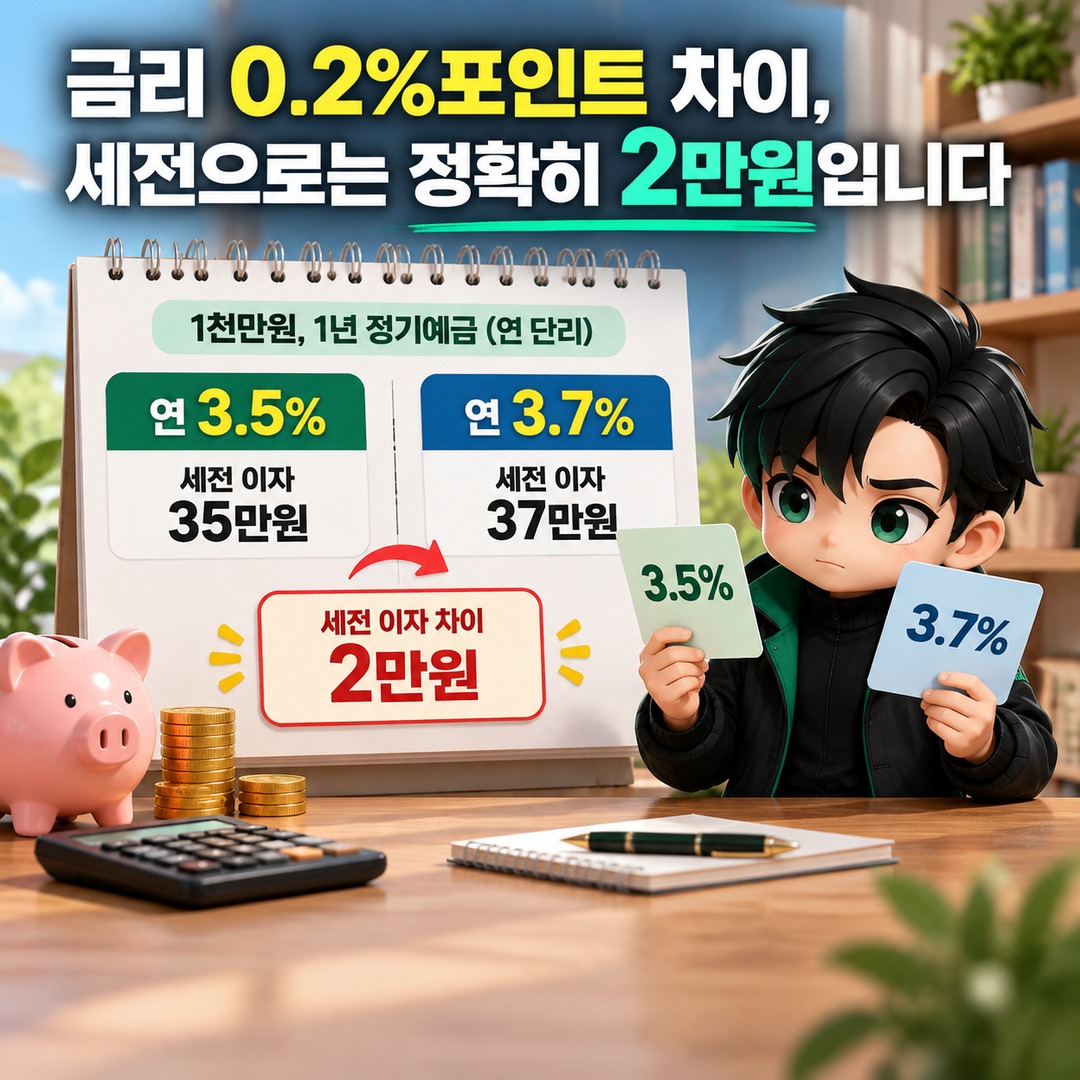
At an annual rate of 3.5%, the pre-tax interest is KRW 10,000,000 × 3.5% = KRW 350,000.
At an annual rate of 3.7%, the pre-tax interest is KRW 10,000,000 × 3.7% = KRW 370,000.
Therefore, the pre-tax difference is KRW 20,000 over 1 year.
An important distinction is that the difference between 3.7% and 3.5% is not 0.2% in relative terms, but 0.2% percentage points. Applying a 0.2%-percentage-point difference to a principal of 1 thousand won produces KRW 20,000 over 1 year.
After Tax, 3.5% Yields KRW 296,100 and 3.7% Yields KRW 313,020
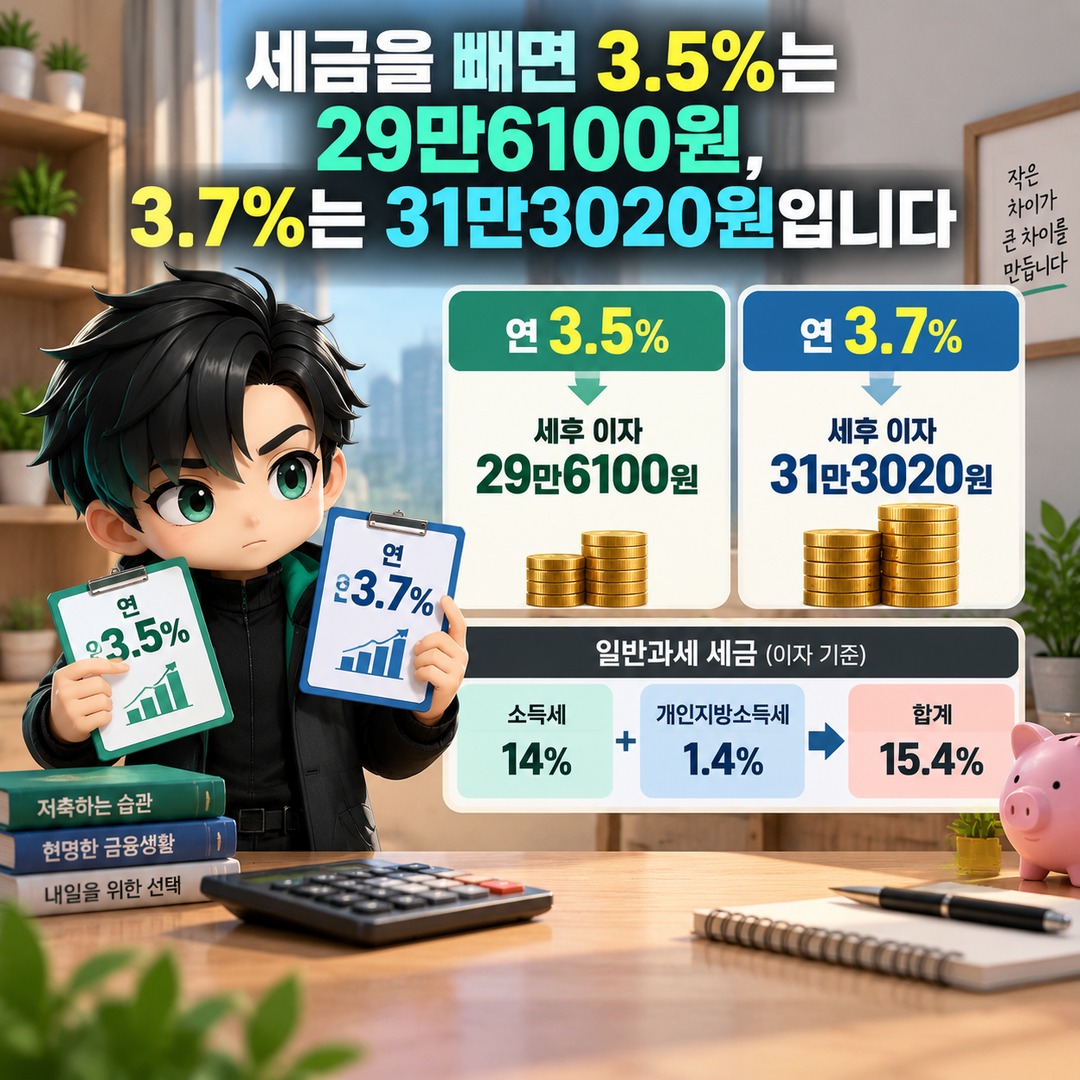
Ordinary deposit interest is subject to withholding income tax at 14%, plus local income tax equal to 10% of the withheld income tax. Expressed as a percentage of the interest earned, the combined standard tax burden is 15.4%.
At an annual rate of 3.5%, deducting KRW 53,900 from the pre-tax interest of KRW 350,000 leaves KRW 296,100 in after-tax interest.
At an annual rate of 3.7%, deducting KRW 56,980 from the pre-tax interest of KRW 370,000 leaves KRW 313,020 in after-tax interest.
According to the author's calculations, the difference in after-tax interest between the two products over 1 year is as follows.
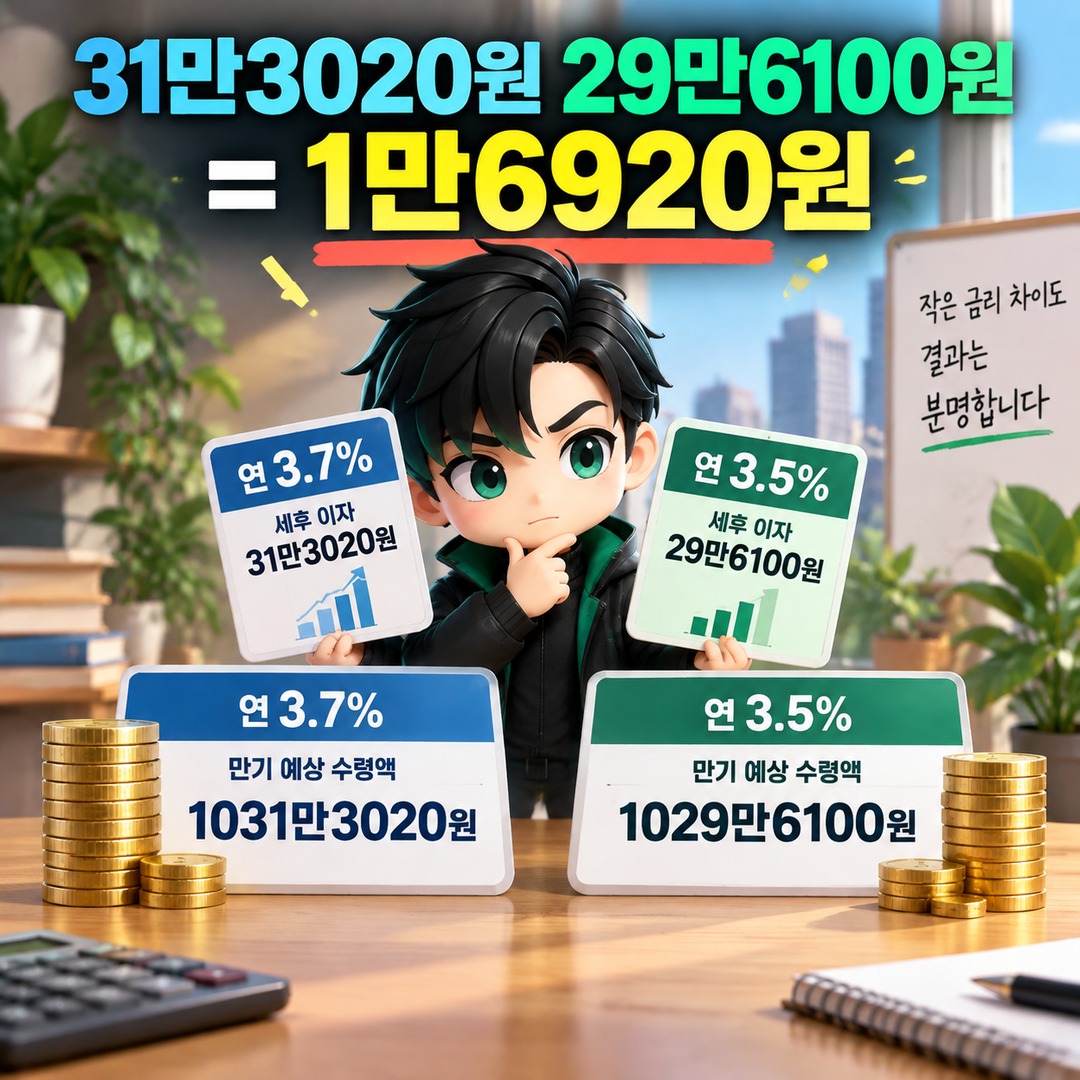
KRW 313,020 - KRW 296,100 = KRW 16,920
Expressed as the expected total amount received at maturity, the annual rate of 3.5% results in KRW 10,296,100, while the annual rate of 3.7% results in KRW 10,313,020.
As the Principal Increases, the Impact of a 0.2%-Percentage-Point Difference Also Grows
Under the same 12-month deposit term and standard taxation conditions, the after-tax interest difference resulting from a rate gap is almost proportional to the principal.
While the difference is KRW 16,920 for 1 thousand won, the author's calculations show a difference of approximately KRW 84,600 for 5 thousand won and approximately KRW 169,200 for KRW 100,000,000.
Therefore, when depositing 1 thousand won, it is advisable to consider the account's terms and conditions rather than choosing a financial institution solely because of a 0.2%-percentage-point rate difference. Conversely, as the deposit amount increases, the monetary impact of the same interest rate difference also grows.
Fixed Deposits Offering Rates in the Mid-3% Range Are Also Available as of September 2026
According to information retrieved on 2026-09-26, Woori Bank's WON Plus Deposit lists a pre-tax annual contractual interest rate of 3.50% for a 12-month term.
It was also reported on September 22 that KakaoBank's 1-year fixed deposit rate would increase to an annual 3.7% starting 2026-09-23. However, the official KakaoBank product page reviewed during this verification still showed September 11 as its interest rate reference date, displaying an annual rate of 3.60% for terms of at least 12 months but less than 24 months.
Therefore, although the interest calculations for 3.5% and 3.7% can be compared using the assumptions above, anyone planning to open an account should reconfirm whether the 3.7% rate actually applies by checking the financial institution's latest product information immediately before subscribing.
Why Comparing Interest Rate Figures Alone Can Be Misleading
When comparing deposit rates, first check whether the deposit terms are identical. Even if both products advertise an annual rate of 3.7%, a 6-month product and a 12-month product will generate different amounts of interest.
It is also important to distinguish between a maximum rate that includes preferential interest and a basic rate available without additional requirements. If the deposit is withdrawn early, the originally agreed maturity rate may not apply.
This calculation assumes a principal of 1 thousand won, a 12-month deposit term, annual rates of 3.5% and 3.7%, standard taxation, and a simple comparison of annual interest rates. Actual interest received at maturity may differ slightly depending on the product's interest calculation method, subscription and maturity dates, and tax treatment.
In addition, starting 2025-09-01, the deposit protection limit was increased to KRW 100,000,000 per person, per financial institution, including both principal and interest. As the deposit amount grows, it becomes increasingly important to check not only the interest rate but also whether the product qualifies for deposit insurance and how much eligible money is already held at the same financial institution.
For a deposit of 1 thousand won over 1 year, the answer is straightforward. Increasing the annual rate from 3.5% to 3.7%, a difference of 0.2% percentage points, increases pre-tax interest by KRW 20,000, while the actual after-tax interest difference under standard taxation is KRW 16,920. This difference should be weighed alongside account-opening convenience, early withdrawal terms, and preferential interest rate requirements.
※ This article is provided for informational purposes to help readers understand market trends and does not constitute an investment recommendation for any particular security or asset. Readers are responsible for their own final decisions and investment outcomes.
Related Articles
Gold Prices Rebound to 4,347 Dollars: Two Things to Check Now at September 16