

Can You Qualify for Jeonse Deposit Insurance After Removing a Mortgage Lien? Same-Day Cancellation and Verification
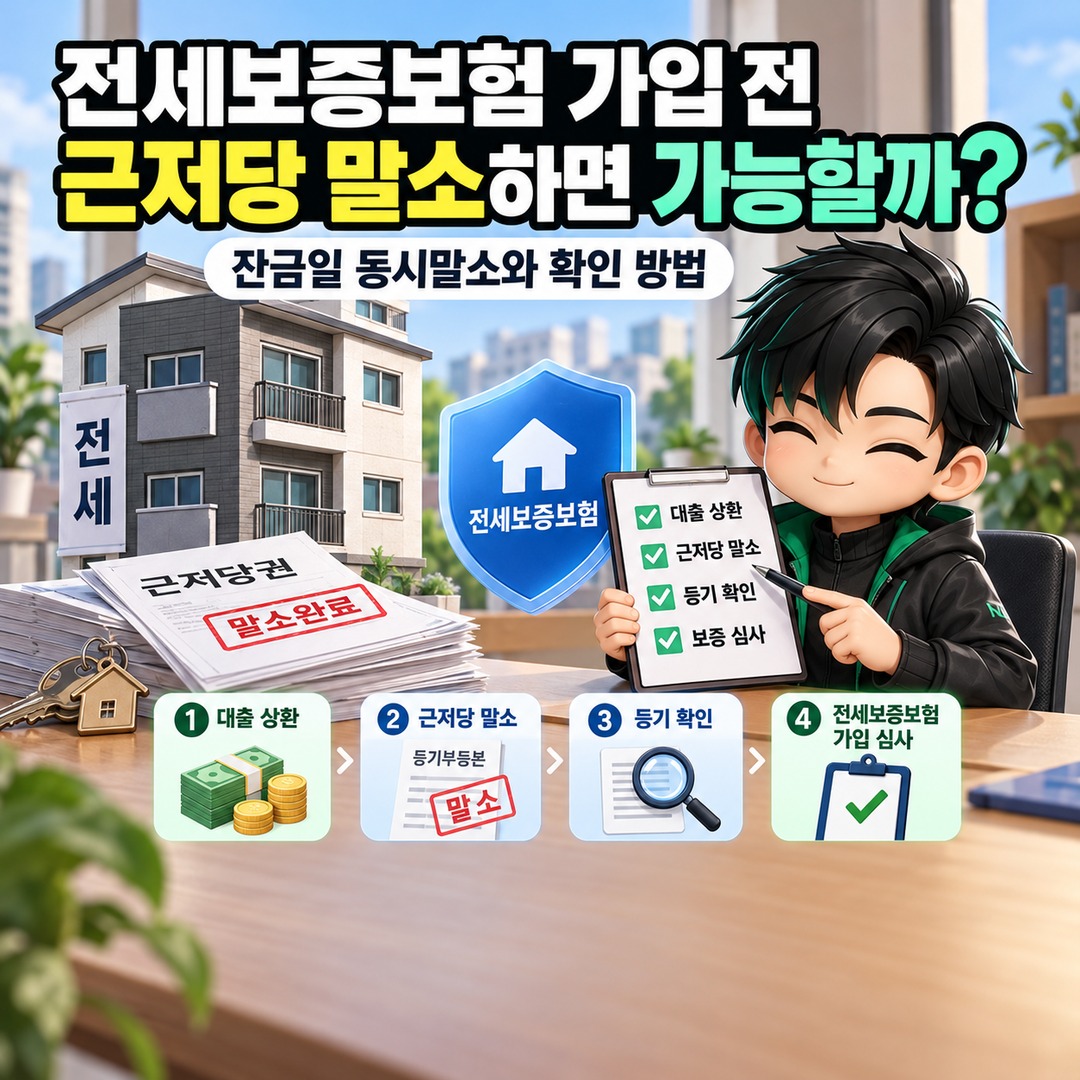
Even if a villa you plan to rent under a Korean jeonse lease has an existing mortgage lien, you may become eligible for jeonse deposit return insurance if the existing loan is repaid and the mortgage lien is fully canceled on the final payment date. However, the landlord's promise to repay the loan is not enough. You must verify that the cancellation has actually been completed and that the property meets the guarantee provider's underwriting requirements.
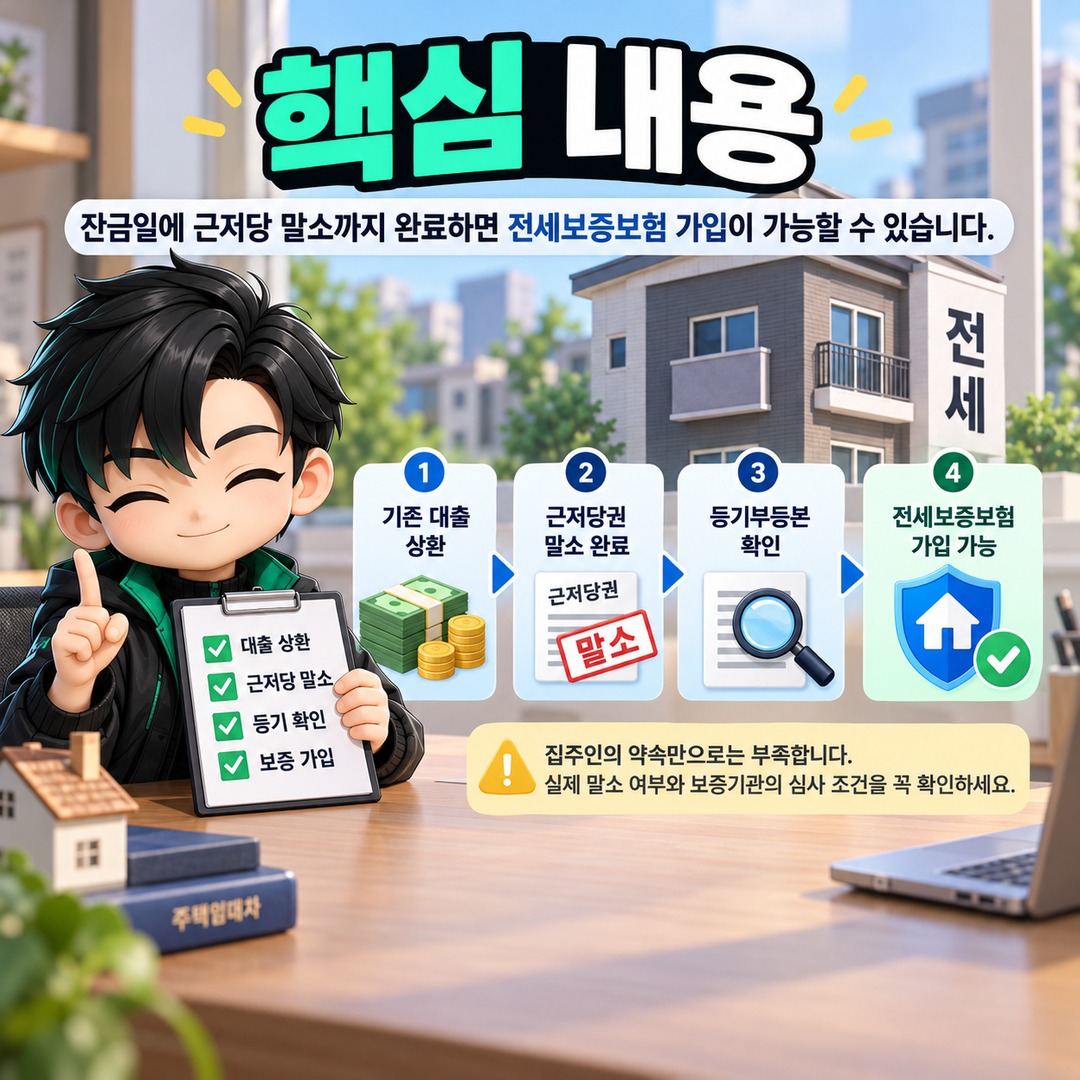
If the landlord intends to repay an existing loan using the tenant's jeonse deposit, the order of final payment and verification of the property registry is particularly important.
*Verification 기준: 2026-10-14 / Korea Housing & Urban Guarantee Corporation (HUG) Jeonse Deposit Return Guarantee requirements*
1. Does an Existing Mortgage Lien Automatically Make a Property Ineligible for Jeonse Deposit Insurance?
No. Even if a property has a registered mortgage lien, it may qualify if the combined amount of senior claims and the jeonse deposit meets the guarantee provider's requirements.
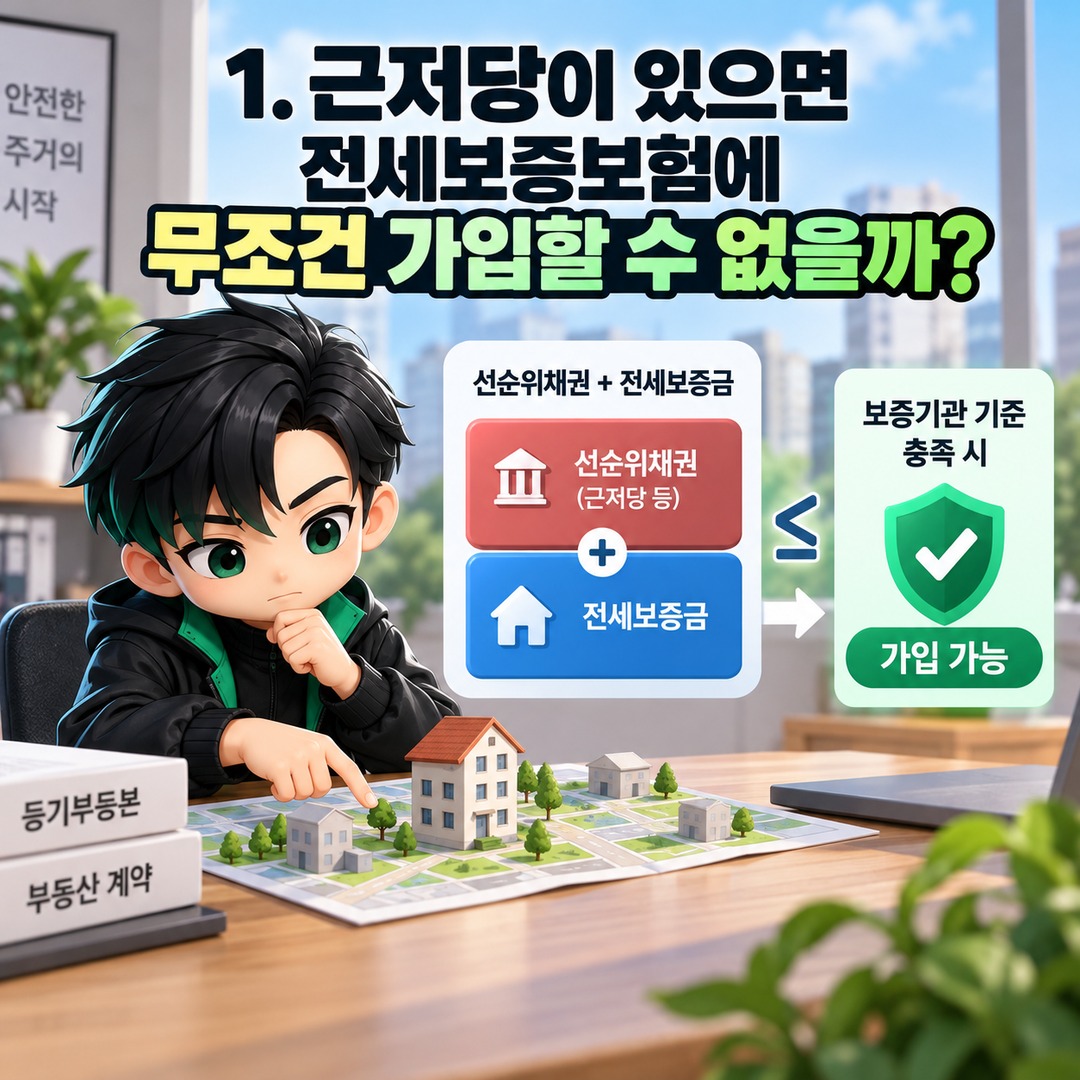
The basic calculation for HUG's Jeonse Deposit Return Guarantee is as follows.
Guarantee Limit = Property Value × 90% - Senior Claims and Other Deductions
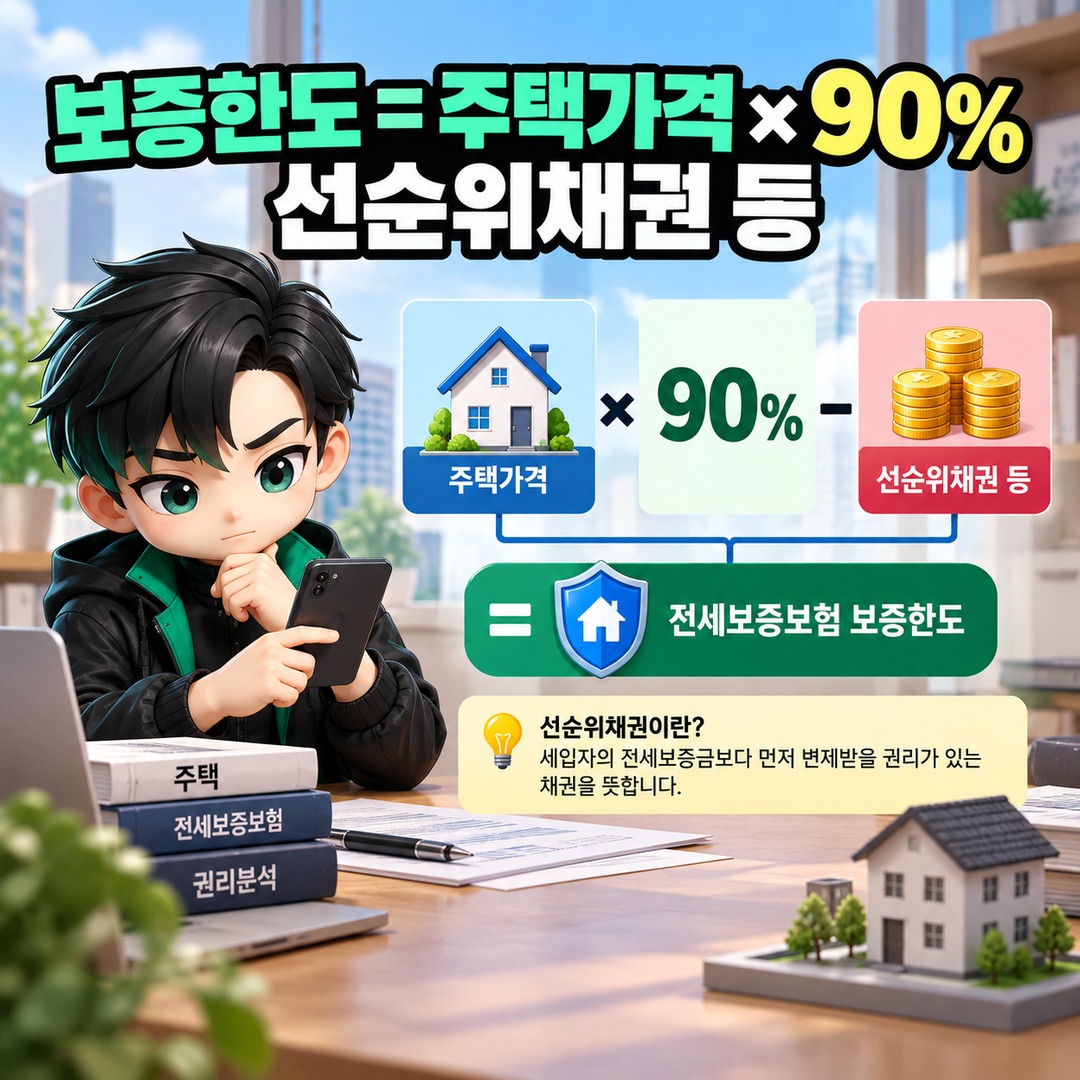
Senior claims are claims that have priority over the tenant's jeonse deposit when repayment is made.
For a property with a registered mortgage lien, you should check the maximum secured claim amount and registration date recorded in Section Eul of the complete real estate registration certificate.
HUG also imposes a separate requirement that senior claims must not exceed 60% of the property's assessed value.
Therefore, meeting the property-price requirement for the jeonse deposit does not automatically guarantee eligibility.
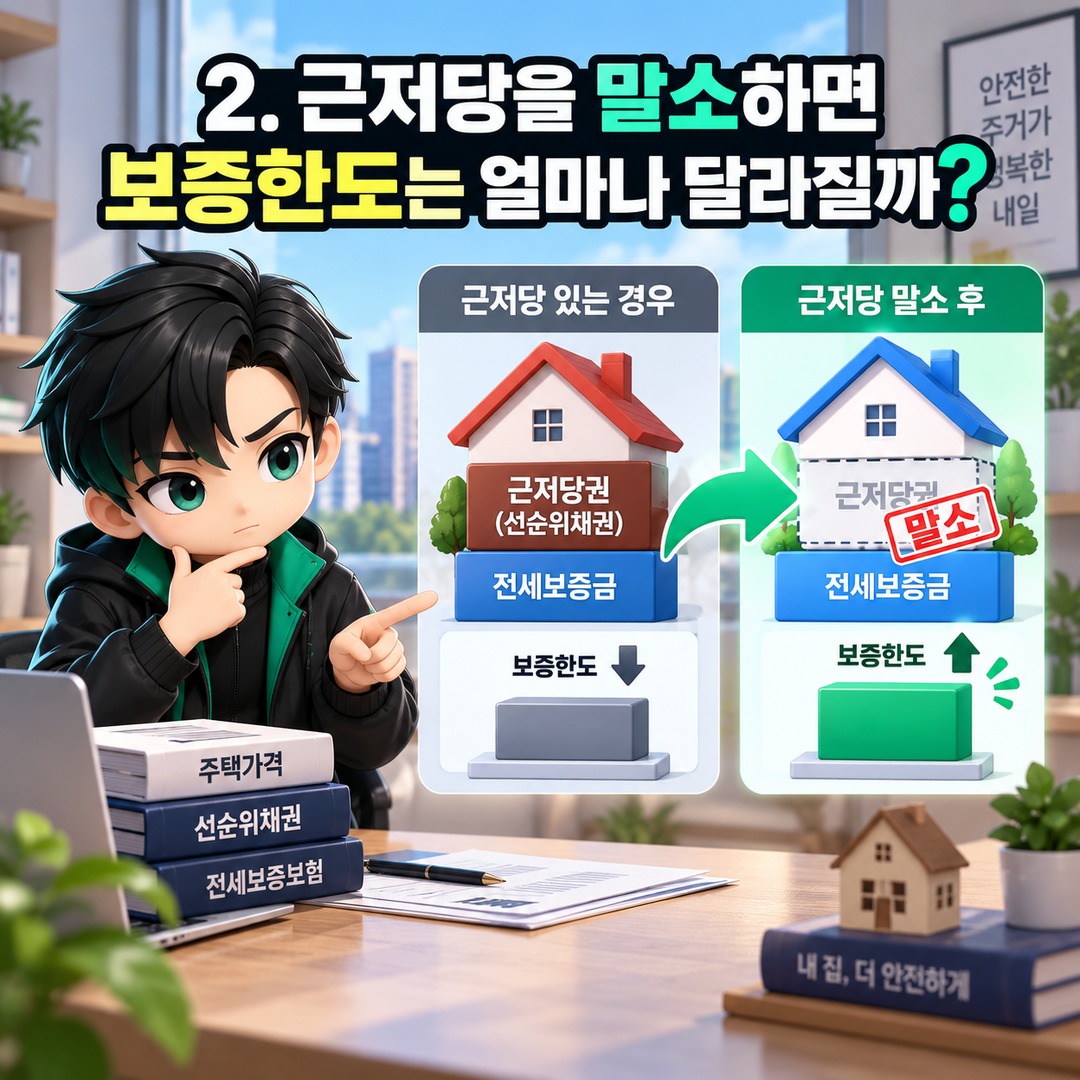
2. How Much Can the Guarantee Limit Increase After a Mortgage Lien Is Canceled?
If the mortgage lien is legally canceled and the associated senior claim is eliminated, the guarantee limit may increase accordingly.
Consider a multi-unit residential property with an officially assessed price of KRW 200,000,000.
Assume HUG recognizes the property's value at 140% of its officially assessed price.
Officially assessed price of the condominium-type residential unit: KRW 200,000,000
Property value recognized by HUG: KRW 280,000,000
Collateral recognition ratio: 90%
Calculated property value for guarantee purposes: KRW 252,000,000
Jeonse deposit: KRW 220,000,000
Maximum secured claim amount under the existing mortgage lien: KRW 50,000,000
Under these assumptions, the figures before and after cancellation are as follows.
| Category | Before Cancellation | After Cancellation |
|---|---|---|
| Property value for guarantee purposes | KRW 252,000,000 | KRW 252,000,000 |
| Senior mortgage claim | KRW 50,000,000 | KRW 0 |
| Calculated guarantee limit | KRW 202,000,000 | KRW 252,000,000 |
| Jeonse deposit | KRW 220,000,000 | KRW 220,000,000 |
| Meets the monetary requirement | No | Potentially |
*Author's calculation. This example assumes there are no senior claims other than the mortgage lien and that all other eligibility requirements are satisfied.*
Before cancellation, the calculated guarantee limit falls short of the jeonse deposit by KRW 18,000,000.
Once the mortgage lien is fully canceled, the calculated guarantee limit increases by KRW 50,000,000.
This demonstrates why mortgage lien cancellation can be a decisive factor in determining eligibility for jeonse deposit insurance.
However, HUG's actual underwriting process also considers the recognized property value, other senior rights, the building register, and the lease terms.
3. Can a Mortgage Lien Be Canceled on the Same Day as the Final Jeonse Payment?
Yes. A transaction can be arranged so that the existing mortgage loan is repaid and the mortgage lien is canceled on the final payment date.
However, the moment the tenant transfers the final payment and the moment the mortgage lien cancellation becomes visible in the property registry may differ.
You should therefore avoid proceeding solely on the landlord's statement that the mortgage lien is scheduled to be canceled on the final payment date.
The general verification sequence is as follows.
1. Before signing: Check the mortgage lien holder and maximum secured claim amount in the complete real estate registration certificate.
2. Before final payment: Confirm the actual repayment amount required and the cancellation procedure with the financial institution holding the existing loan.
3. On the final payment date: Verify that repayment and the application for cancellation registration are proceeding as agreed.
4. After the cancellation application: Check whether the registration application has been received and its processing status.
5. After cancellation is completed: Obtain an updated complete real estate registration certificate and verify that the mortgage lien has actually been removed.
It is particularly important to distinguish between the acceptance of an application for cancellation registration and the completion of the cancellation itself.
For safety, confirm in advance with the guarantee provider which documents must be submitted and by what deadline during the jeonse deposit insurance application process.
4. How Should a Mortgage Lien Cancellation Clause Be Written in a Jeonse Lease Agreement?
If the lease is conditional on mortgage lien cancellation, the agreement should clearly specify the obligation to cancel the lien, the deadline, and the consequences of noncompliance.
For example, the following matters may be considered.
These are examples for review, not standardized contractual provisions guaranteed to have the same legal effect in every agreement.
The actual lease should further clarify the following details.
Registration receipt number and maximum secured claim amount of the mortgage lien to be canceled
Party responsible for repaying the existing loan
Deadline for completing mortgage lien cancellation
How the final payment is coordinated with the loan repayment procedure
Conditions governing final payment, contract termination, and repayment of funds if cancellation is delayed or not completed
A contractual clause does not automatically cancel a mortgage lien.
A Special Contract Clause Documents a Promise; the Actual Legal Status of the Property Must Be Verified Through Its Registration Records.
The legal consequences of paying a contract deposit or final balance may vary depending on the specific contractual terms. Professional review may therefore be advisable.
5. What If the Landlord Says the Loan Has Been Repaid but the Mortgage Lien Still Appears in the Registry?
Repaying a loan and canceling a registered mortgage lien are two separate matters.
Even if the landlord has fully repaid the loan, the tenant must separately verify the cancellation status if the mortgage lien remains on the property registry.
Three stages should be distinguished.
| Status | What to Verify |
|---|---|
| Loan repayment completed | Repayment confirmation documents issued by the financial institution |
| Cancellation registration applied for | Whether the registration application has been officially received |
| Cancellation registration completed | Updated complete real estate registration certificate |
A repayment confirmation issued by the financial institution alone should not be treated as proof that the mortgage lien has been removed from the registry.
During guarantee underwriting, HUG checks senior claims and registered encumbrances affecting the property.
If cancellation has not been completed, explain the current registration status to the guarantee provider and confirm whether the application can be assessed.
6. Can Jeonse Deposit Insurance Still Be Denied After the Mortgage Lien Is Canceled?
Yes. Mortgage lien cancellation resolves only one of several eligibility requirements. It does not automatically satisfy every condition.
The following issues may still prevent approval.
First, the Jeonse Deposit Exceeds the Guarantee Limit.
Even without a mortgage lien, enrollment may be difficult if the jeonse deposit itself exceeds the property value recognized by HUG for guarantee purposes.
Second, Other Registered Encumbrances Affect the Property.
Attachments, provisional attachments, auction applications, or other issues recorded in Section Gap of the property registry may affect separate underwriting requirements.
Third, the Building Is Recorded as an Unauthorized or Noncompliant Structure.
For residential properties other than apartments, HUG checks whether the building register identifies the property as a structure that violates building regulations.
Fourth, Additional Requirements Apply to the Property Type.
It is important to distinguish between *dasedae* housing and *dagagu* housing under South Korea's residential property classifications.
Dasedae housing generally allows separate ownership registration for individual residential units. For dagagu housing, however, it may be necessary to examine the rights affecting the entire building and the deposits held by other tenants.
Therefore, the same requirements should not automatically be applied to every property simply because it is described as a villa.
7. How to Check Whether Mortgage Lien Cancellation Is Feasible Before Signing a Lease
If you are preparing to sign a jeonse lease, consider following this verification process.
① Obtain the Complete Real Estate Registration Certificate
Check the latest complete real estate registration certificate through the Supreme Court of Korea's Internet Registry Office.
Supreme Court Internet Registry Office
Section Gap contains ownership information and encumbrances such as attachments. Section Eul contains registered rights such as mortgage liens and jeonse rights.
② Check the Officially Assessed Property Price
Look up the property's officially assessed condominium-type residential property price through the Ministry of Land, Infrastructure and Transport's Real Estate Public Price Information Service.
Real Estate Public Price Information Service
However, the property value used in the actual guarantee assessment may differ depending on HUG's order of applying property valuation information and its recognition standards.
③ Verify the Mortgage Repayment and Cancellation Schedule
Ask the landlord to explain the repayment plan for the existing loan and the procedure for canceling the mortgage lien.
Check whether the repayment amount, scheduled repayment date, and party responsible for handling cancellation registration have been clearly determined.
④ Confirm HUG's Eligibility Requirements
Review the Korea Housing & Urban Guarantee Corporation's official Jeonse Deposit Return Guarantee product information, including property valuation, senior claims, and lease conditions.
Official HUG Jeonse Deposit Return Guarantee Information
If the agreement requires the mortgage lien to be canceled on the final payment date, contact HUG or the participating financial institution in advance to confirm the application timing and document submission requirements.
8. Frequently Asked Questions
Q. If the Registered Maximum Secured Claim Is KRW 100,000,000 but the Actual Outstanding Loan Is KRW 70,000,000, Which Amount Should Be Used?
HUG instructs applicants to check the mortgage amount and registration date recorded in Section Eul of the property registry.
Therefore, the senior claim should not automatically be calculated as KRW 70,000,000 solely because the landlord says the actual outstanding loan balance is KRW 70,000,000.
If the lien has been canceled or its registered amount reduced, verify the supporting documents and whether the change will be recognized during underwriting.
Q. Can I Obtain Jeonse Deposit Insurance If the Mortgage Lien Cancellation Application Is Merely Filed on the Final Payment Date?
Submitting the cancellation application alone does not guarantee eligibility.
The required supporting documents may vary depending on the registration processing status and application date. Confirm the requirements in advance with HUG or the participating institution.
Q. Will My Entire Jeonse Deposit Be Protected Once the Mortgage Lien Is Canceled?
Canceling the mortgage lien alone does not guarantee full coverage.
You must pass the guarantee provider's underwriting process and check the guaranteed amount stated on the issued guarantee certificate. Actual payment under the guarantee is also subject to the policy terms and claim requirements.
Conclusion: Completed Mortgage Lien Cancellation Matters More Than a Promise to Cancel
In a jeonse lease, what matters more than the mere existence of a mortgage lien is how much senior debt remains after the transaction and whether the promised cancellation is actually completed.
If you sign a lease conditional on mortgage lien cancellation, separately verify the contractual clause, loan repayment, cancellation registration, and jeonse deposit insurance underwriting process.
Before transferring the final payment, confirm the cancellation procedure in detail. Afterward, obtain the latest complete real estate registration certificate to verify the actual outcome.
---
Official References
Korea Housing & Urban Guarantee Corporation — Jeonse Deposit Return Guarantee Product Overview
Supreme Court Internet Registry Office
Ministry of Land, Infrastructure and Transport — Real Estate Public Price Information Service