

Villa Jeonse Deposit Insurance: A Mortgage Changes Eligibility Even Below 126% of the Official Property Value
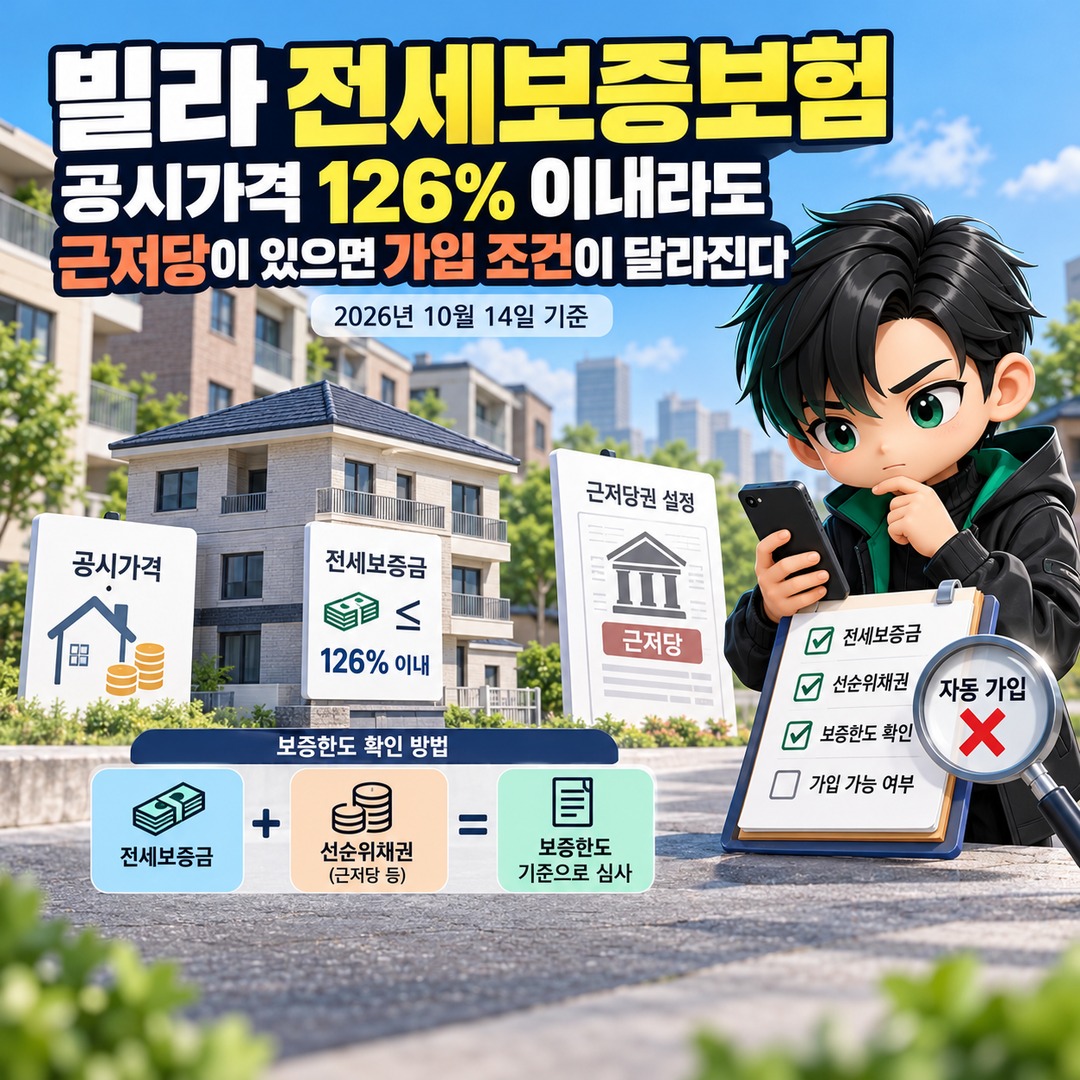
Even if the jeonse deposit for a villa is within 126% of its officially assessed property value, having a registered mortgage does not automatically qualify the property for deposit insurance. Under the 2026-10-14 criteria, the deposit and senior-priority claims must be added together to determine whether they fall within the guarantee limit. However, a registered mortgage does not automatically disqualify every property.
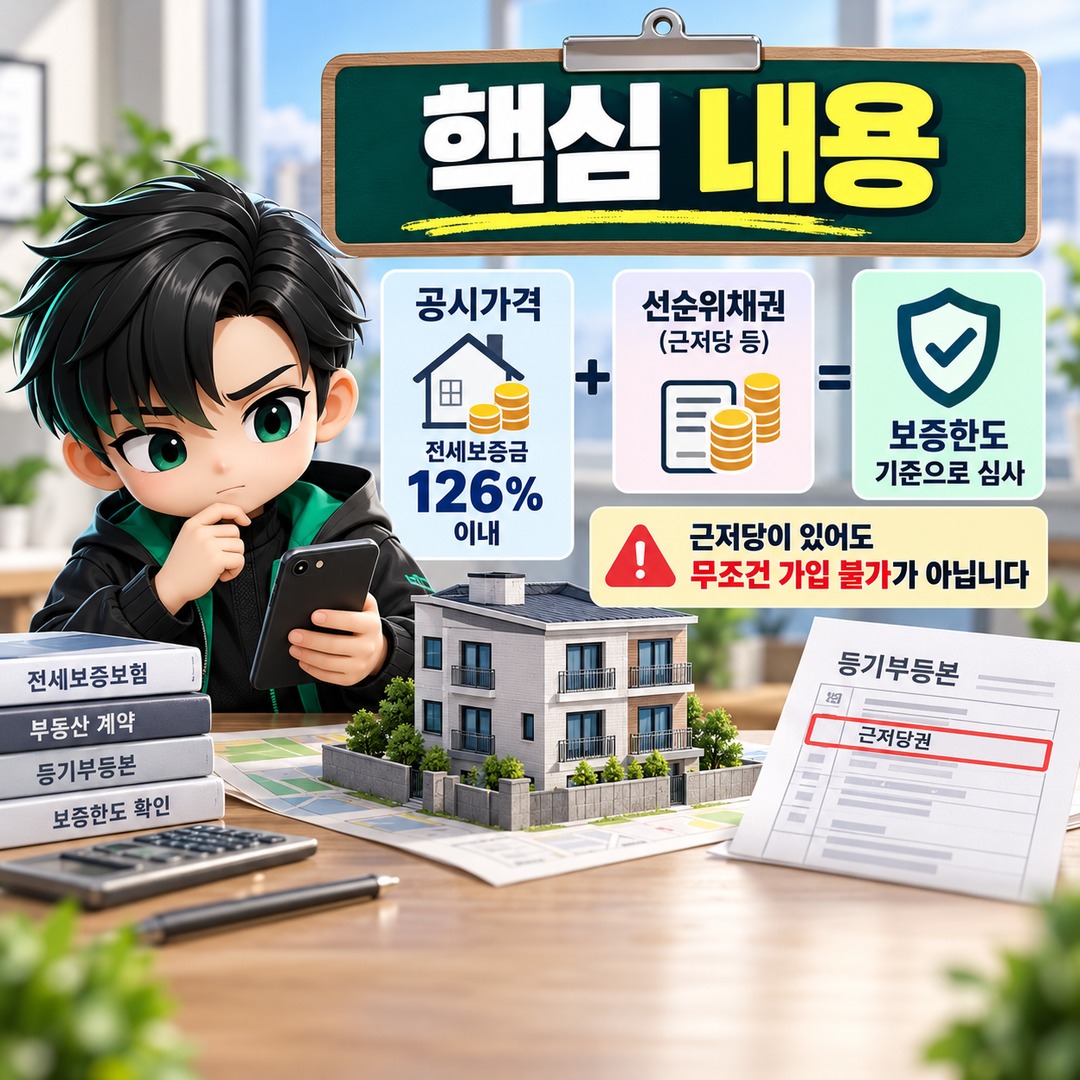
In villa lease agreements, the calculation can produce different results depending on whether only the jeonse deposit is considered or the registered mortgage's maximum secured claim amount is also included.
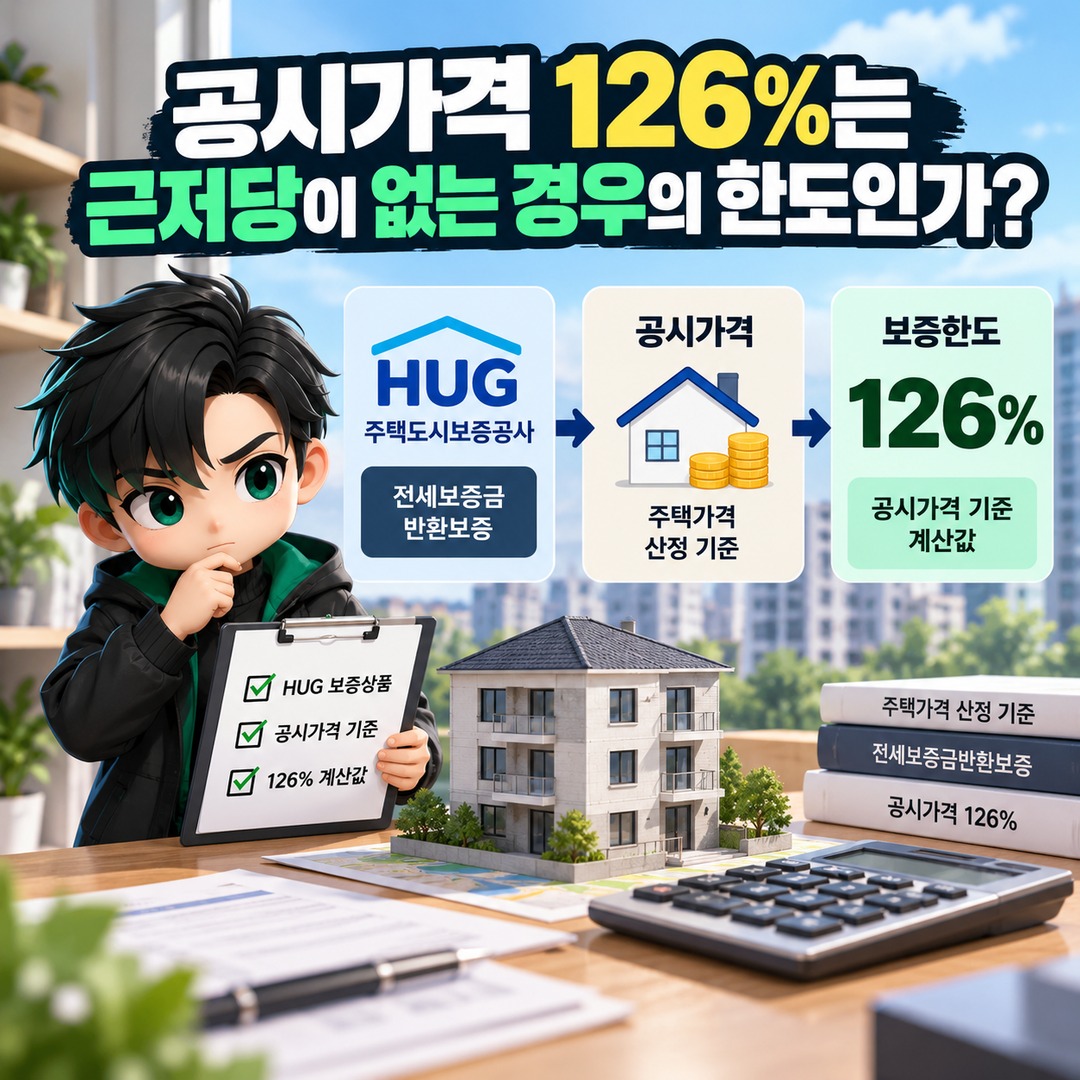
Does 126% of the Official Property Value Represent the Limit When There Is No Mortgage?
The 126% figure is derived from the calculation used by the Korea Housing & Urban Guarantee Corporation (HUG) for its Jeonse Deposit Return Guarantee when the officially assessed property value is used to determine the property's value.
When 140% of the officially assessed value is recognized as the property value and the collateral recognition ratio of 90% is applied, the calculation is as follows.
Official Property Value × 140% × 90% = Official Property Value × 126%
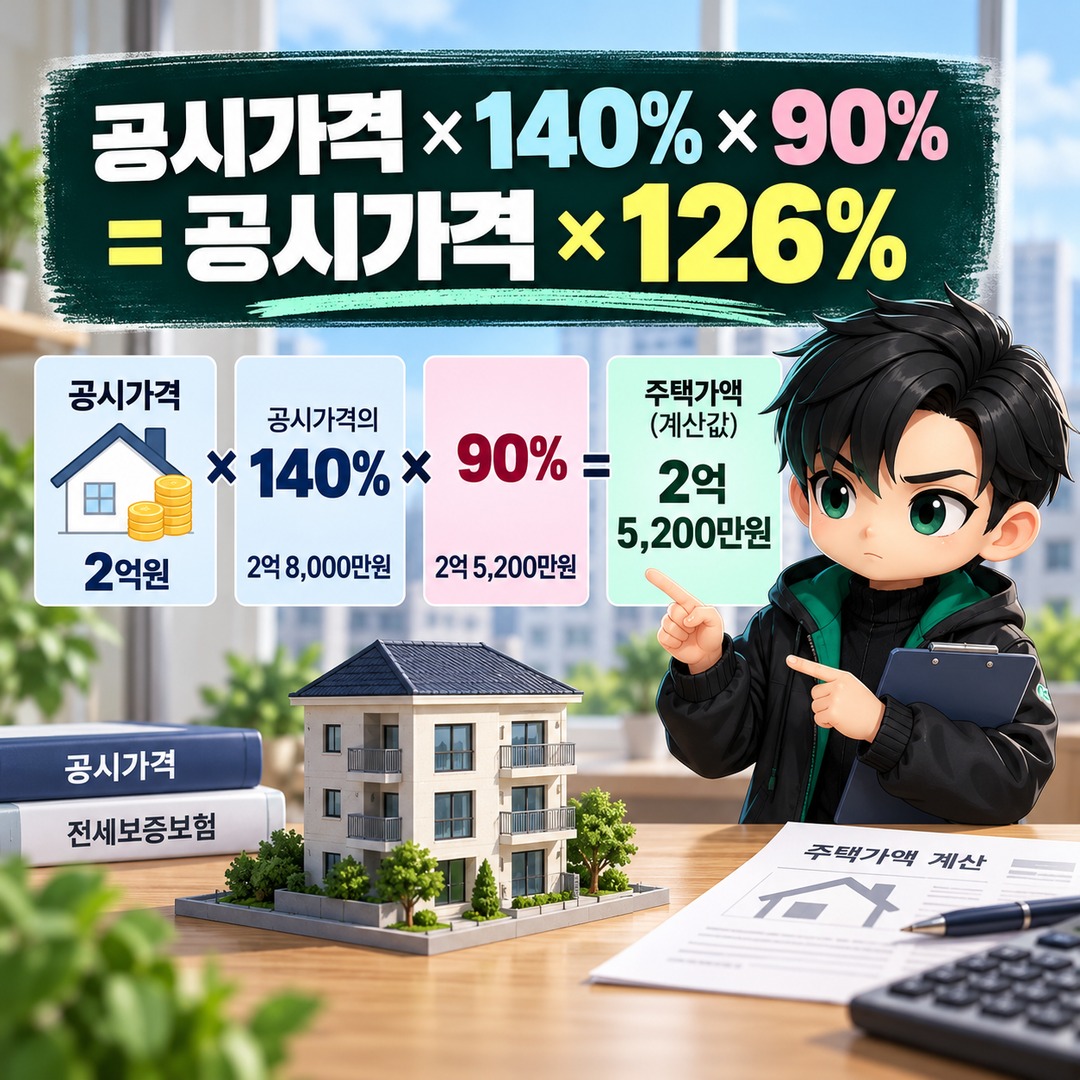
For example, if a villa has an officially assessed multi-unit residential property value of KRW 200,000,000, its calculated property value is KRW 252,000,000.
However, this does not mean that the amount is the actual guarantee limit for every villa. The eligible amount varies depending on the property valuation method accepted by the guarantee institution and the existence of senior-priority claims.
For a villa without a mortgage, a jeonse deposit of KRW 252,000,000 may satisfy the monetary requirement. For a villa with a mortgage, however, the available guarantee limit is reduced accordingly.
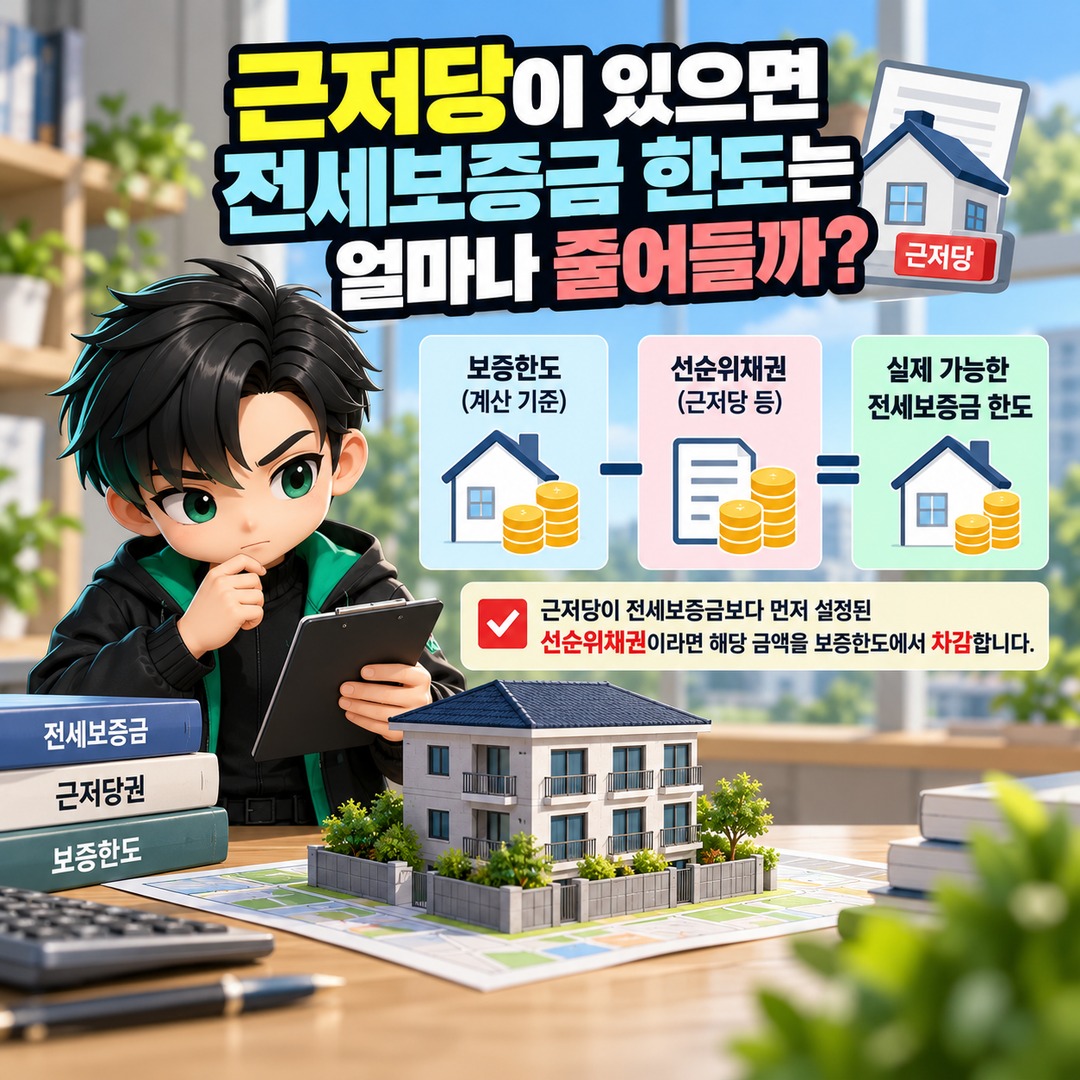
How Much Does a Mortgage Reduce the Maximum Eligible Jeonse Deposit?
If a mortgage was registered before the jeonse deposit and therefore constitutes a senior-priority claim, its amount must be deducted when calculating the guarantee limit.
HUG's basic guarantee limit calculation is structured as follows.
Guarantee Limit = Property Value × 90% − Senior-Priority Claims and Other Applicable Amounts
For a villa whose recognized property value is 140% of its officially assessed value, the guarantee limit can be calculated by deducting senior-priority claims from the amount equivalent to 126% of the official property value.
Consider a villa with an officially assessed property value of KRW 200,000,000.
| Registered Senior-Priority Mortgage Amount | Calculated Maximum Jeonse Deposit |
|---|---|
| None | KRW 252,000,000 |
| KRW 30,000,000 | KRW 222,000,000 |
| KRW 50,000,000 | KRW 202,000,000 |
| KRW 80,000,000 | KRW 172,000,000 |
These figures are simplified calculations assuming there are no other senior-priority claims and that 140% of the official property value is accepted as the recognized property value. They do not represent confirmed insurance eligibility amounts.
For example, if the jeonse deposit is KRW 230,000,000 and the registered senior-priority mortgage amount is KRW 30,000,000, the combined amount is KRW 260,000,000.
This exceeds the calculated property value of KRW 252,000,000 by KRW 8,000,000.
In this example, the jeonse deposit itself is within 126% of the official property value, but the property fails to meet the guarantee limit requirement once the senior-priority mortgage is included.
Does a Small Mortgage Automatically Mean the Property Qualifies?
Even when the mortgage amount is small, separate restrictions on senior-priority claims must be checked in addition to the overall guarantee limit calculation.
In its standard deposit return guarantee assessment, HUG also checks whether senior-priority claims are within 60% of the property's value. Separate requirements apply to detached houses, multi-household houses, and multi-occupancy houses, including consideration of deposits held by other tenants.
For example, if the property value is KRW 252,000,000, 60% of that value is KRW 151,200,000.
However, satisfying the requirement that senior-priority claims do not exceed KRW 151,200,000 does not, by itself, establish eligibility.
The combined jeonse deposit and senior-priority claims must also remain within the property's value. The registered ownership and security interests, as well as the lease terms, are reviewed together.
Therefore, the senior-priority claim ratio restriction and the combined deposit guarantee limit must be checked as separate requirements.
Should You Check the Outstanding Mortgage Loan Balance or the Maximum Secured Claim Amount?
If a mortgage is registered against a villa, you must check not only the actual outstanding loan balance but also the maximum secured claim amount recorded in the property register.
The maximum secured claim amount is the maximum amount of debt that a financial institution secures through the registered mortgage.
For example, even if the landlord's actual outstanding loan balance is KRW 40,000,000, the maximum secured claim amount recorded in the property register may be KRW 48,000,000.
If the guarantee assessment uses the registered senior-priority mortgage amount, you should not calculate eligibility simply by deducting the outstanding loan balance of KRW 40,000,000 reported by the landlord.
Even if the landlord has partially repaid the loan, the registered mortgage amount may remain unchanged.
For this reason, before signing the lease, it is important to check the mortgage amount and registration date in Section B of the complete certified property registration record.
Can Removing the Mortgage Make Jeonse Deposit Insurance Available?
If removing the registered mortgage reduces senior-priority claims, the property's eligibility under the guarantee limit requirement may change. However, removing the mortgage alone does not satisfy every insurance requirement.
Suppose a villa has an officially assessed property value of KRW 200,000,000, a jeonse deposit of KRW 230,000,000, and a registered senior-priority mortgage of KRW 30,000,000.
If the mortgage remains in place, the combined jeonse deposit and senior-priority claims amount to KRW 260,000,000.
If the mortgage is completely discharged and no other senior-priority claims exist, the combined amount falls to the jeonse deposit of KRW 230,000,000.
In this case, the amount falls within the calculated property value of KRW 252,000,000 based on the official assessment.
However, actual eligibility is determined only after reviewing additional factors, including the accepted property valuation method, the tenant's legal enforceability against third parties and preferential repayment rights, and whether the property is subject to any adverse legal claims or restrictions.
Even if the landlord explains that the existing loan will be repaid using the final lease payment, a planned repayment must be distinguished from a completed mortgage discharge.
Do HUG and HF Apply the Same Mortgage Assessment Requirements?
Both HUG's Jeonse Deposit Return Guarantee and the Korea Housing Finance Corporation's (HF) General Jeonse Protection Guarantee consider senior-priority claims, but their product-specific eligibility requirements differ.
HF's General Jeonse Protection Guarantee calculates the guarantee limit by deducting the total senior-priority claims from 90% of the property value.
In addition, for properties other than detached and multi-household houses, including row houses and multi-unit residential buildings, the total senior-priority claims must generally be within 60% of the property's value. Separate criteria may apply to lease agreements signed before 2023-09-30.
Applicants for HF's General Jeonse Protection Guarantee must also satisfy the eligibility requirements for the guarantee beneficiary, such as already using an HF jeonse loan guarantee or applying for the deposit protection guarantee simultaneously with a jeonse loan guarantee.
Therefore, a calculation made under HUG's criteria should not be used unchanged to determine eligibility for HF's product.
What Should You Check Before Signing a Villa Lease?
To determine whether a villa is eligible for jeonse deposit insurance, do not compare only the officially assessed property value and the jeonse deposit. You must also examine the rights and security interests recorded against the property.
Follow this verification sequence.
1. Check the Officially Assessed Multi-Unit Residential Property Value: Verify the official assessed value for the specific unit you intend to lease.
2. Review the Complete Property Registration Record: Check the registered mortgage amount and registration date in Section B, and examine Section A for adverse claims or restrictions, including attachment and provisional attachment orders.
3. Calculate the Guarantee Limit: Use the property value accepted by the guarantee institution and the senior-priority claims to determine whether the jeonse deposit falls within the applicable limit.
4. Check the Building Register: Verify whether the property is classified as a building with violations and confirm its registered use.
5. Request a Preliminary Assessment From the Guarantee Institution: Confirm potential eligibility based on the actual lease terms and property registration documents.
It is particularly important to distinguish between multi-unit residential buildings and multi-household houses.
Multi-unit residential buildings generally have separately registered ownership for each individual unit. By contrast, a multi-household house is often registered as a single ownership unit covering the entire building, which may require checking the deposits of other tenants.
Even villas that look similar from the outside may be subject to different assessment requirements depending on their building register classification and property registration structure.
Is a Jeonse Lease Safe If the Deposit Is Below 126%?
A jeonse deposit cannot be considered safely protected solely because it falls within 126% of the officially assessed property value.
126% is a calculated guarantee limit based on a particular property valuation method. It does not guarantee the landlord's ability to return the deposit or the property's actual sale price.
Furthermore, being eligible to purchase deposit insurance and having successfully completed enrollment in the insurance are two different matters.
If the villa you intend to lease has a registered mortgage, do not stop at checking the ratio of the jeonse deposit to the official property value. You must also verify the guarantee limit after including senior-priority claims and examine the property's registered legal interests.
Under the October 2026 Criteria, the First Thing to Check When Considering Villa Jeonse Deposit Insurance Is the Actual Guarantee Limit Including Senior-Priority Mortgages, Rather Than Simply 126% of the Official Property Value.
Before signing the contract, prepare the official assessed value of the specific unit, the proposed jeonse deposit, and the mortgage amount recorded in the property register. It is advisable to request a preliminary eligibility assessment from the guarantee institution whose product you intend to use.