

How to Annualize the Bitcoin Futures Basis: Comparing Contracts with Different Expiration Dates
This post contains Coupang Partners affiliate links. We may earn a commission from qualifying purchases.
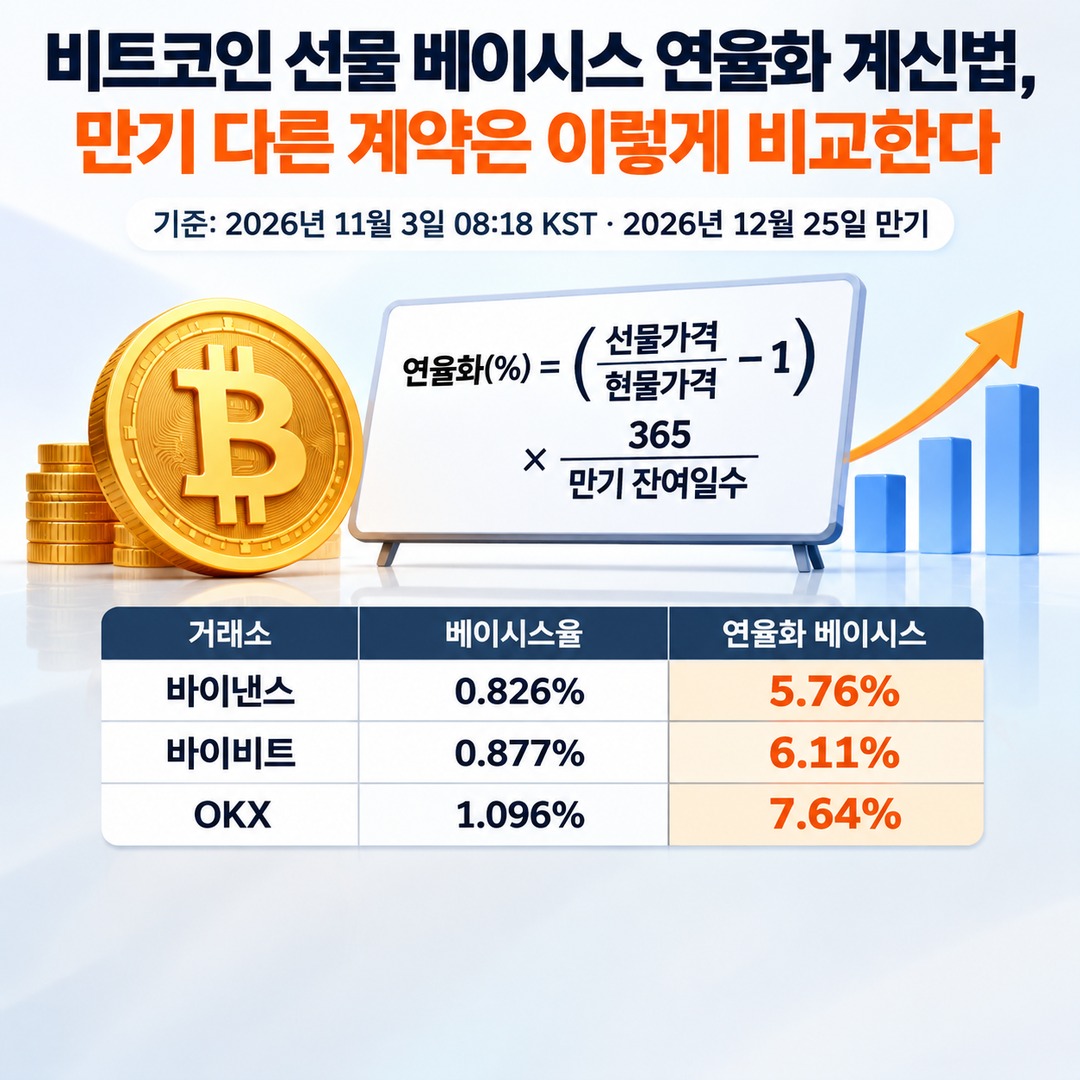
When money flows out of spot Bitcoin ETFs while futures open interest (OI) remains stable, it is worth examining whether the positions remaining in the futures market reflect bullish expectations or arbitrage strategies. An annualized futures basis is a useful indicator for this analysis. By measuring how much higher the futures price is than the spot price and accounting for the time remaining until expiration, you can calculate the annualized percentage represented by that difference.
1. What Does the Bitcoin Futures Basis Tell Us?
The basis is the difference between the spot price of Bitcoin and the price of a futures contract with a specified expiration date.
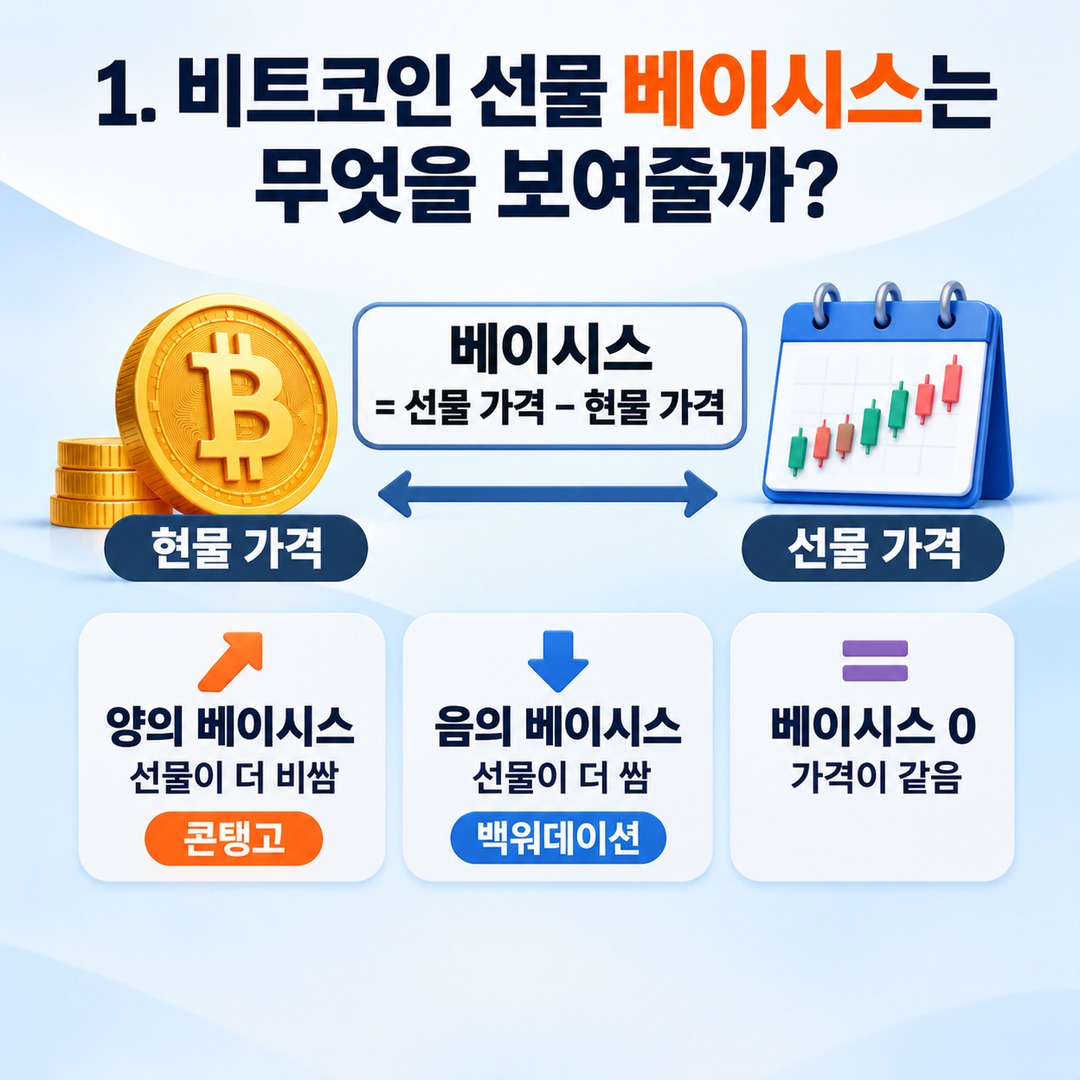
This article follows the same calculation method used by CME: subtracting the spot price from the futures price.
Positive basis: Futures are trading above spot.
Negative basis: Futures are trading below spot.
Zero basis 0: Futures and spot prices are equal.
A market structure in which futures trade above spot is called contango, while one in which futures trade below spot is called backwardation.
The important point is that higher futures prices do not necessarily mean that more investors are expecting the market to rise.
Futures prices reflect factors such as financing costs, time remaining until expiration, demand for leverage, and market sentiment.
CME Group also explains that the Bitcoin futures basis is influenced by financing costs and market sentiment, among other factors.
2. The Formula for Calculating the Annualized Basis
Looking only at the dollar difference in the basis makes it difficult to compare futures contracts with different expiration dates accurately.
For example, a price difference of 1% for a futures contract with 10 days remaining until expiration has a different time-based meaning from a price difference of 1% for a contract with 180 days remaining.
That is why the basis is annualized to account for the number of days remaining until expiration.
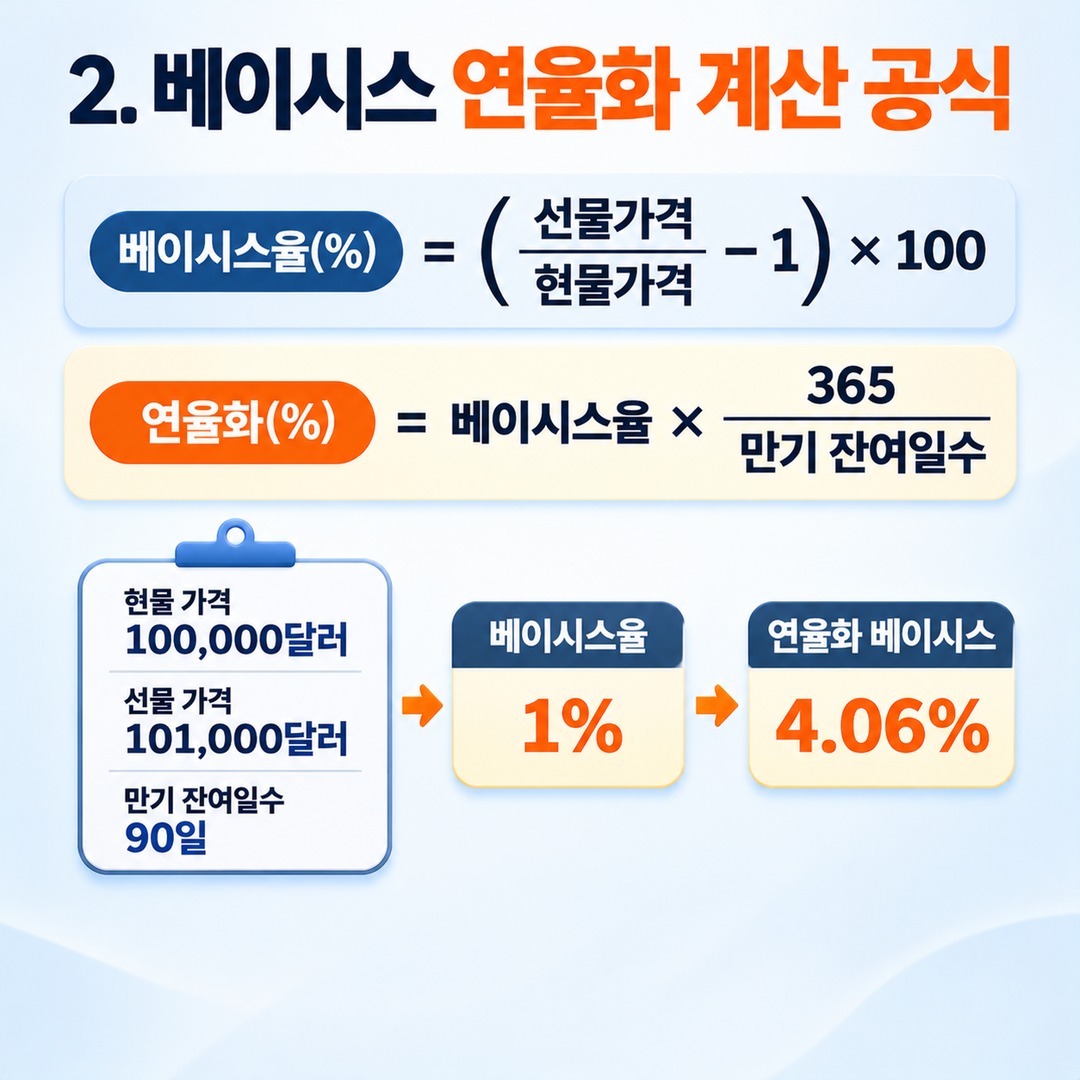
Calculation formulas
Basis rate (%)=(Futures price / Spot price−1)×100
\left(\frac{Futures price}{Spot price}-1\right)\times100\nAnnualized basis (%) = Basis rate × 365 / Remaining days until expiration
Basis rate\times\frac{365}{Remaining days until expiration}\nThis calculation uses a simple annualization method that does not account for compounding.
For example, if the spot price is USD 100,000 and the futures price is USD 101,000, the basis rate is 1%.
If 90 days remain until expiration, the calculation is as follows:
1×36590=4.06%\n1\times\frac{365}{90}=4.06\%\nTherefore, the annualized basis is approximately 4.06%.
Here, 4.06% is not a return that can be guaranteed over an actual period of 1 year. It is a converted figure used to compare futures price differences across contracts with different expiration dates on the same time basis.
3. What Do the Actual 2026-11-03 Bitcoin Futures Data Show?
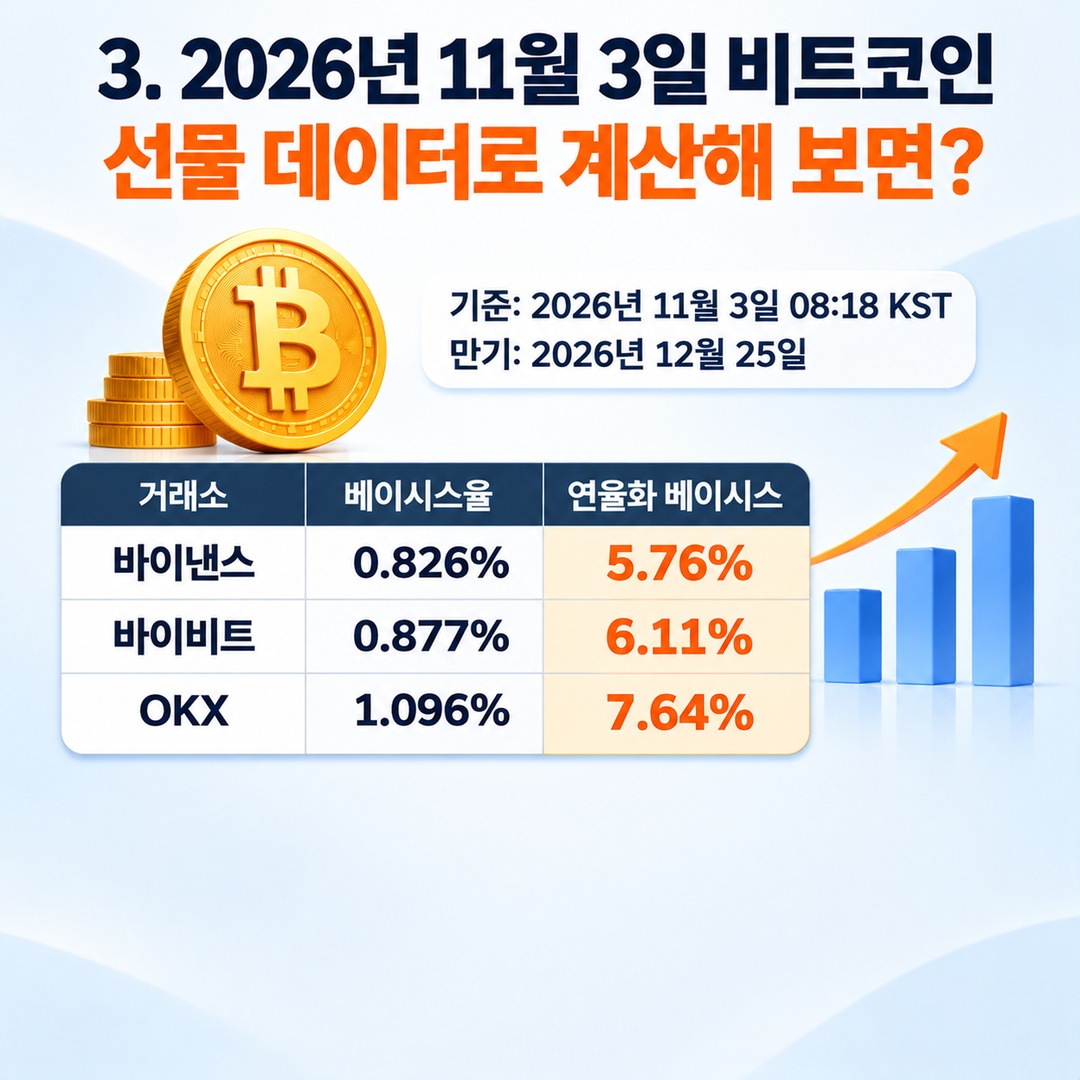
Applying publicly available futures data makes the calculation method easier to understand.
In publicly available data checked on 2026-11-03 at 8:18 KST, Bitcoin futures expiring in 2026-12-25 showed the following differences across exchanges.
Data reference: 2026-11-03 08:18 KST · Public market data
| Exchange | Basis Rate | Annualized Basis |
|---|---|---|
| Binance | 0.826% | 5.76% |
| Bybit | 0.877% | 6.11% |
| OKX | 1.096% | 7.64% |
All three exchanges are in contango, meaning their futures prices are higher than their respective spot indices.
However, their annualized basis figures are not identical.
The difference between the lowest figure on Binance and the highest on OKX is 1.88% percentage points.
Let's calculate the Binance figure directly.
Futures price: USD 77,481.09
Spot index: USD 76,846.13
Basis: USD 634.96
Time remaining until expiration: 52.4 days
① Calculating the basis rate
634.9676,846.13×100=0.826%\frac{634.96}{76,846.13}\times100
=0.826\%\n② Calculating the annualized basis
0.826×36552.4≈5.75%\n0.826\times\frac{365}{52.4}
\approx5.75\%\nThis is almost identical to 5.76%, the rounded figure reported in the public data.
This calculation allows us to compare futures contracts by accounting for the time remaining until expiration, rather than simply looking at how much higher their prices are.
However, spot indices and contract specifications vary across exchanges, so their figures should not be compared as though they represented returns on exactly identical products.
4. Does a Higher Annualized Basis Always Indicate a Favorable Market?
No.
A higher annualized basis means that futures are trading at a relatively higher price than the spot market.
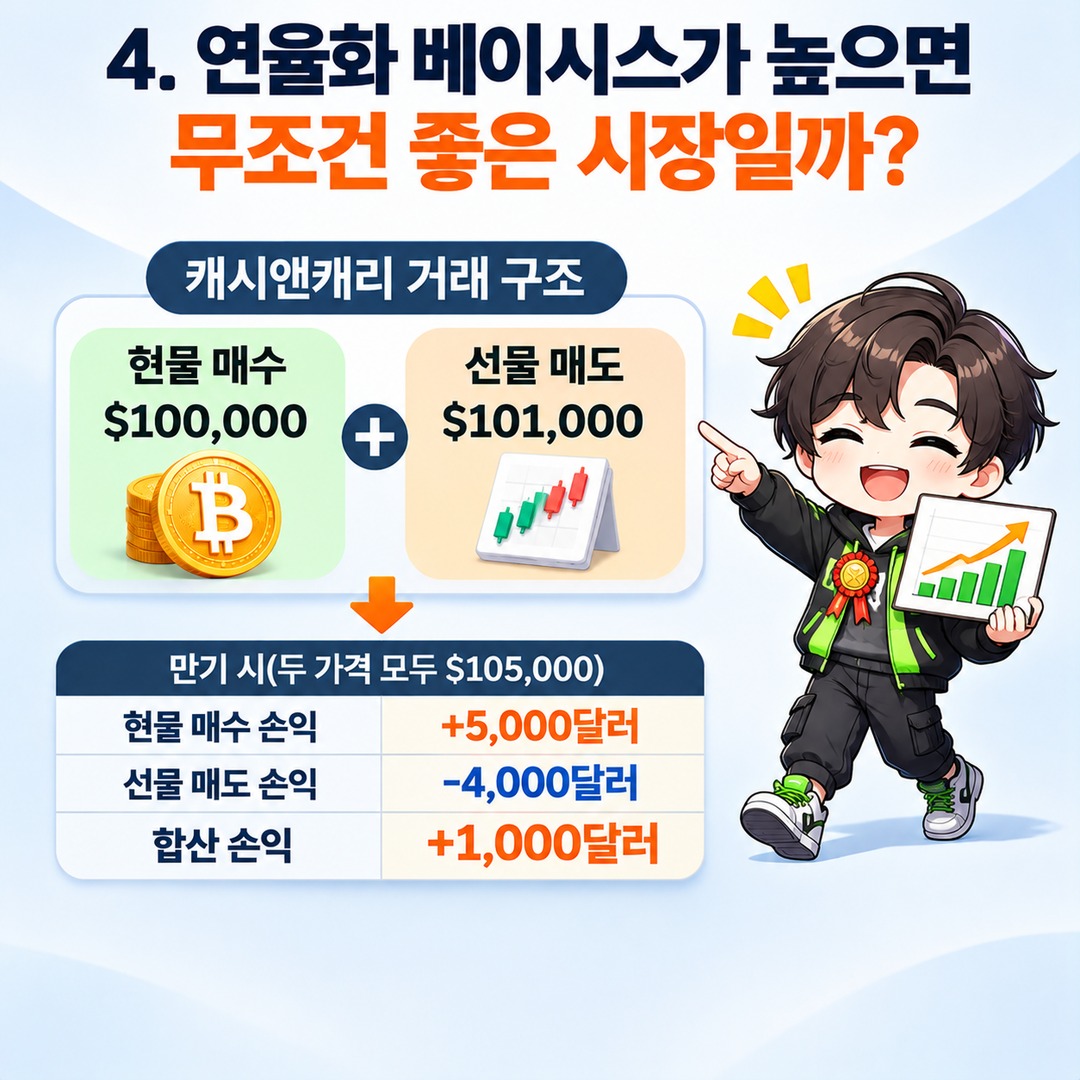
In this environment, the incentive for Cash-and-Carry trades, which involve buying spot and selling futures, may increase.
A Cash-and-Carry trade is a strategy that exploits the price difference between the two markets by simultaneously buying spot and selling futures.
For example, the structure could look like this.
Illustration using hypothetical prices
| Category | Trade | Price |
|---|---|---|
| Spot | Buy Bitcoin | $100,000 |
| Futures | Sell Bitcoin | $101,000 |
| Initial price difference | Futures premium | $1,000 |
Assuming that spot and futures prices converge to USD 105,000 at expiration, the result would be as follows.
Profit or loss on the spot purchase: +USD 5,000
Profit or loss on the futures sale: -USD 4,000
Combined profit or loss: +USD 1,000
Even if Bitcoin's price rises, the gain from the spot position and the loss from the short futures position offset each other.
Conversely, even if Bitcoin's price falls, the two positions can move in opposite directions in terms of profit and loss.
CME Group has explained the basis trade structure in which investors buy spot Bitcoin ETFs and sell CME futures.
Therefore, the basis is also an important supplementary indicator when interpreting situations in which ETF fund flows and futures OI move in different directions.
However, this does not establish that ETF inflows and short futures positions originated from the same investors.
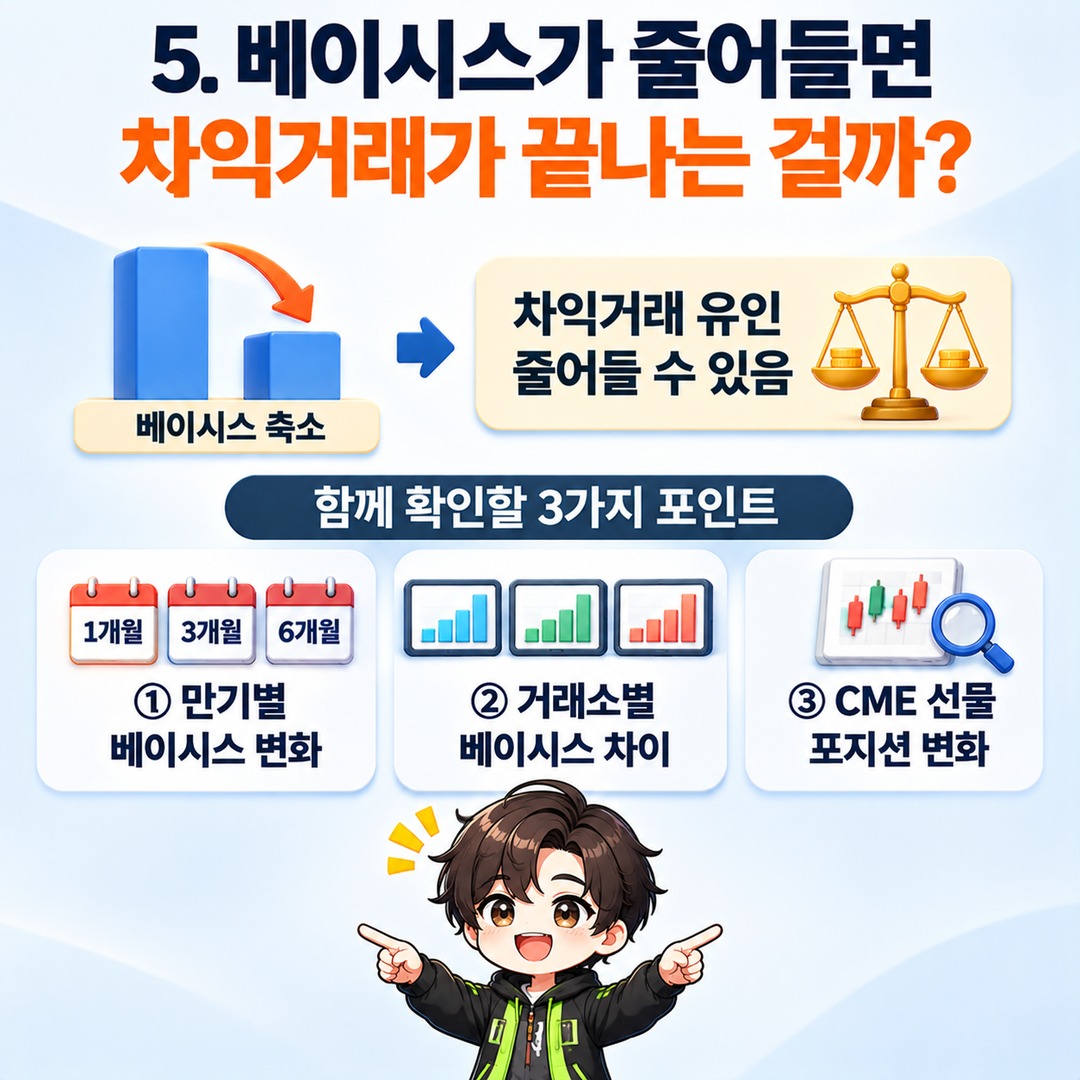
5. Does a Narrowing Basis Mean Arbitrage Trades Are Over?
A narrowing basis means that the price difference between futures and spot is decreasing.
In general, this can be interpreted as a reduction in the potential profit margin available from Cash-and-Carry trades.
However, a narrowing basis alone is not enough to conclude that all arbitrage positions have been closed.
It is useful to check the following three factors together.
First, changes in the basis across expiration dates
If the basis narrows only for near-dated contracts while remaining stable for longer-dated contracts, it is difficult to conclude that the overall pricing structure of the futures market has changed.
Where possible, compare the trends across 1-month, 3-month, and 6-month expirations.
Second, differences in the basis across exchanges
If the basis narrows on only one exchange, the change may reflect shifts in liquidity or supply and demand on that particular exchange.
Check whether similar movements are occurring across multiple exchanges.
Third, changes in CME futures positions
Positioning data for leveraged funds in CME futures can also provide useful supplementary information.
CME has previously linked the expansion of leveraged funds' net short positions in Bitcoin futures following the launch of spot ETFs to basis trading.
However, neither overall market OI nor leveraged funds' net short positions alone can establish the trading purpose of individual investors.
6. 4 Things That Are Easy to Overlook in Practice
Keep the following points in mind when checking annualized basis figures.
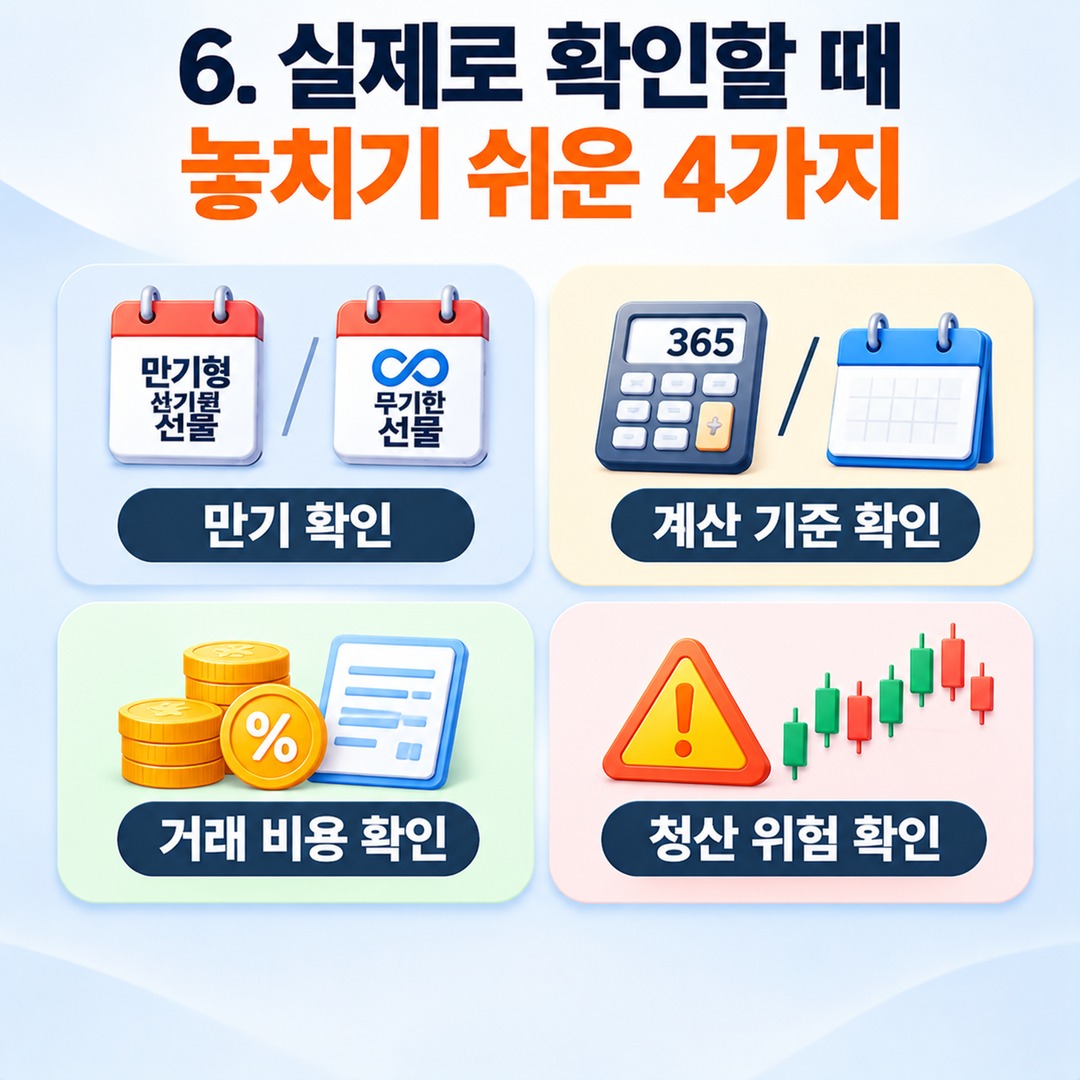
Check the expiration: Distinguish between dated futures and perpetual futures.
Check the calculation basis: Confirm whether 365-day or another annualization convention is being used.
Check transaction costs: Actual profitability changes when trading fees, slippage, borrowing costs, and collateral costs are taken into account.
Check liquidation risk: If futures prices move unfavorably, mark-to-market losses and additional margin requirements may arise before expiration.
In particular, the funding rate for perpetual futures and the basis for dated futures are not the same indicator.
Because perpetual futures have no fixed expiration date, they cannot be directly compared using the formula above, which relies on the number of days remaining until expiration.
Furthermore, even if the price difference between spot and futures eventually converges, the basis may widen further along the way. Therefore, a theoretical price difference does not automatically translate into realizable profit.
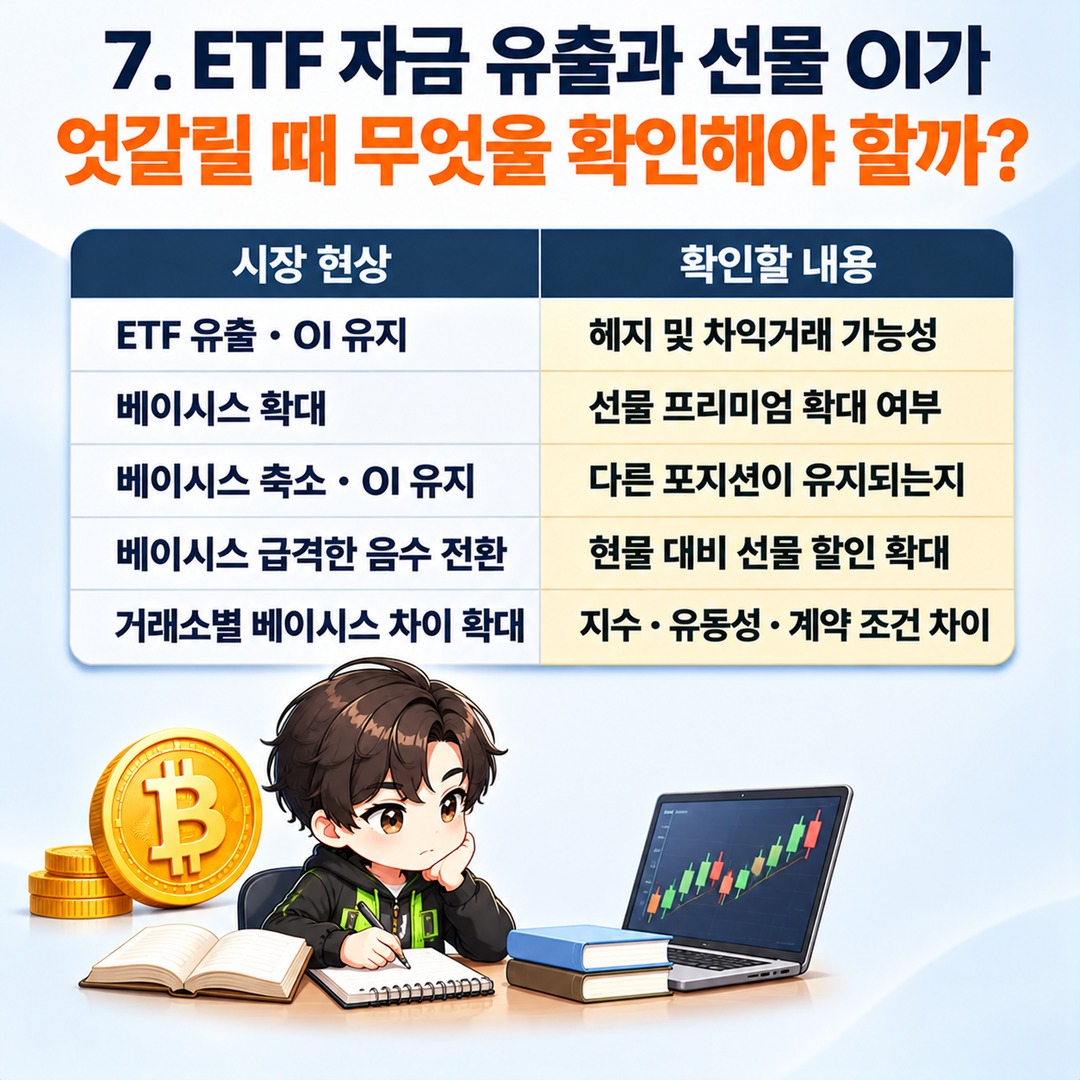
7. What Should You Check When ETF Outflows and Futures OI Move in Different Directions?
Ultimately, when spot Bitcoin ETF fund flows and futures open interest move in different directions, the futures basis should also be examined.
The following distinctions can help with interpretation.
| Market Observation | What to Check |
|---|---|
| ETF outflows · OI stable | Potential hedging and arbitrage activity |
| Widening basis | Whether the futures premium is increasing |
| Narrowing basis · OI stable | Whether other positions remain open |
| Sharp shift to a negative basis | Increasing futures discount relative to spot |
| Widening basis differences across exchanges | Differences in indices, liquidity, and contract specifications |
This table is a buy
※ This article is provided for informational purposes to help readers understand market trends. It does not constitute a recommendation to invest in any particular security or asset. You are responsible for your own final decisions and investment risks.
This post contains Coupang Partners affiliate links. We may earn a commission from qualifying purchases.