

Haven't Received Your VAT Preliminary Tax Notice? Amounts Below KRW 500,000 Are Excluded, and Notices Are Issued Through October 10
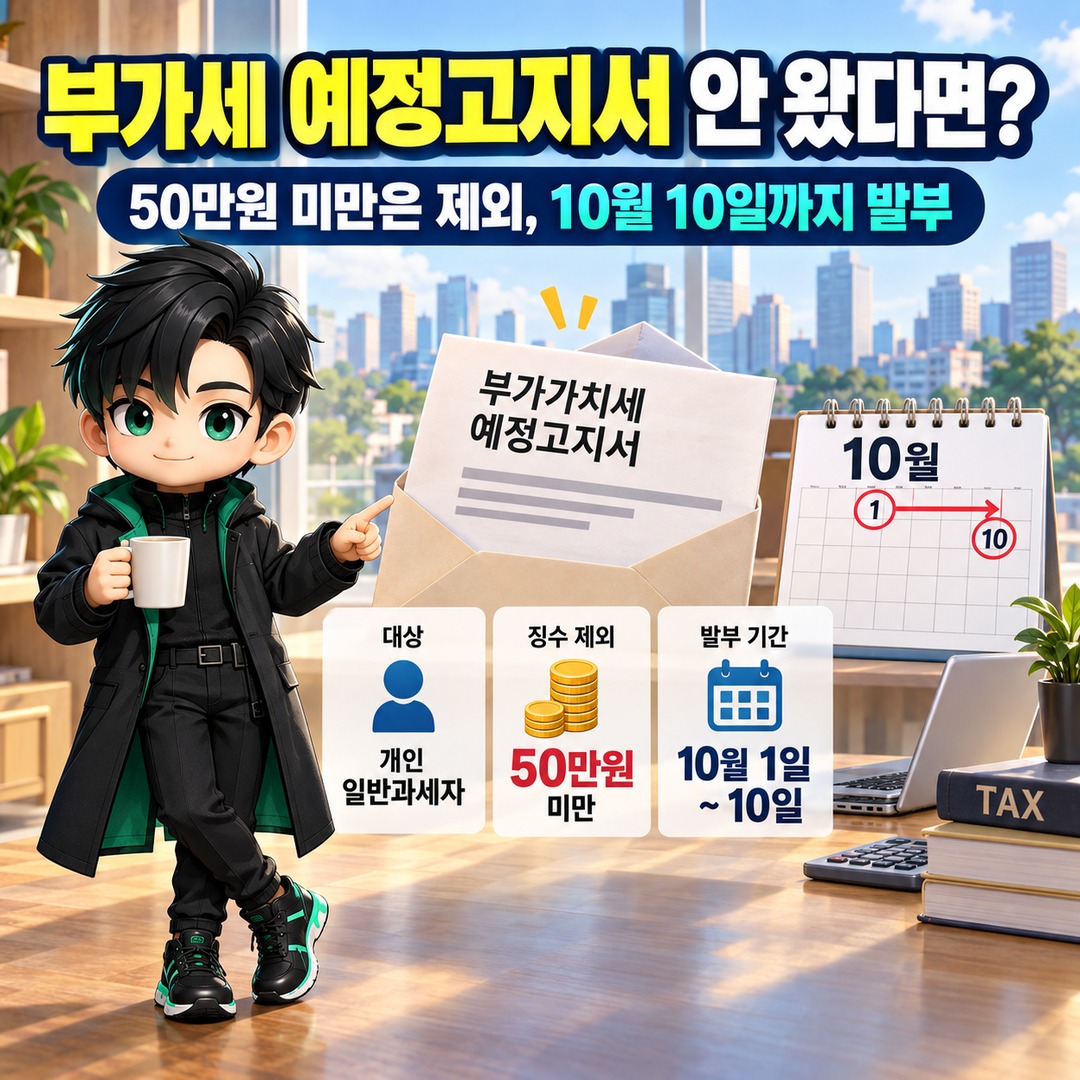
If you are an individual business owner subject to general VAT taxation and have not yet received your October 2026 preliminary VAT notice, there is no need to immediately assume that it was omitted. If the amount to be collected through preliminary assessment is below KRW 500,000, it is not collected at all. Under the law, preliminary tax notices for the 2th taxable period are issued from October 1 through 10.
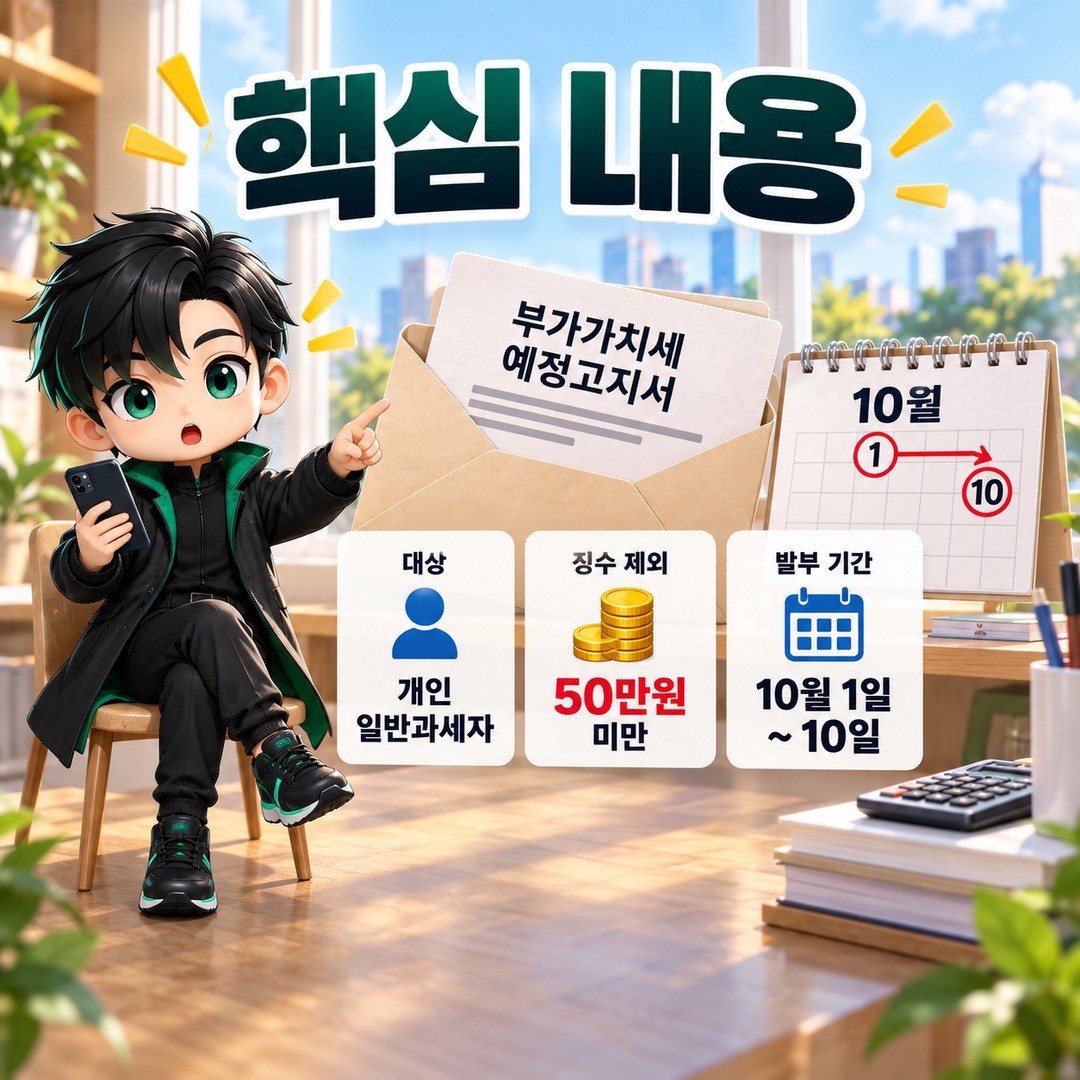
In particular, as of October 1, the notice issuance period has only just begun. Therefore, if you cannot find your notice, it is advisable to check the issuance schedule and the criteria for exemption from preliminary assessment separately.
If Your Preliminary Assessment Is Below KRW 500,000, You Do Not Have to Make an Interim Payment in October
Preliminary VAT assessments for individual business owners subject to general taxation are calculated based on the VAT paid during the previous taxable period.
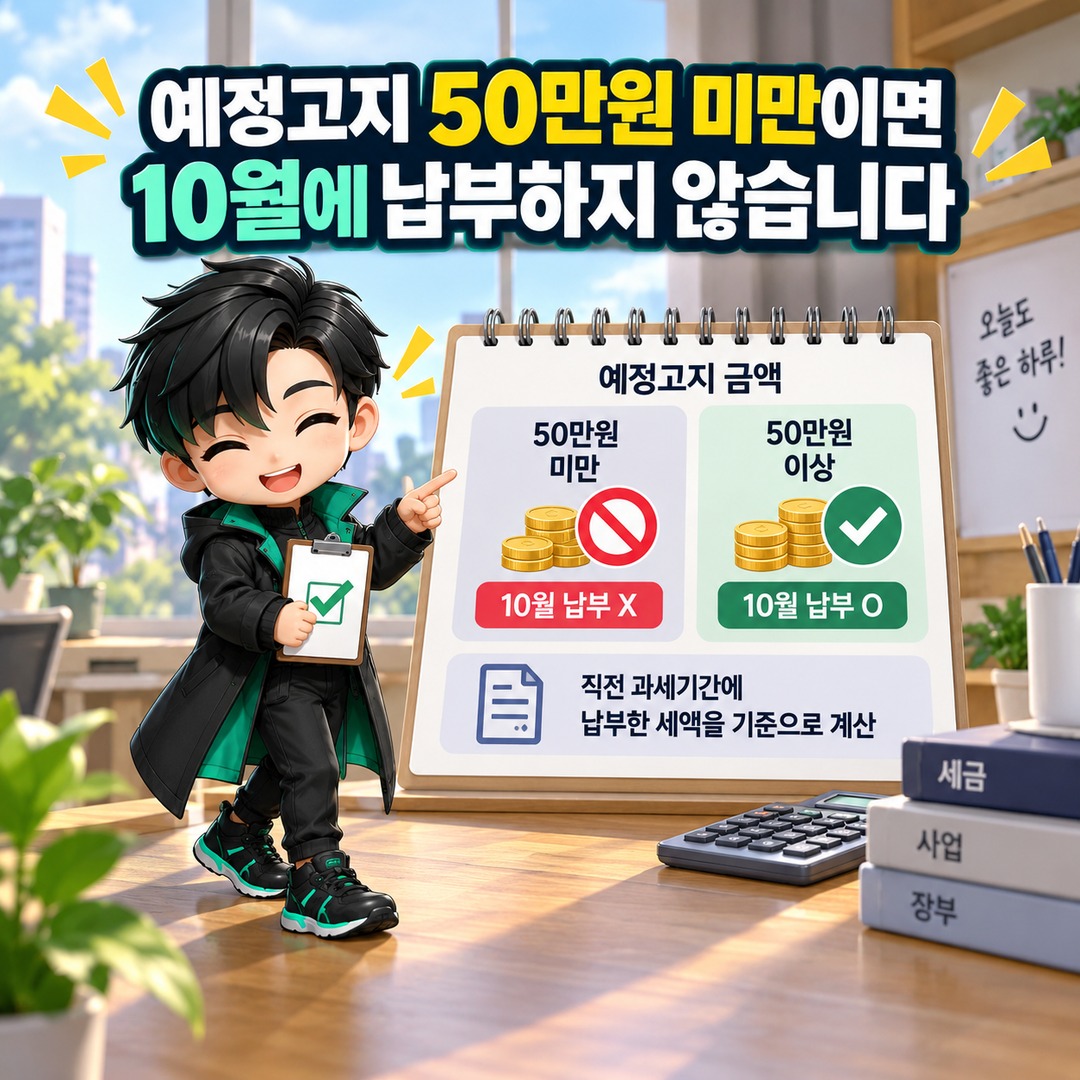
As a general rule, 50% of the VAT paid during the previous taxable period is assessed in advance, with amounts smaller than KRW 1,000 rounded down. However, if the resulting amount to be collected is below KRW 500,000, no preliminary assessment is issued.
There is a common misunderstanding here.
This does not mean that 'the VAT paid during the previous taxable period must have been below KRW 500,000.' The relevant threshold applies to the amount to be collected under the current preliminary assessment, calculated by applying 50% to the VAT paid previously.
For example, suppose the VAT paid during the previous taxable period was KRW 800,000. Applying 50% produces KRW 400,000.
KRW 800,000 × 50% = KRW 400,000
Because the amount to be collected through preliminary assessment is below KRW 500,000, no preliminary assessment would be issued based on this threshold alone.
Conversely, if the previous VAT payment was KRW 1,000,000, applying 50% produces exactly KRW 500,000.
KRW 1,000,000 × 50% = KRW 500,000
Because the law excludes amounts 'below KRW 500,000,' an amount equal to KRW 500,000 is not exempt under this monetary threshold. The actual assessed tax may differ from this simple calculation because individual circumstances, including tax credits and corrections, can affect the final amount.
Not Having a Notice on October 1 Is Not Necessarily Unusual
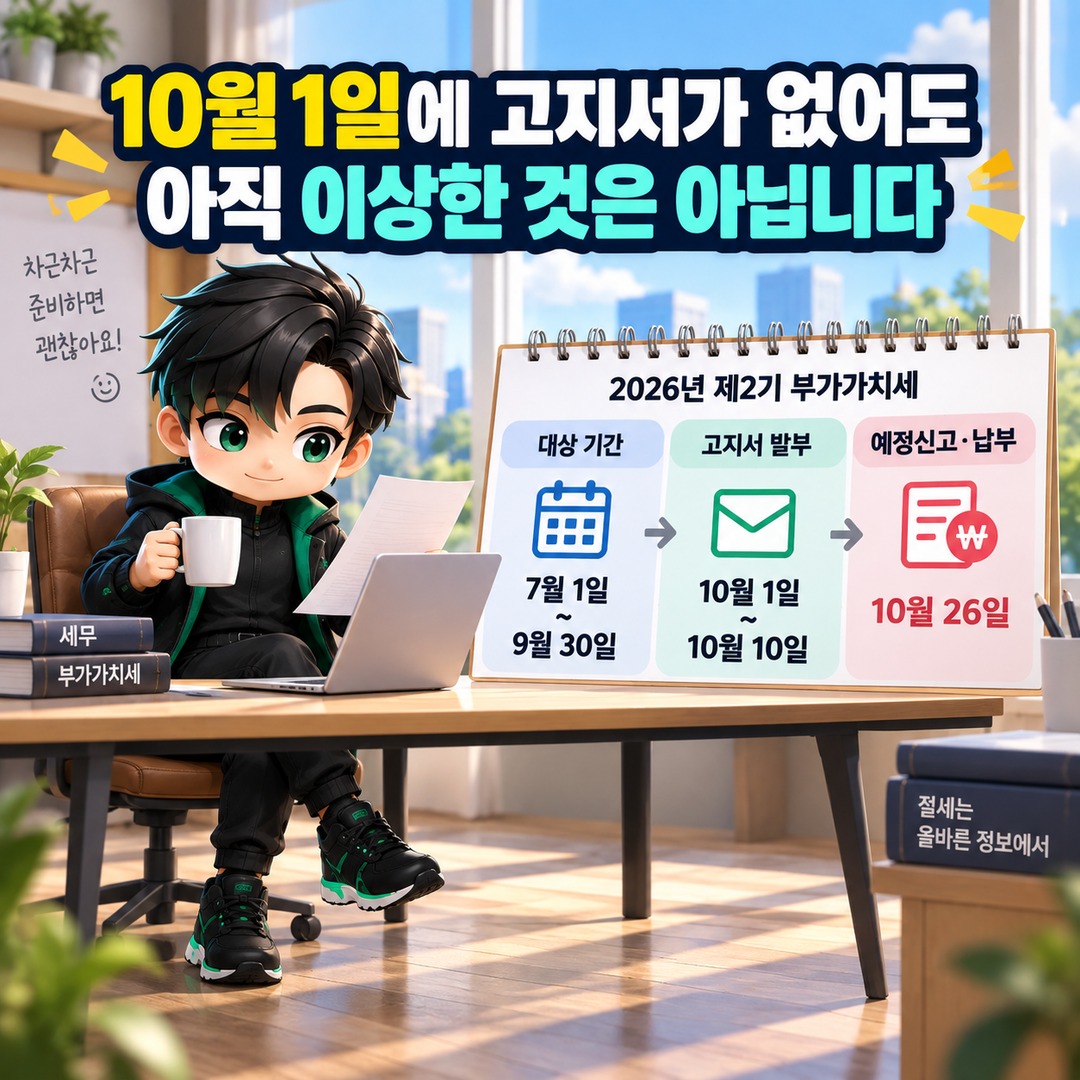
The preliminary VAT reporting period for the 2th taxable period of 2026 runs from July 1 through September 30. According to the National Tax Service's tax calendar, the preliminary VAT filing and payment deadline for the 2th taxable period of 2026 is October 26.
The standard deadline is 25 days after the end of the preliminary reporting period. However, because 2026-10-25 falls on a Sunday, the deadline moves to the following day, October 26, under the deadline-extension provisions of the Framework Act on National Taxes.
In addition, under the Enforcement Decree of the Value-Added Tax Act, payment notices for preliminary assessments in the 2th taxable period are issued from October 1 through October 10.
Therefore, rather than wondering why a notice has not arrived in early October, you should first recognize that the issuance period is still underway.
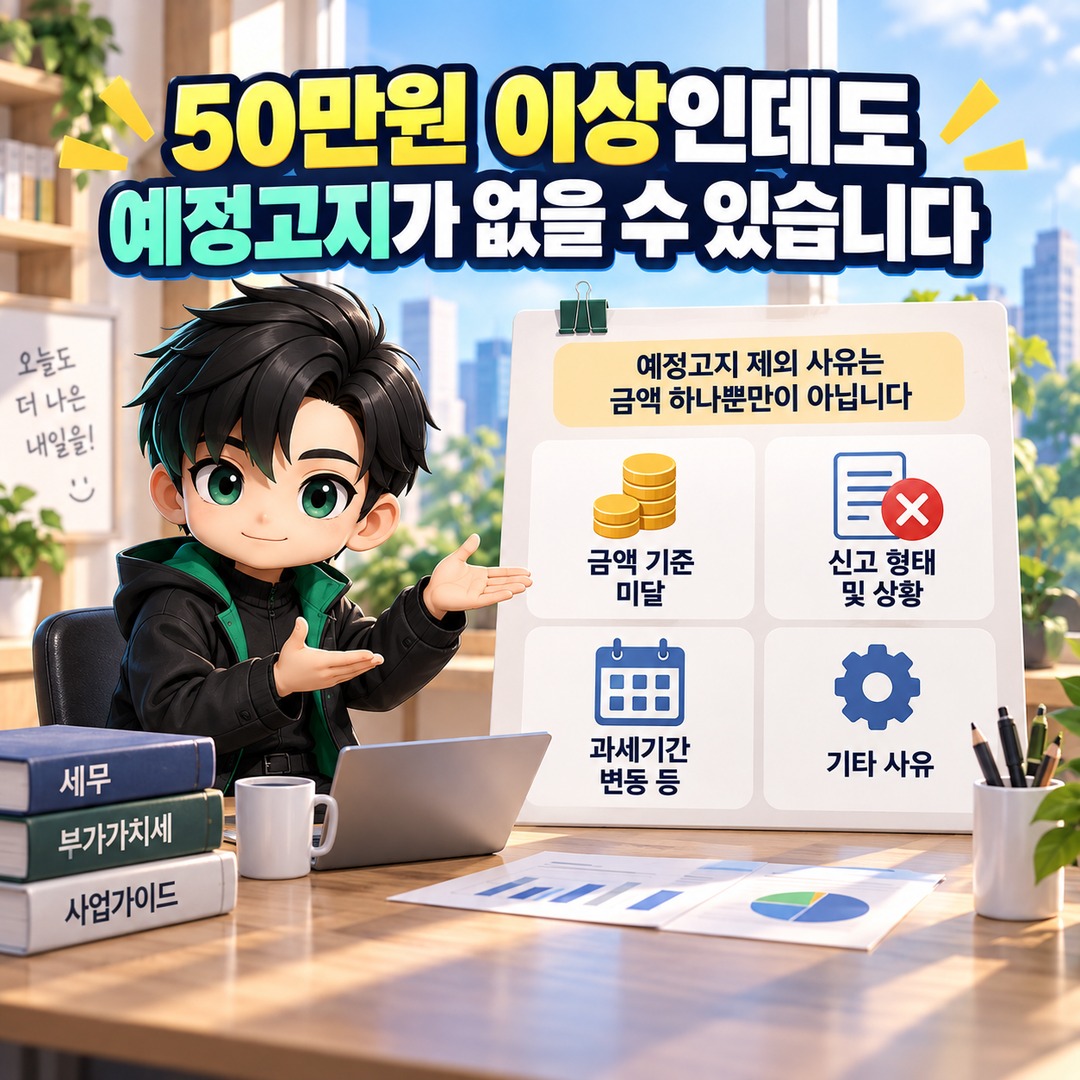
You May Not Receive a Preliminary Assessment Even If the Amount Is KRW 500,000 or More
The monetary threshold is not the only reason for exclusion from preliminary VAT assessment.
Under the current Value-Added Tax Act, businesses excluded from preliminary assessment include not only those whose amount to be collected is below KRW 500,000 but also business owners who changed from simplified taxation to general taxation as of the first day of the relevant taxable period, among others.
The National Tax Service also explains that individual business owners subject to general taxation and small corporations meeting certain requirements are generally assessed 50% of the VAT paid during the previous taxable period. However, they are excluded from preliminary assessment if the amount is below KRW 500,000 or if they fall under the applicable tax-status conversion criteria.
Certain businesses may also be excluded from preliminary assessment under special tax administration support measures. For example, during the 1th taxable period of 2026, the National Tax Service excluded qualifying exporters, businesses in certain industries sensitive to oil prices, and businesses located in designated preemptive crisis-response areas from preliminary assessment. However, this was a support measure applicable to the 1th taxable period of 2026, so it should not be assumed that the same measure automatically applies to the 2th taxable period.
Does Having No Notice Mean Your VAT Liability Disappears in October?
No, it does not.
A preliminary VAT assessment does not finalize the tax liability. Instead, it allows part of the tax to be paid in advance during the taxable period. If you pay the amount stated in a preliminary assessment, that payment is deducted as tax already paid when you file your final VAT return.
For individual business owners subject to general taxation, the final VAT reporting period for the 2th taxable period runs from July 1 through December 31. Therefore, not receiving a preliminary assessment in October does not mean that VAT on business activities during the second half of the year has been waived.
In other words,
Exemption From Preliminary Assessment = No Interim Payment in October
This is the more accurate way to understand the exemption.
VAT on all business activities during the second half of the year will be settled through the subsequent final return for the 2th taxable period.
If Your Sales Have Fallen Sharply, There Is Something Else to Check Regardless of Whether You Received a Notice
Being subject to preliminary assessment does not necessarily mean that every business owner must pay only the amount stated in the notice.
The Value-Added Tax Act allows qualifying businesses to file a preliminary VAT return when their business performance has deteriorated due to temporary closure, sluggish business conditions, or similar circumstances. If a preliminary return is filed, the existing preliminary assessment decision is treated as though it had never been made.
Specifically, the Enforcement Decree provides for preliminary filing when the value of supplies or VAT payable during the preliminary reporting period is less than 1 out of 3 of the value of supplies during the previous taxable period or the VAT payment amount used as the basis for calculating the preliminary assessment, or when the business seeks an early VAT refund during the preliminary reporting period.
Therefore, individual business owners whose sales declined significantly during 7–September should check not only the amount shown on their tax notice but also whether they qualify to file a preliminary VAT return.
Here's What to Check in October 2026
If you are an individual business owner subject to general VAT taxation, first determine whether you are subject to preliminary assessment in October.
If you have not yet received a notice, do not immediately assume on October 1 that it has been omitted. Instead, check that the statutory issuance period for preliminary tax notices for the 2th taxable period runs from 1 through 10 of October.
If you still have no preliminary assessment afterward, check in order whether the amount to be collected is below KRW 500,000, whether your taxation category has changed, and whether any other grounds for exclusion from preliminary assessment apply.
According to the National Tax Service's tax calendar, the preliminary VAT filing and payment deadline for the 2th taxable period of 2026 is October 26.
You can verify whether a notice has actually been issued and the amount assessed for your business through the notice records in Hometax or by contacting your local tax office. The outcome may vary depending on your individual tax liability, taxation category, and eligibility for tax administration support measures.
Verification Reference: 2026-10-01 at 7 a.m., Based on Publicly Available Materials From the National Tax Service and the National Law Information Center
※ This article is provided for reference purposes to help readers understand market trends and does not constitute investment advice concerning any particular stock or asset. Final investment decisions and responsibility rest with the individual.
Related Articles
Why 180 Days May Not Be Reached Despite Working 6 Months: How to Calculate It With 5 Days per Week