

Why Your Rebalancing Account Balance Changes Even When Both Asset Prices Return to Their Starting Levels
This post contains Coupang Partners affiliate links. We may earn a commission from qualifying purchases.
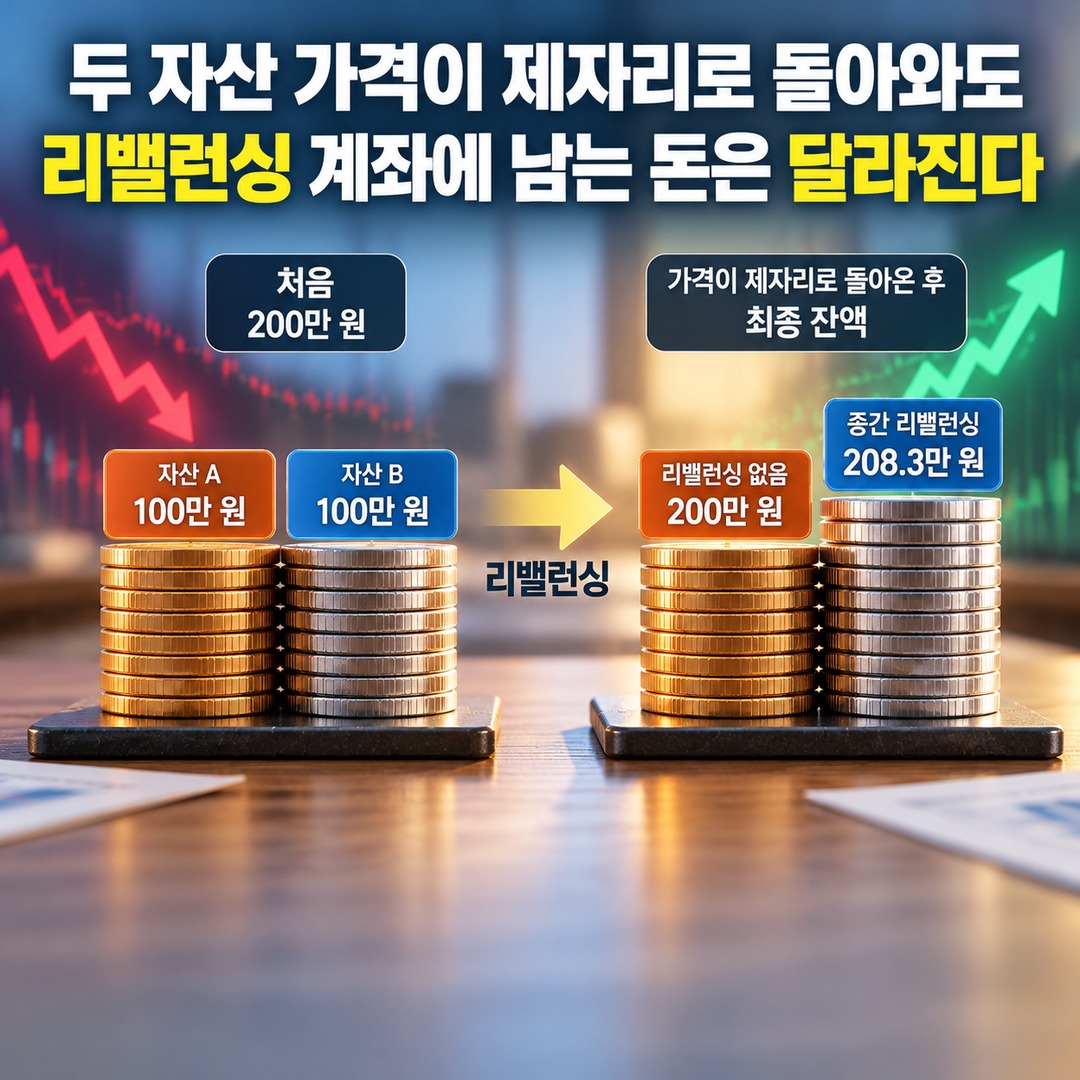
Even when both asset prices return to their original levels, the investment account balance does not necessarily return to its starting value. This is because selling assets that have risen in price and buying more of those that have fallen changes the quantities held. A hypothetical example dividing an initial investment of KRW 2,000,000 into equal amounts of KRW 1,000,000 shows how the final balance changes depending on whether rebalancing takes place along the way.
What Happens When You Divide KRW 2,000,000 Into Equal Amounts of KRW 1,000,000?
In this hypothetical example, an investment of KRW 2,000,000 is allocated equally between Asset A and Asset B, with KRW 1,000,000 invested in each. Both assets are assumed to have an initial price of 100.
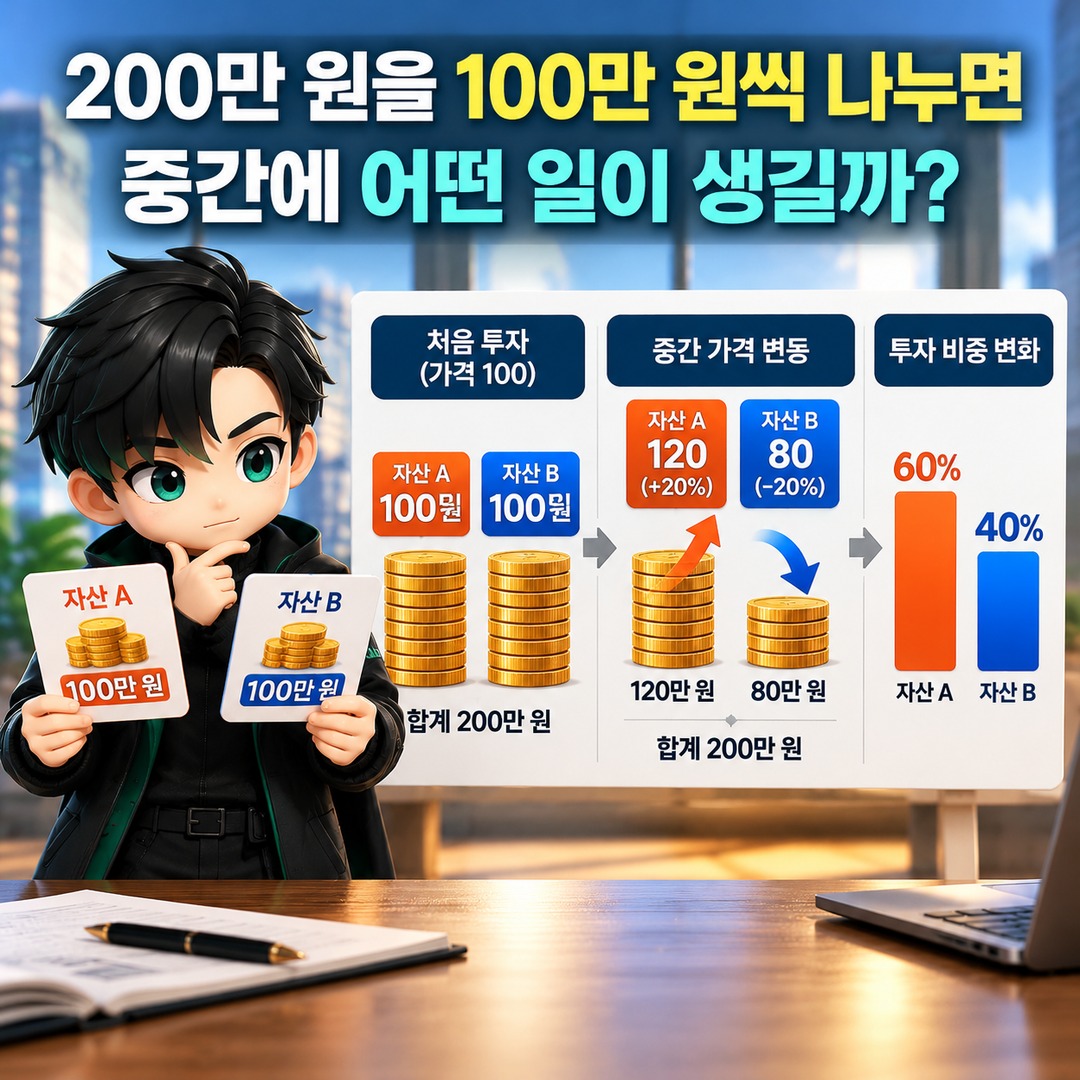
The first price movement is as follows.
| Category | Initial Value | Intermediate Price | Intermediate Value |
|---|---|---|---|
| Asset A | KRW 1,000,000 | 120 (+20%) | KRW 1,200,000 |
| Asset B | KRW 1,000,000 | 80 (-20%) | KRW 800,000 |
| Total | KRW 2,000,000 | KRW 2,000,000 |
At this point, the total account value remains unchanged, but the investment allocation has shifted.
Asset A: 60%
Asset B: 40%
To maintain the originally established 50-to-50 allocation ratio, you would need to sell KRW 200,000 worth of Asset A and buy KRW 200,000 worth of Asset B.
Immediately after rebalancing, the allocation returns to A KRW 1,000,000 and B KRW 1,000,000.
What Is the Final Balance When Both Asset Prices Return to Their Original Levels?
Suppose that, after the intermediate adjustment, the prices of Asset A and Asset B both return to their initial price of 100.
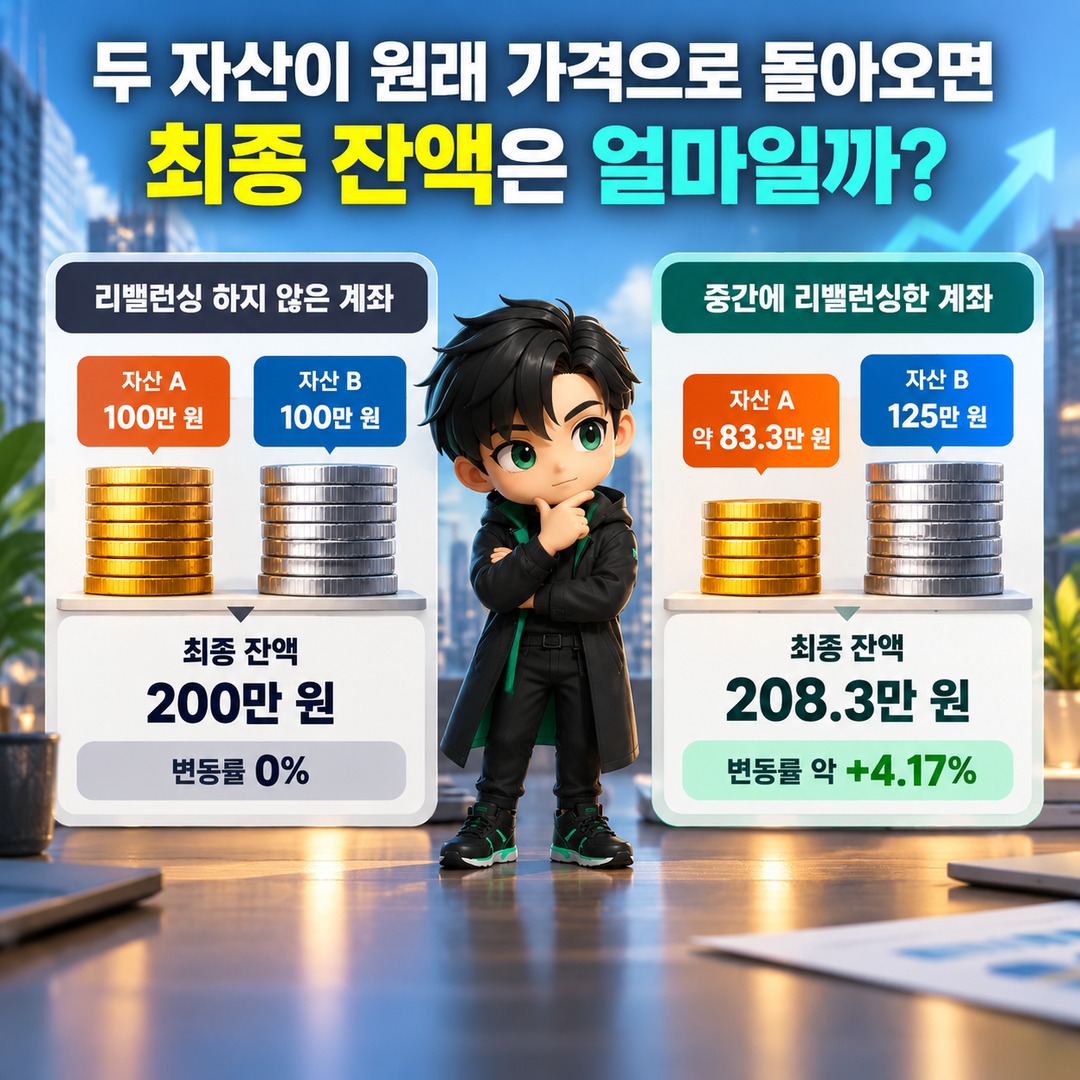
What matters at this point is not the market value but the quantities of each asset held.
① Account Without Rebalancing
The quantities originally purchased remain unchanged.
Asset A: 1 million units × 100 = KRW 1,000,000
Asset B: 1 million units × 100 = KRW 1,000,000
Final balance without rebalancing
KRW 2,000,000
Change compared with the initial investment: 0%
② Account Rebalanced Midway
Part of Asset A was sold when its price was 120, and additional Asset B was purchased when its price was 80.
Asset A: approximately 8,333.33 units × 100 = approximately KRW 833,333
Asset B: 12,500 units × 100 = KRW 1,250,000
Final balance after rebalancing
KRW 2,083,333
Approximately +4.17% compared with the initial investment
Hypothetical example. Transaction costs and taxes excluded.
No rebalancing: Final balance KRW 2,000,000
Intermediate rebalancing: Final balance KRW 2,083,000.0
The difference is approximately KRW 83,333.
Although both asset prices returned to their starting levels, the account balances differ because the quantities of Assets A and B changed during the rebalancing process.
This calculation is a hypothetical example illustrating the relationship between price movements and trading quantities, not an actual investment result. It assumes that fractional-unit trading is possible and excludes commissions, taxes, bid-ask spreads, and execution errors.
Rebalancing Does Not Always Increase Your Account Balance
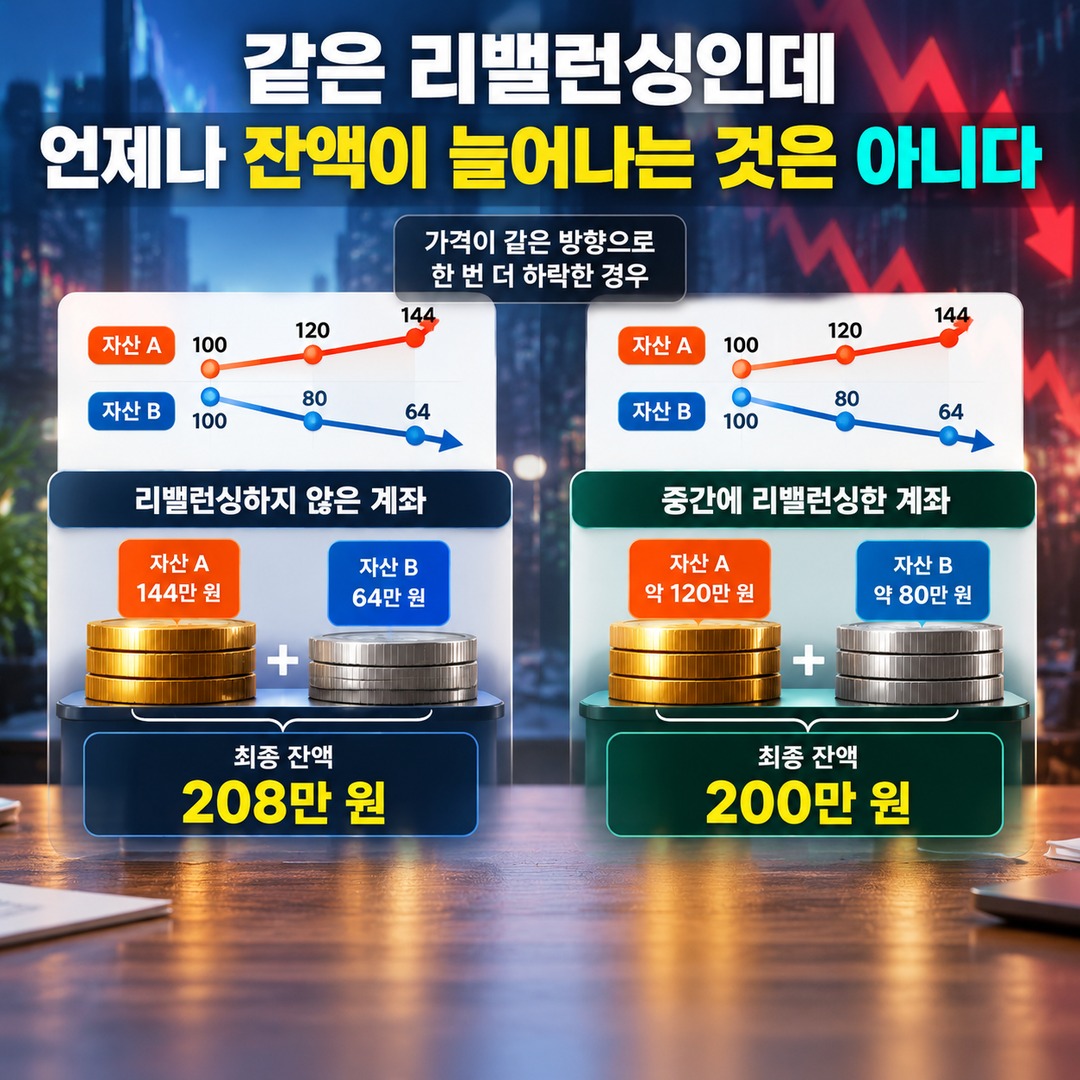
The gain in the example above occurred because the two asset prices moved in opposite directions before returning to their original levels. The same result does not occur under all market conditions.
Now suppose that, instead of recovering after the first movement, prices move once more in the same respective directions.
A: 100 → 120 → 144
B: 100 → 80 → 64
If no rebalancing had taken place in the meantime, the final values would be as follows.
A: KRW 1,440,000
B: KRW 640,000
Total: KRW 2,080,000
By contrast, if the portfolio had been rebalanced midway to a 50-to-50 allocation, the results would be as follows.
A: approximately KRW 1,200,000
B: approximately KRW 800,000
Total: KRW 2,000,000
This time, the account without rebalancing has KRW 80,000 more.
Therefore, the +4.17% from the earlier calculation should not be interpreted as the typical return from rebalancing. The outcome depends on the sequence of price movements and how differently the assets perform relative to one another.
The Purpose of Rebalancing Is Not to Maximize Returns at All Costs
The U.S. Securities and Exchange Commission (SEC), through its investor education website Investor.gov, describes rebalancing as the process of restoring a portfolio to its originally established asset allocation. This involves reducing holdings in assets whose portfolio weights have increased due to price appreciation and buying more of assets whose weights have declined.
Vanguard's portfolio management guidance also identifies the central purpose of rebalancing as managing the target asset allocation and risk level. It should be distinguished from market-timing strategies designed to maximize returns.
SEC Investor.gov's explanation of asset allocation and rebalancing
Vanguard's guide to portfolio rebalancing
When considering rebalancing, it is helpful to check these three things first.
1. Does the original target allocation still match your investment objectives and risk tolerance?
2. Have your current asset allocations moved beyond the adjustment thresholds you established in advance?
3. Is there a meaningful benefit to rebalancing after accounting for transaction fees and taxes on purchases and sales?
The SEC explains that rebalancing methods may involve transaction fees or tax implications. Vanguard also describes approaches for reducing trading costs and taxes, including partial adjustments and using cash flows such as dividends and interest.
What to Check Before Comparing Account Balances
If both assets have returned to their original prices but the account balance is different, compare the following items.
Initial purchase quantities and current holdings
Quantities sold during intermediate rebalancing
Additional quantities purchased and their actual execution prices
Whether dividends and distributions were paid and reinvested
Transaction fees and taxes
For foreign assets subject to currency conversion, the exchange rates at the time of purchase and valuation
In particular, even if the underlying asset prices of foreign ETFs or stocks return to their original levels, their KRW-denominated valuation can change when exchange rates fluctuate.
Ultimately, the current price alone does not determine an account balance. You also need to consider the sequence of price movements, the quantities actually held throughout that process, cash flows, and costs.
The key point of the KRW 2,000,000 example is clear. Rebalancing is not about restoring asset prices to their original levels; it is a transaction that readjusts investment allocations that have changed. Whether that transaction benefits the final account balance depends on subsequent price movements.
※ This article provides information for understanding market trends and is not a recommendation to invest in any particular security or asset. All final investment decisions and responsibility for them rest with the individual investor.
This post contains Coupang Partners affiliate links. We may earn a commission from qualifying purchases.