

If You Withdraw Money from an RIA Account Within 1 Year, Could You Lose the Tax Benefit? The Difference Between Early Withdrawals and Investment-Profit Withdrawals
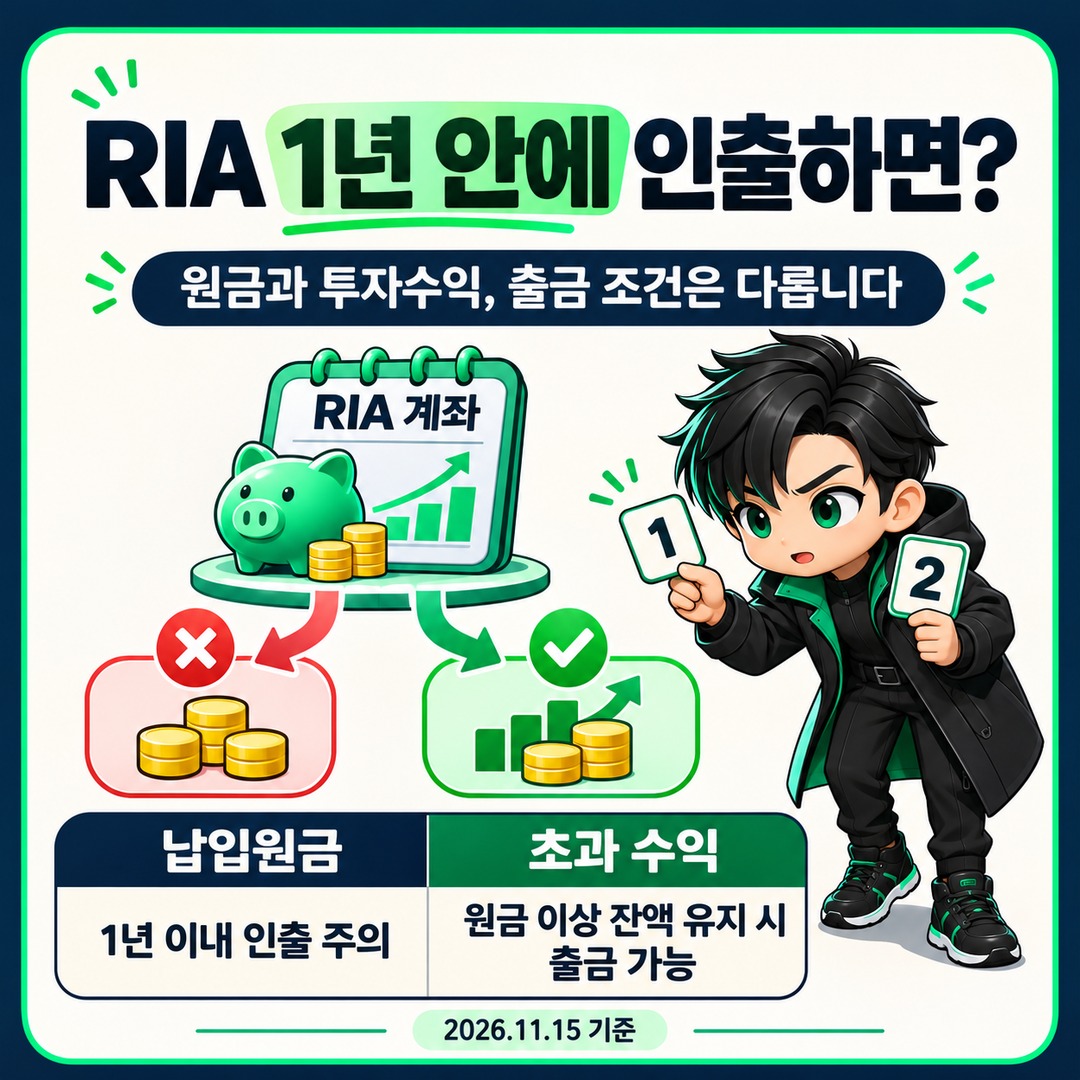
To qualify for a capital gains tax reduction on overseas stocks, funds from their sale must remain in an RIA (Domestic Market Return Account) for at least 1 year from the date they are converted into Korean won. However, investment profits generated in the account are not necessarily locked in. The withdrawal rules differ for contributed principal and investment profits exceeding that principal.
As of 2026-11-15, let’s distinguish between the restrictions on early withdrawals from an RIA account and the exceptions.
1. Would withdrawing only KRW 1 from an RIA account make the tax benefit disappear?
The key is to distinguish whether the withdrawn money is contributed principal or investment profits exceeding the contributed principal.
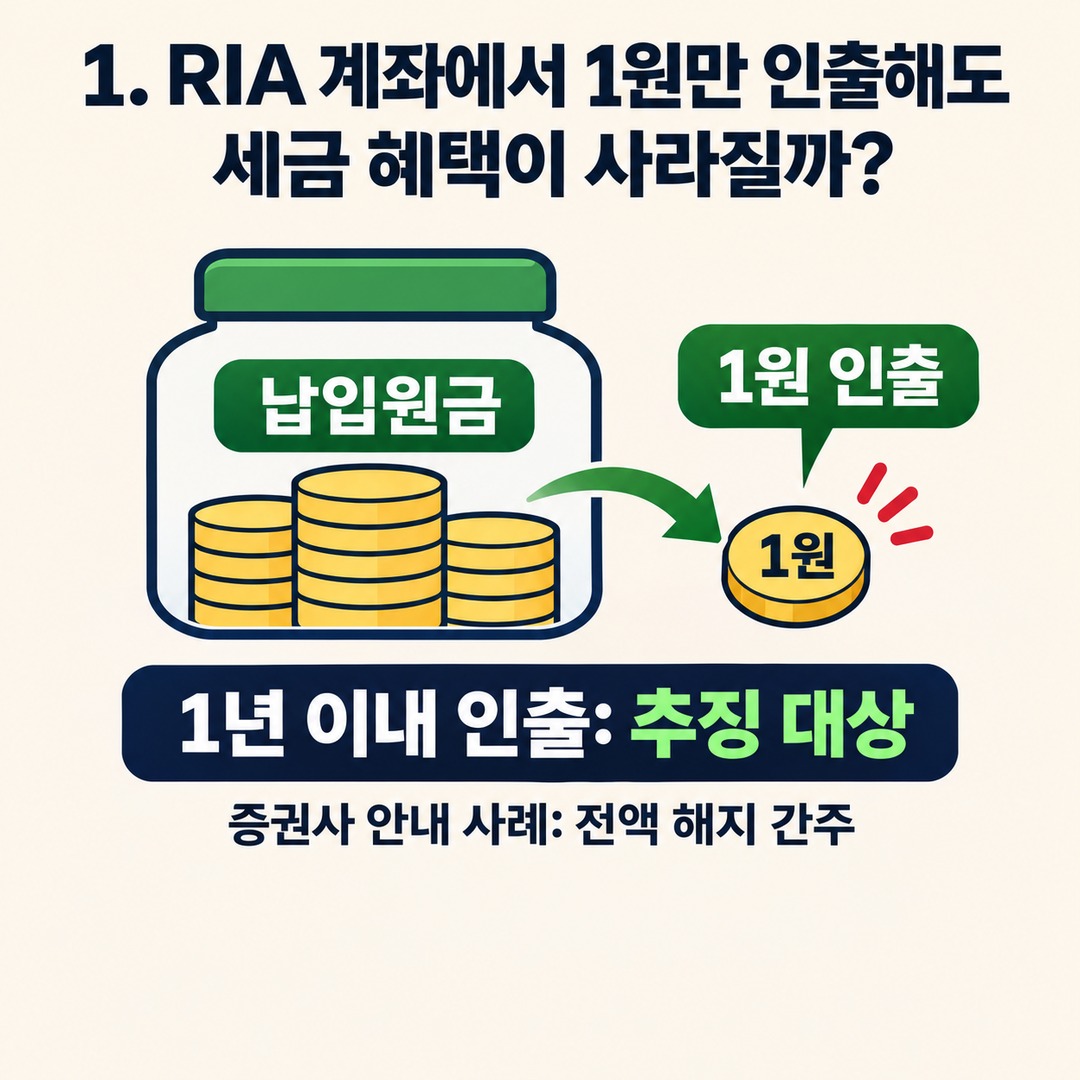
Under Article 91(26) of the Restriction of Special Taxation Act, withdrawing an amount contributed to an RIA account before 1 year has passed from the contribution date makes it subject to post-benefit tax monitoring.
| Withdrawal situation | Tax benefit |
|---|---|
| Withdrawal of contributed principal within 1 year | Subject to recapture |
| Partial withdrawal of contributed principal within 1 year | Subject to recapture |
| Withdrawal of investment profits exceeding the contributed principal | The excess may be withdrawn |
| Withdrawal of principal after 1 year has passed from the contribution date | Withdrawal requirement met |
The point that requires particular attention is KRW 1.
Some securities firms’ guidance says that withdrawing even KRW 1 of contributed principal within 1 year is treated as a full account closure, canceling all tax benefits.
Therefore, do not assume that withdrawing only part of the principal will be allowed without consequences.
2. Why can investment profits be withdrawn before 1 year has passed?
An RIA is structured to distinguish between contributed principal and investment profits.
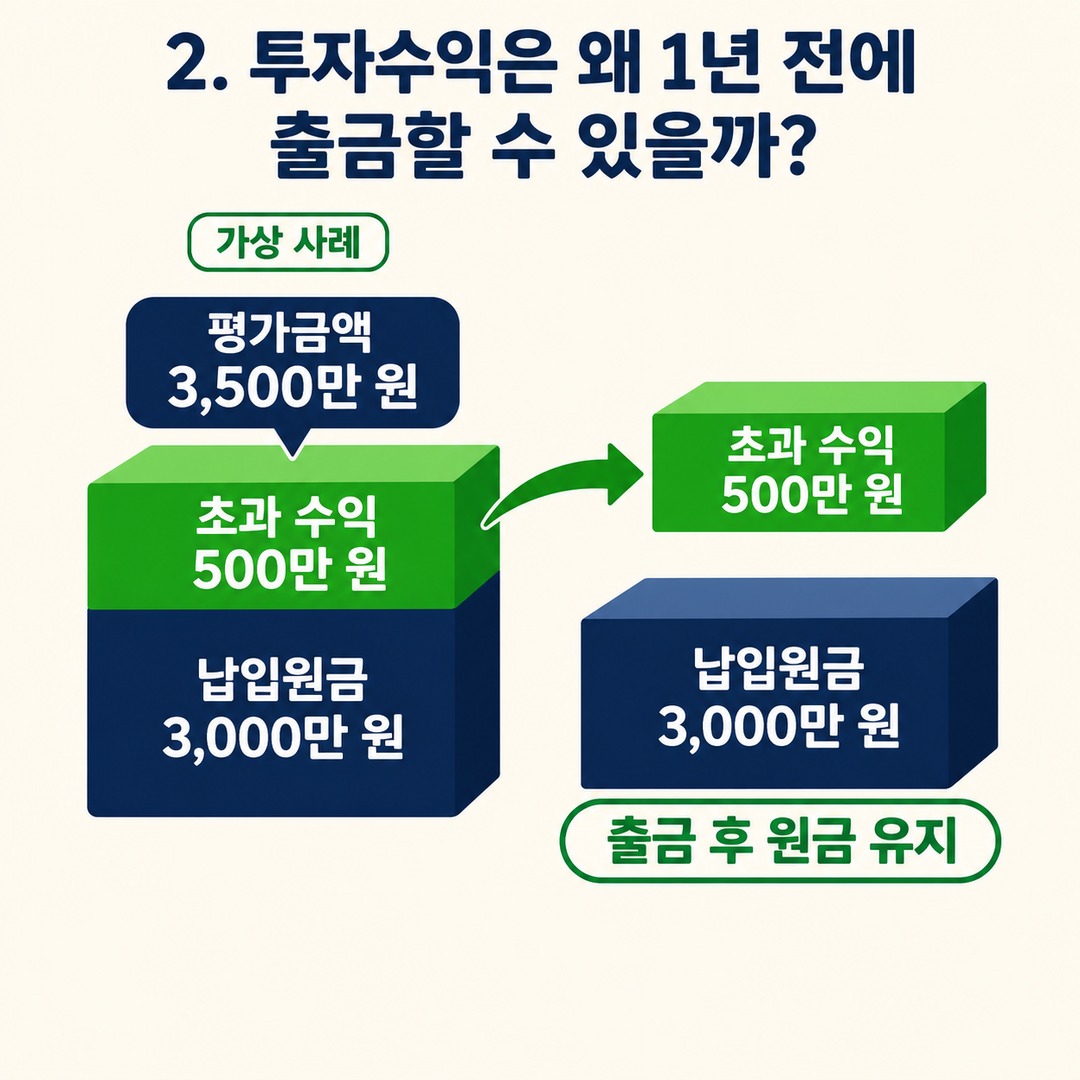
Under the law, if the account’s balance exceeds the cumulative amount contributed, the excess is treated as profit and may be withdrawn. The withdrawal is treated as coming from profits first, and the account balance must remain at least equal to the cumulative contributed principal after the withdrawal.
Here is an example.
Author’s calculation · Hypothetical example for clarity
| Category | Amount |
|---|---|
| Cumulative principal contributed to the RIA | KRW 30,000,000 |
| Valuation after investing in domestic stocks | KRW 35,000,000 |
| Profit exceeding contributed principal | KRW 5,000,000 |
| Withdrawable profit | Up to KRW 5,000,000 |
In this situation, even after withdrawing the excess profit of KRW 5,000,000, KRW 30,000,000 remains in the account.
The situation changes if KRW 1,000,000 is withdrawn from the principal of KRW 30,000,000.
Because this would mean withdrawing contributed principal before 1 year has passed, it could trigger recapture of the tax benefits.
The key point is that selling stocks and converting them to cash does not automatically make that amount an investment profit.
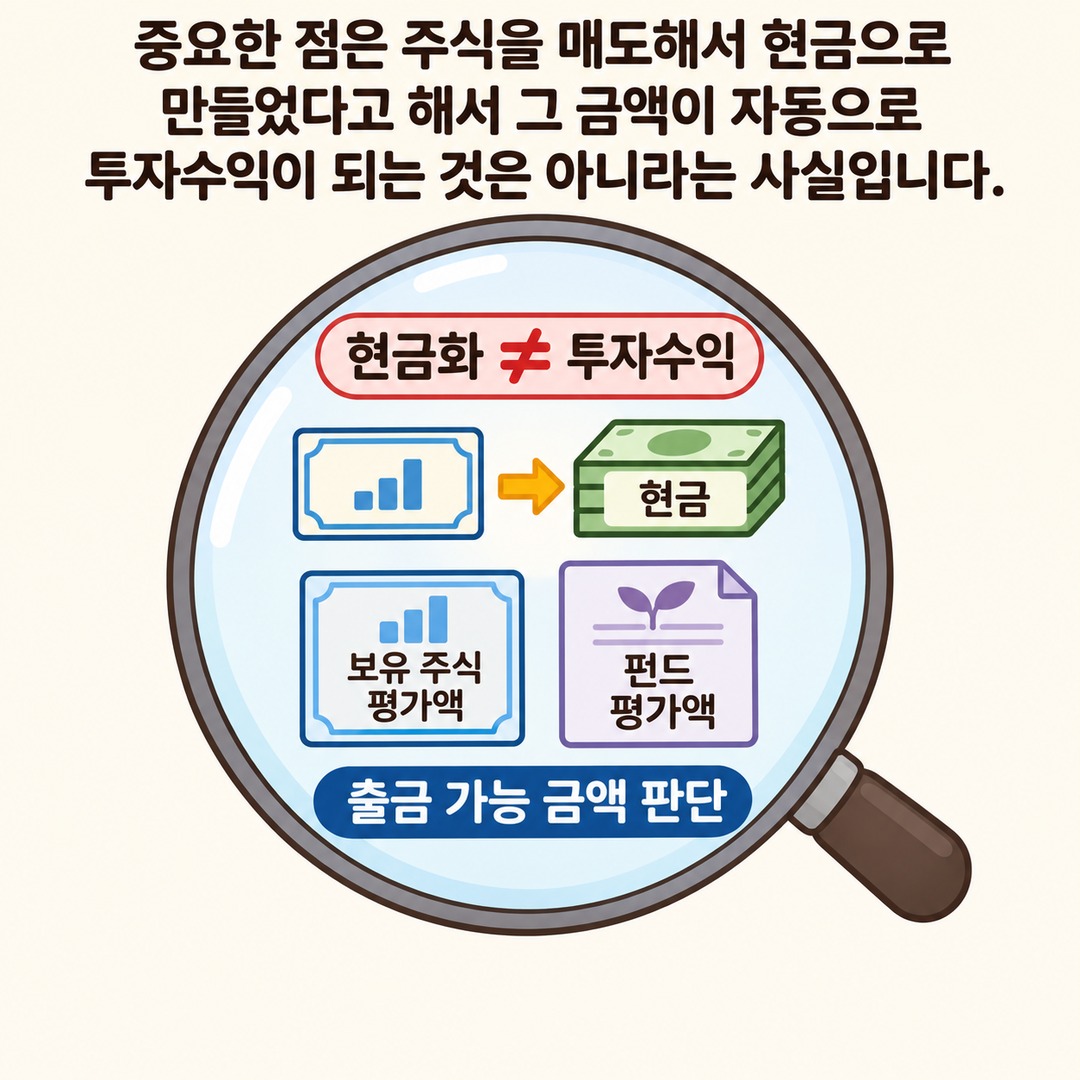
The amount available for withdrawal is determined by taking into account not only cash, but also the valuation of stocks, funds, and other holdings.
3. Is the 1-year period for an RIA account counted from the account opening date?
No. The relevant date is not when the account was opened, but when the overseas stocks were sold, the proceeds were converted into Korean won, and the funds were deposited.
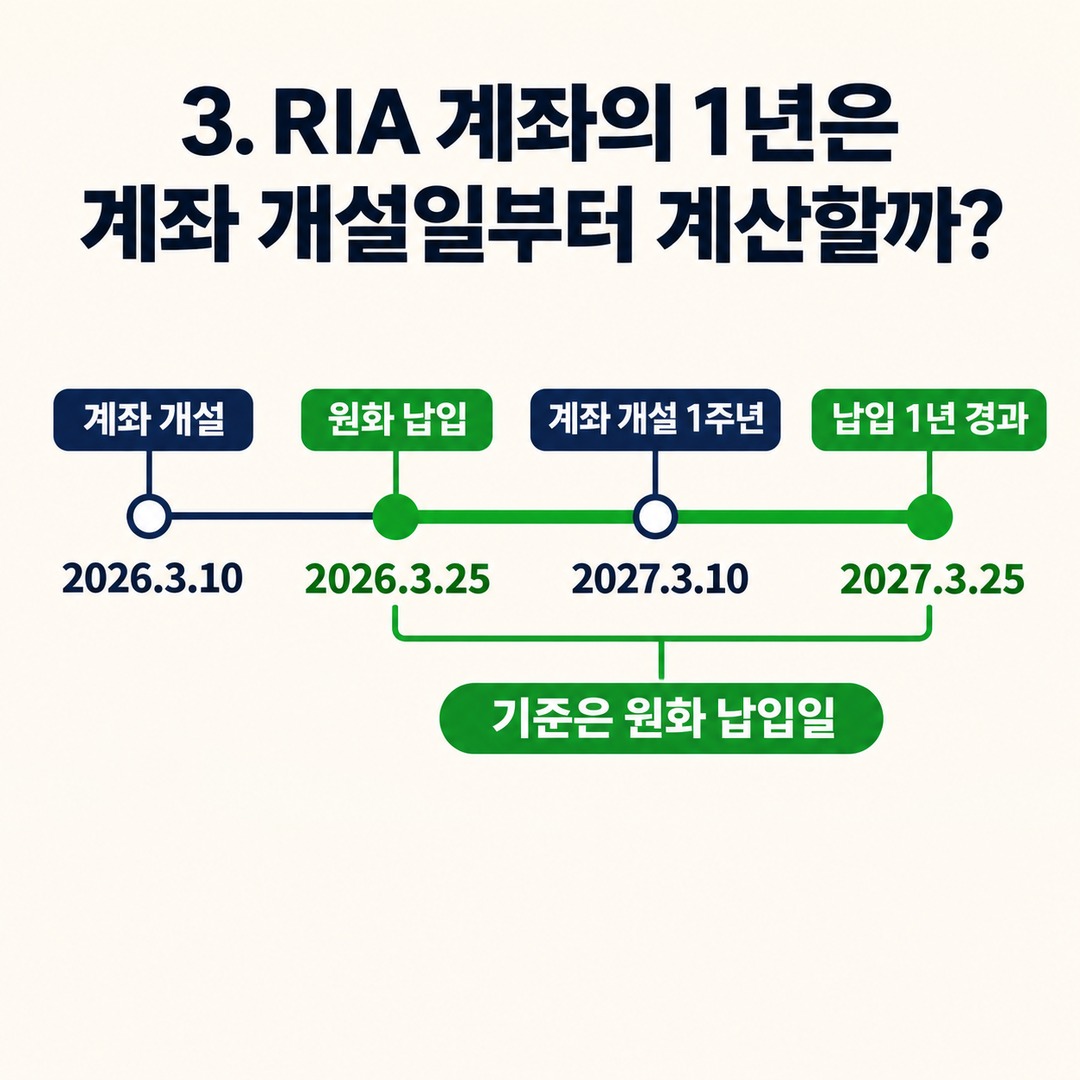
Guidance from Korea Investment & Securities and Mirae Asset Securities also explains that the 1-year period is calculated from the settlement of the sale proceeds and their conversion into Korean won.
For example:
| Category | Date |
|---|---|
| RIA account opened | 2026-03-10 |
| Proceeds from overseas stock sales deposited in Korean won | 2026-03-25 |
| 1-year mark | 2027-03-25 |
In the example above, 2027-03-10 is the account’s 1 anniversary, but it is not the point at which 1 year has passed since the contribution.
Also, if you made deposits after selling overseas stocks on multiple occasions, you need to check whether 1 year has passed for each deposit date.
Some securities firms also tie their guidance on maturity and early-termination procedures to the date of the final deposit. Before making an actual withdrawal, check the RIA terms and conditions of the relevant securities firm.
4. When would taxes have to be paid again after an early withdrawal?
Simply returning the withdrawn money does not resolve the matter.
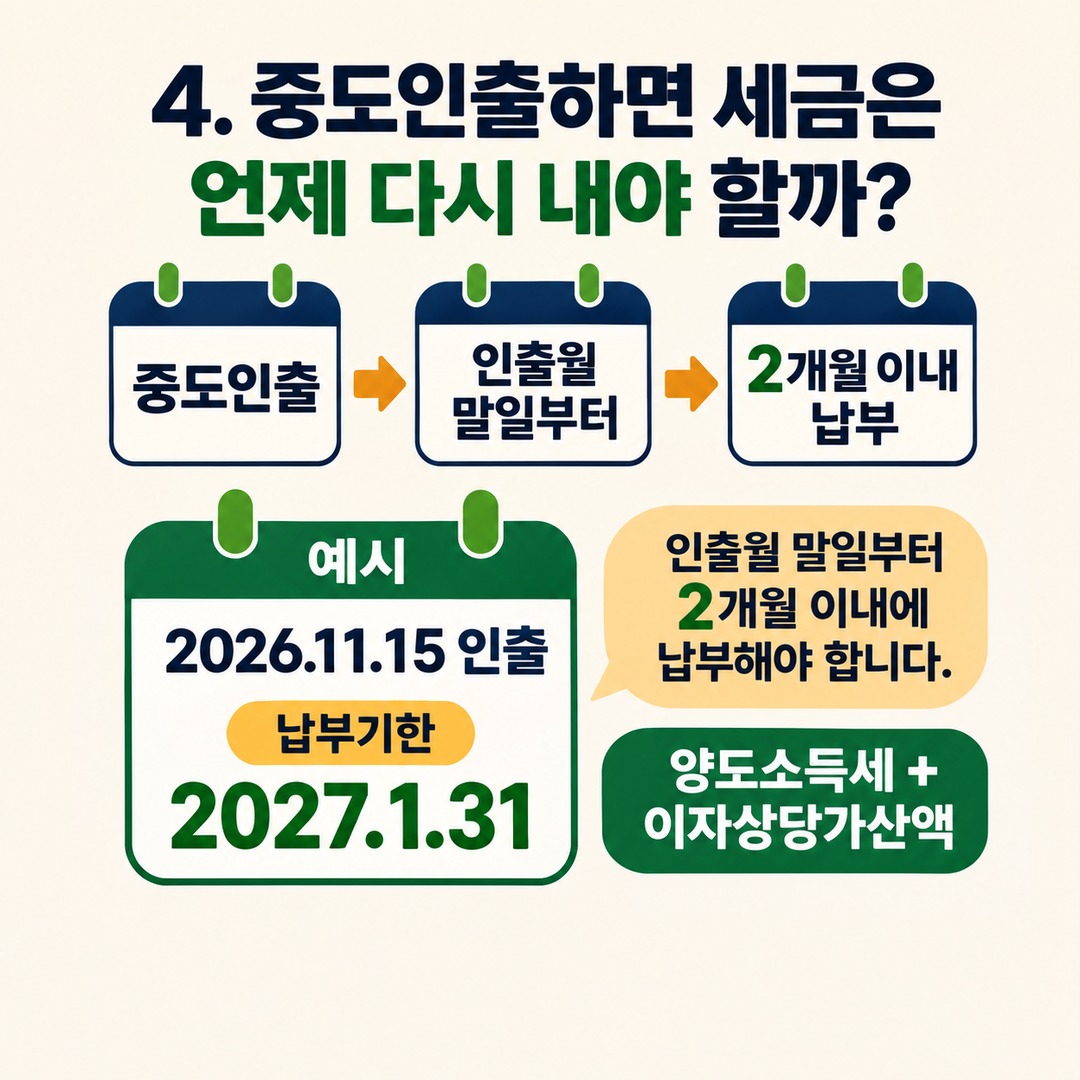
Article 91(26), paragraphs 4 and 5, of the Restriction of Special Taxation Act provides that withdrawing contributed amounts before 1 year has passed requires payment of capital gains tax and an additional amount equivalent to interest.
The payment deadline is within 2 months from the last day of the month in which the withdrawal occurs.
For example, if contributed principal was withdrawn early on 2026-11-15, the statutory payment deadline is 2027-01-31.
However, the actual tax due when filing and paying will depend on the deduction applied, the tax rate, and the calculation of the additional amount equivalent to interest.
There is another point that is easy to overlook.
Even if no money had been withdrawn from the account by the time of the May 2027 capital gains tax filing, a post-benefit recapture issue may arise if an amount contributed in 2026 is withdrawn before 1 year has passed from the contribution date.
Korea Investment & Securities also lists this as a separate point requiring attention.
5. Are there exceptions if money is needed because of death or illness?
Ordinary financial difficulties must be distinguished from unavoidable circumstances recognized by law.
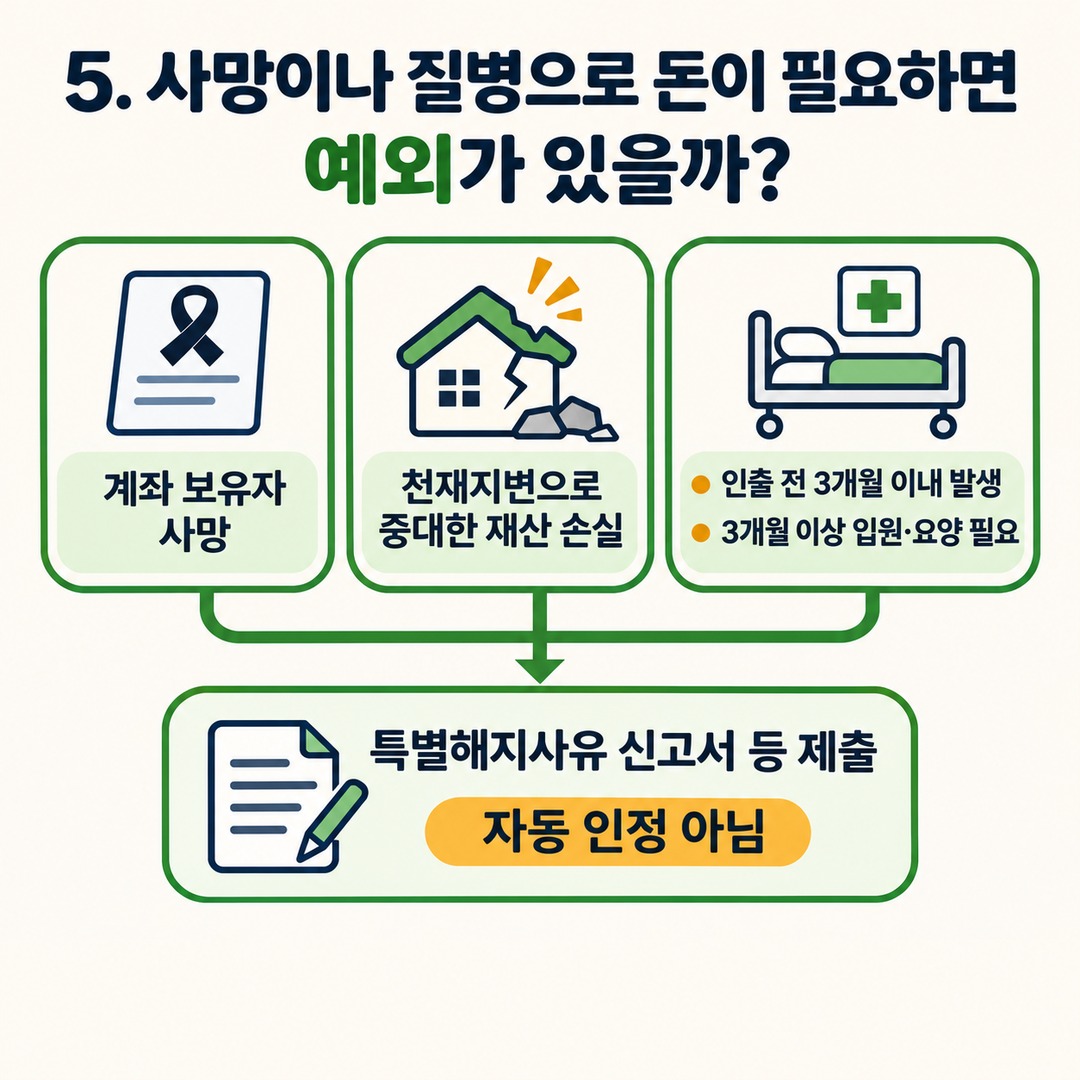
Article 93(12) of the Enforcement Decree of the Restriction of Special Taxation Act specifies the following as exceptions.
Death of the account holder
Significant property loss caused by a natural disaster
An injury or illness arising within 3 months before the withdrawal date that requires hospitalization or medical care for at least 3 months
However, having an exceptional circumstance does not mean it will automatically be accepted.
You must submit the required documents, such as a special early-termination reason report, to the financial institution and confirm the specific eligibility requirements and procedures.
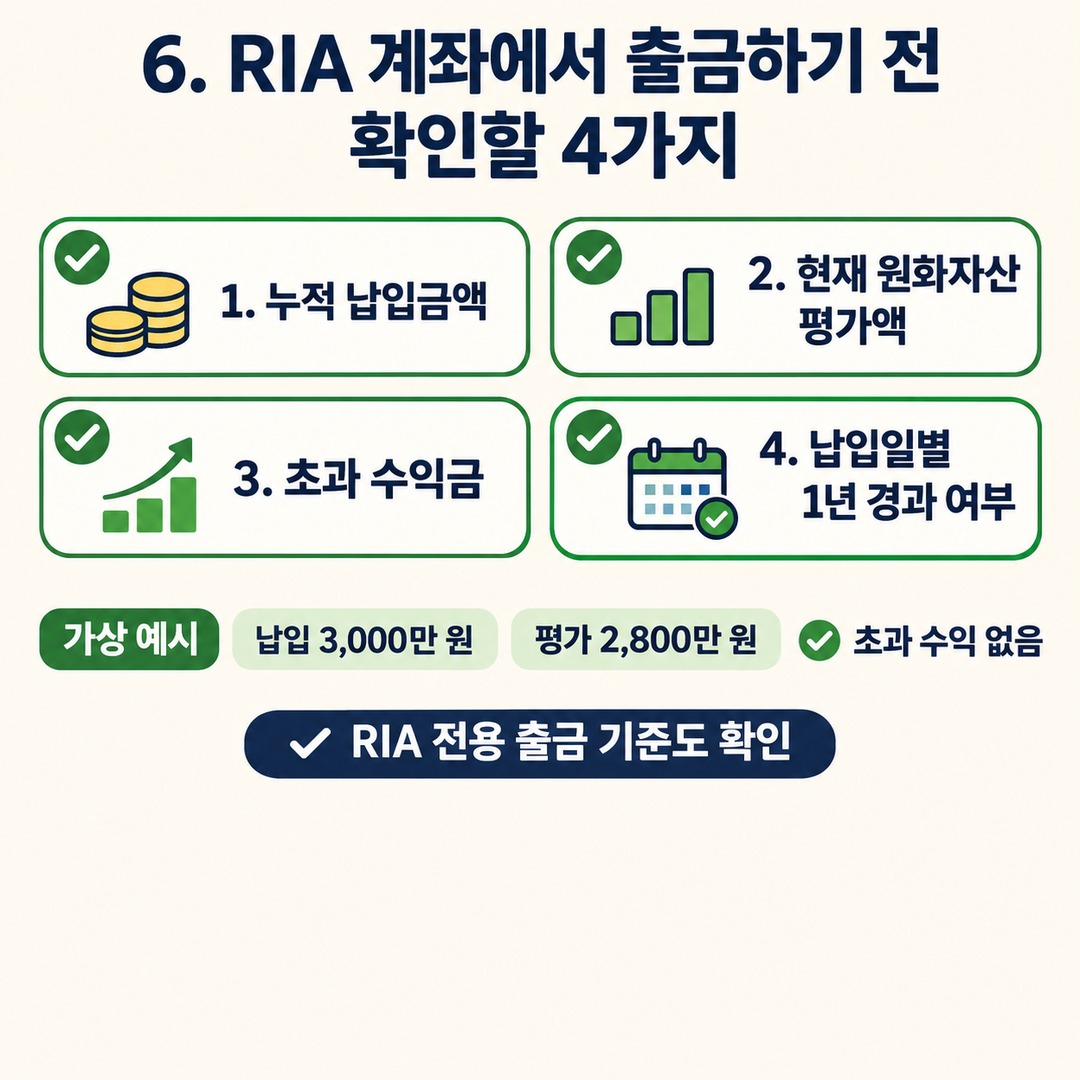
6. 4 things to check before withdrawing from an RIA account
Before making an actual withdrawal, it is a good idea to check the following.
1. Cumulative contributions: Check the total amount deposited in Korean won after selling overseas stocks.
2. Current valuation of Korean won assets: Check the valuation of cash, domestic stocks, and domestic stock funds.
3. Excess profits: Check the amount remaining after subtracting cumulative contributed principal from the valuation.
4. Whether 1 year has passed for each contribution date: Check whether any contributed principal is still within its first 1 year.
In particular, if stock prices fall, the amount of profit available for withdrawal also decreases.
For example, if cumulative contributions are KRW 30,000,000 and the current valuation is KRW 28,000,000, there are no excess profits.
If KRW 2,000,000 is insufficient at that point, withdrawing principal could jeopardize the tax benefits.
Check the RIA-specific withdrawal rules as well; do not rely only on the amount shown as available for withdrawal in the securities firm’s app.
---
In closing: An RIA account distinguishes between profits and principal
An RIA account does not require all funds to remain locked away unconditionally for 1 year.
The 1-year holding requirement applies to contributed principal, but investment profits exceeding that principal may be withdrawn under the law.
Conversely, if you need principal, even a partial withdrawal before 1 year has passed could affect the tax benefits.
If you used an RIA in 2026, it is important to keep track of each contribution date and withdrawal in advance instead of waiting until the 2027 capital gains tax filing period.
*This article was prepared based on the laws and securities firms’ publicly available guidance as of 2026-11-15. Actual withdrawals and tax treatment may vary depending on the account terms and each individual’s transaction history.*