

How to Apply for 2026 Small Business Policy Fund Loans Through Financial Institutions: From Eligibility Certificate to Bank Review
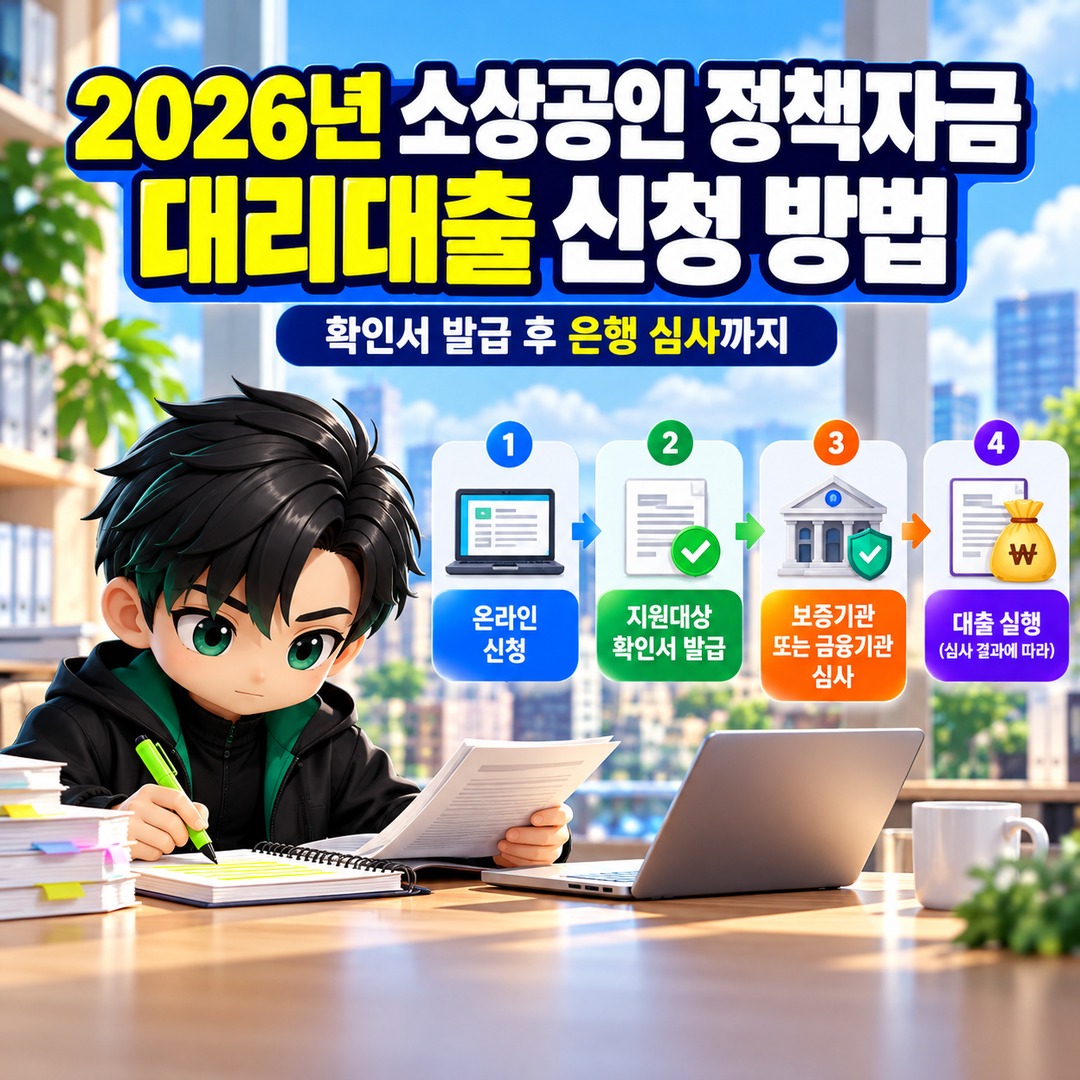
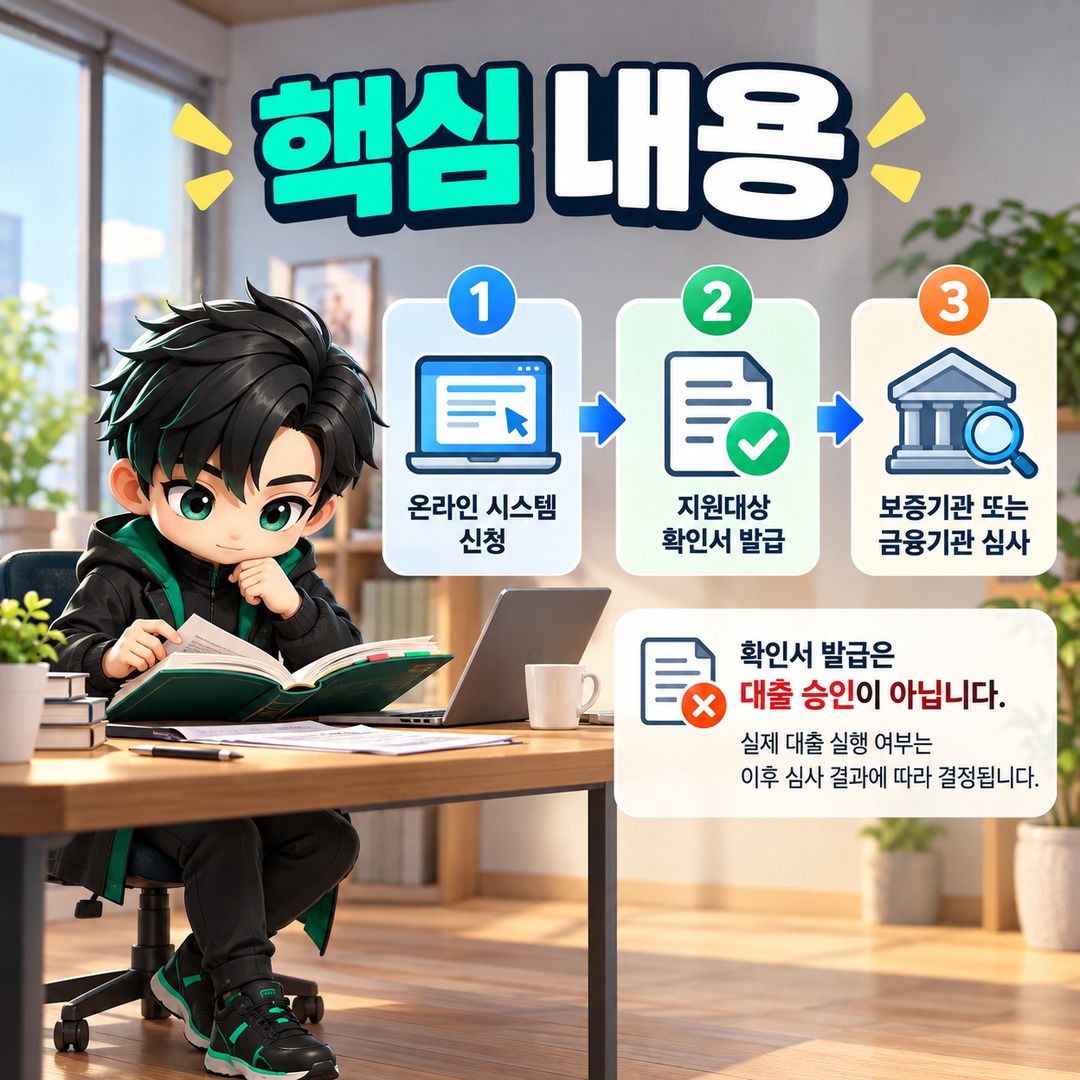
2026 small business policy fund loans through financial institutions are applied for through the online Small Business Policy Funds system. Applicants obtain an eligibility confirmation certificate and then undergo a review by a guarantee institution or financial institution. Issuance of the certificate does not constitute loan approval, and whether the loan is ultimately disbursed depends on the subsequent review results.
As of 2026-10-18, the most important part of the application process is not visiting a bank immediately, but first identifying the type of funding being requested and the applicable loan method.
In particular, because the procedures differ between credit- or collateral-backed loans and loans secured by guarantee certificates, applicants must identify which route applies to them.
Where Can You Apply for 2026 Small Business Policy Fund Loans Through Financial Institutions?
Applications for loans through financial institutions are submitted through the online Small Business Policy Funds system operated by the Korea SMEs and Startups Agency's Small Enterprise and Market Service (SEMAS).
According to the Ministry of SMEs and Startups' 2026 support program guidance, policy fund applications are generally submitted online, while application schedules for individual funding programs are announced separately on the policy funds website.
The application process is as follows.
1. Visit the Small Business Policy Funds website (ols.semas.or.kr).
2. Check which policy funding programs are currently accepting applications and review their eligibility requirements.
3. Determine whether the funding program you wish to apply for uses the financial institution-mediated loan method.
4. Enter the required information and submit the necessary documents during the online application process.
5. Complete the eligibility verification process conducted by SEMAS.
6. After receiving the eligibility confirmation certificate, proceed with the subsequent procedures at a guarantee institution or participating financial institution.
However, not all policy funding programs accept applications throughout the year. Availability must be determined based on the application notices for each funding program.
As of 2026-10-18, it has not been separately confirmed whether applications are currently open for individual funding programs or how much funding remains available.
Does Receiving an Eligibility Confirmation Certificate Mean the Loan Has Been Approved?
A Small Business Policy Fund Eligibility Confirmation Certificate Is Not Final Loan Approval.
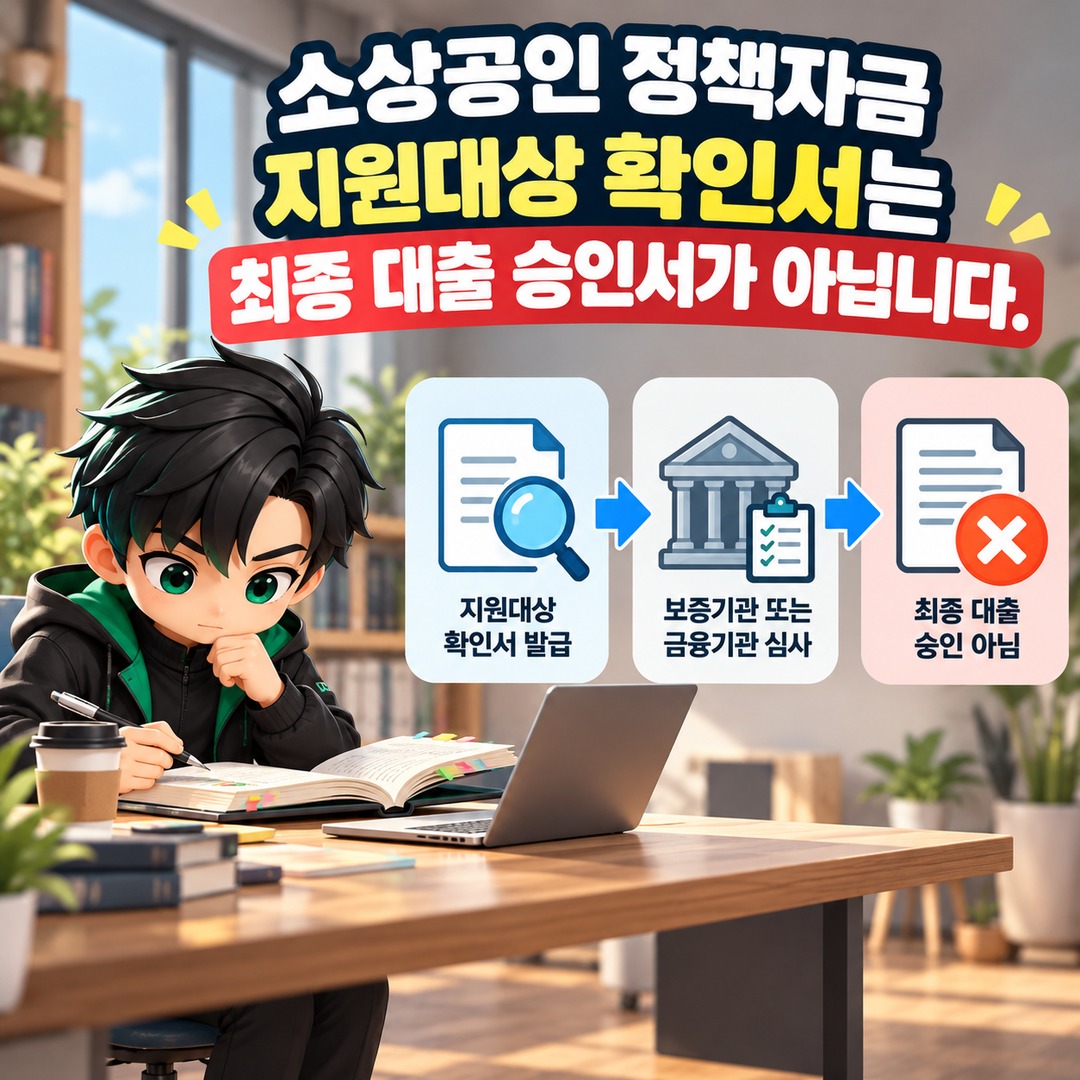
SEMAS verifies whether an applicant qualifies for policy funding support. For loans arranged through financial institutions, the guarantee institution or financial institution subsequently conducts the relevant loan review.
Therefore, even if SEMAS issues an eligibility confirmation certificate, the loan may not be disbursed depending on the bank's review results.
Understanding the responsibilities of each institution makes the process easier to follow.
| Institution | Main Responsibility |
|---|---|
| Small Enterprise and Market Service (SEMAS) | Verifies eligibility for policy funding support |
| Guarantee institution | Reviews whether a guarantee certificate can be issued |
| Participating financial institution | Conducts loan reviews and disburses loans |
A guarantee institution is not a mandatory step for every applicant.
The process differs depending on whether the applicant obtains a loan secured by a guarantee certificate or a loan backed by creditworthiness or real estate collateral.
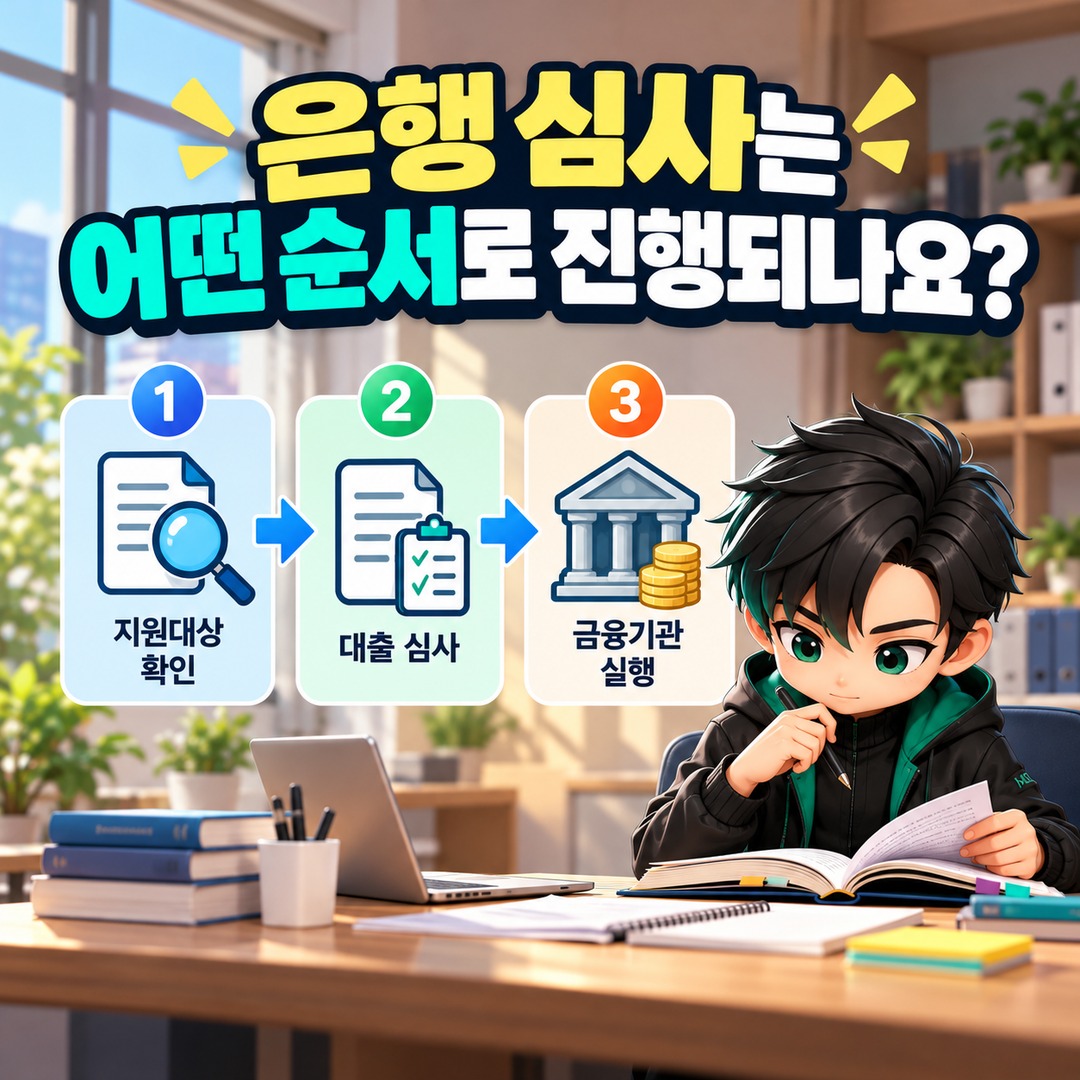
What Is the Sequence of the Bank Review Process?
The basic structure of 2026 policy fund loans through financial institutions consists of three stages: eligibility verification, loan review, and loan disbursement by a financial institution.
However, the institution responsible for the actual review depends on the loan method.
Loans Using Guarantee Certificates
For loans secured by guarantee certificates, a guarantee institution reviews whether to provide a guarantee after SEMAS verifies the applicant's eligibility.
Once the guarantee institution issues a guarantee certificate, the financial institution proceeds with the loan disbursement process using that certificate as security.
The overall process is as follows.
SEMAS eligibility verification → Guarantee institution review and issuance of guarantee certificate → Loan disbursement by financial institution
The guarantee institution's review results are important because whether a guarantee certificate is issued determines whether the subsequent loan process can proceed.
Credit-Based or Real Estate-Secured Loans
For credit-based or collateral-backed loans, the financial institution reviews whether to approve the loan after SEMAS verifies the applicant's eligibility.
Instead of the guarantee certificate issuance process, the bank's loan review becomes the central step.
The process is as follows.
SEMAS eligibility verification → Financial institution loan review → Loan disbursement based on creditworthiness or real estate collateral
Therefore, not every applicant for a financial institution-mediated policy loan undergoes the same sequence of reviews by a guarantee institution and a bank.
What Do Banks Review?
Financial institutions participating in these policy loan programs conduct their own loan reviews separately from SEMAS's eligibility verification.
During the actual review, factors such as the applicant's credit status, existing debts, business-related documentation, repayment capacity, and collateral conditions may be examined. However, specific assessment criteria and required documents vary depending on the financial institution and loan method.
Before consulting a bank, applicants should check the following.
Whether the financial institution handles the policy funding program they wish to apply for
Whether the loan product requires a guarantee certificate
Whether business registration and sales-related documents are required
Whether additional documentation concerning existing loans or debts must be submitted
Whether the financial institution imposes collateral requirements
What procedures are required for loan review and disbursement
The loan limit stated in a policy funding announcement must be distinguished from the amount actually approved.
Whether an individual applicant ultimately receives a loan and the amount disbursed may vary according to the relevant review results.
Which Funding Programs Offer 2026 Loans Through Financial Institutions?
The 2026 policy funding plan includes programs operated through financial institution-mediated loans, such as the General Management Stabilization Fund, Youth Employment-Linked Fund, Support Fund for Businesses Owned by Persons with Disabilities, and the General Type of the Specialized Fund for Small Manufacturers.
Eligibility requirements, interest rates, loan periods, and limits differ by funding program.
For example, the main conditions presented in the initial 2026 funding plan are as follows.
| Funding Program | Announced Loan Limit | Loan Period |
|---|---|---|
| General Management Stabilization Fund | 7 thousand won annually | Within 5 years |
| Youth Employment-Linked Fund | 7 thousand won | Within 5 years |
| Support Fund for Businesses Owned by Persons with Disabilities | KRW 100,000,000 | Within 7 years |
| Specialized Fund for Small Manufacturers, General Type | Working capital: KRW 100,000,000; Facilities: KRW 500,000,000 | Working capital: 5 years; Facilities: 8 years |
The amounts above are the limits stated in the official announcement and do not represent the amounts approved for individual applicants. Applicants must also check whether existing outstanding loan balances are included in the limits and whether additional restrictions apply to each funding program.
In particular, the loan methods differ between the General Type and Promising Type of the Specialized Fund for Small Manufacturers. Under the 2026 funding plan, the General Type is classified as a financial institution-mediated loan, while the Promising Type is classified as a direct loan.
This means that even subcategories within the same policy funding program may follow different procedures after application.
What Is the Difference Between Direct Loans and Loans Through Financial Institutions?
The biggest difference between the two methods is which institution reviews and disburses the loan.
For direct loans, SEMAS handles the entire process, from application submission to review, evaluation, loan agreement, and disbursement.
By contrast, for loans through financial institutions, SEMAS verifies eligibility for policy funding support, while the loan is disbursed through a financial institution.
| Category | Direct Loans | Loans Through Financial Institutions |
|---|---|---|
| Application and Submission | SEMAS | SEMAS |
| Main Review | SEMAS review and evaluation | Guarantee institution or financial institution |
| Loan Disbursement | SEMAS | Financial institution |
Therefore, rather than assuming that direct loans or loans through financial institutions are universally more advantageous, applicants should first check the eligibility requirements and financing method of the funding program they wish to apply for.
What Should You Do If a Bank Rejects Your Loan Application?
If a loan is not disbursed following the bank's review, it is advisable to first contact the financial institution to ask about the review results and any additional matters that need clarification.
Because SEMAS eligibility verification and bank loan approval are separate processes, receiving an eligibility confirmation certificate does not, by itself, change the bank's review decision.
Applicants who wish to approach another financial institution must also verify whether that institution handles the relevant policy funding program and review its application requirements.
For loans secured by guarantee certificates, the guarantee institution's review results should also be examined.
In particular, it is advisable to check the validity period of the eligibility confirmation certificate, the application status of the funding program, and whether the financial institution requires additional documents before deciding on the next steps.
What Should You Check Before Applying?
When preparing to apply for 2026 small business policy fund loans through financial institutions, it is important not to treat the online application system and the bank's loan review as a single procedure.
This is because a separate decision by a guarantee institution or financial institution is still required even after an applicant passes SEMAS's eligibility verification.
Before applying, applicants should prioritize the following three checks.
First, confirm whether the desired funding program is currently accepting applications.
Second, determine whether the funding program offers direct loans or loans through financial institutions.
Third, if the program uses loans through financial institutions, check whether the loan is secured by a guarantee certificate or based on creditworthiness or collateral, and ask the participating financial institution about the necessary procedures.
For questions about policy funding applications and procedures, applicants can contact the Integrated SME Call Center at 1357 or the Policy Funds Call Center at 1533-0100.
The most important distinction in loans through financial institutions is between eligibility verification and actual loan approval. After obtaining an eligibility confirmation certificate, applicants must also identify which institution will conduct the next review and what that review involves to proceed correctly with loan disbursement.