

October 2026 VAT Preliminary Notice: Do You Have to Pay If You Switched from Simplified to General VAT Taxation in July?
Businesses that switched from simplified VAT taxation to general VAT taxation in 2026-07-01 are generally excluded from the October VAT preliminary tax notice. However, not receiving a preliminary notice is not the same as having no obligation to file a VAT return. You need to distinguish between the conversion date and the applicable tax periods to avoid mistakes in your next filing.
If you switched to general VAT taxation for the first time this year, checking the sales and purchase records to be included in the January 2027 final VAT return is more important than whether you receive a October preliminary notice.
*Verification basis: 2026-10-17 / South Korea's National Tax Service VAT guidance*
1. Switching to General VAT Taxation in July 1 Generally Excludes You from the October Preliminary Notice
South Korea's National Tax Service (NTS) states that businesses switching from simplified to general VAT taxation as of the first day of a tax period are excluded from VAT preliminary tax notices.
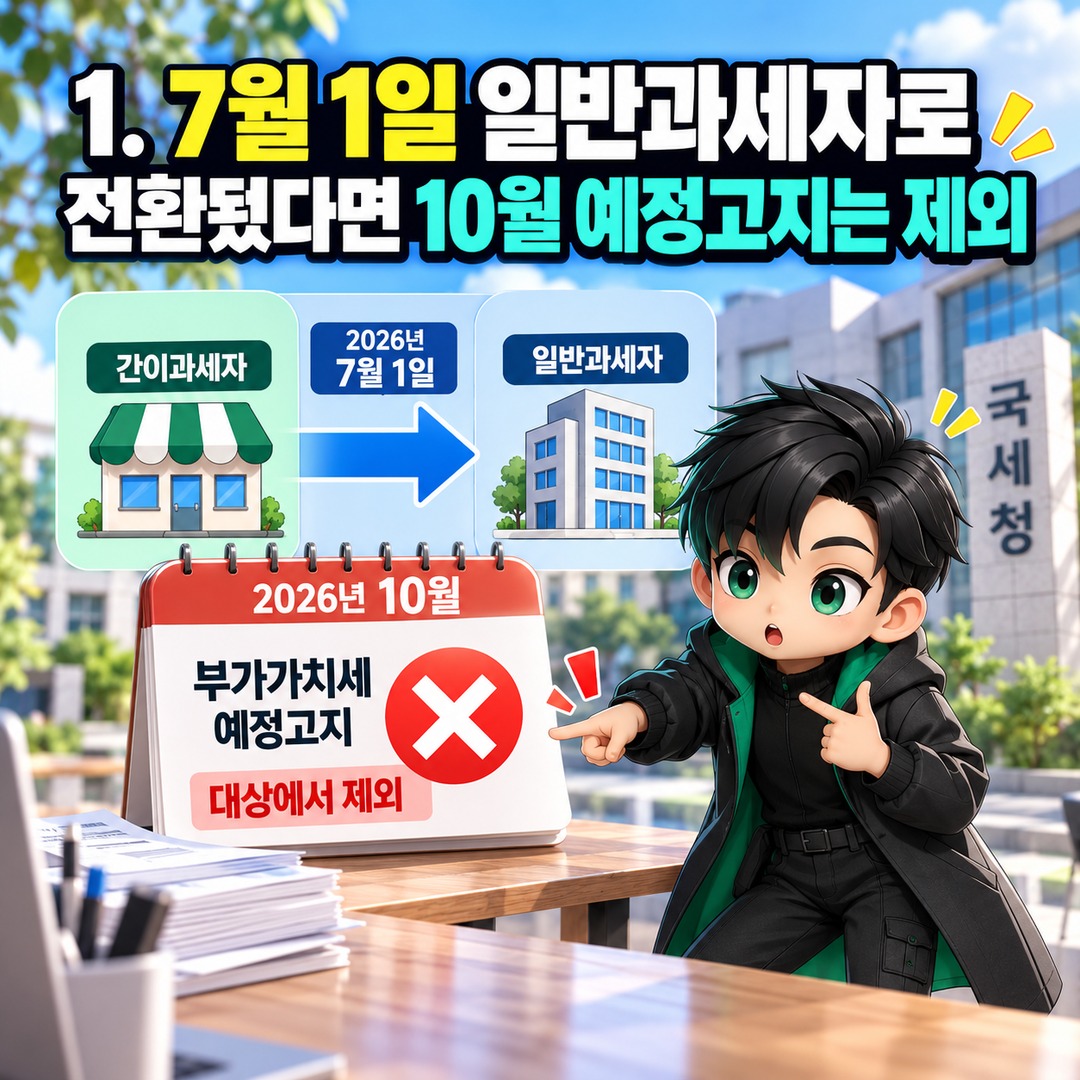
The second VAT tax period of 2026 runs from July 1 through December 31.
Therefore, if your conversion to general VAT taxation took effect on 2026-07-01, you are generally excluded from the October preliminary notice.
The important factor is not simply that your business became subject to general VAT taxation, but when the conversion took effect.
| Business situation | October preliminary notice assessment |
|---|---|
| Switched from simplified to general VAT taxation in 2026-07-01 | Generally excluded |
| Continued operating under general VAT taxation from an earlier period | Determined according to other applicable conditions |
| Newly established business in the second half of 2026 | Check the tax period applicable to newly established businesses |
| Unclear VAT classification conversion date | Business registration status must be verified |
Do not assume that your tax obligations have ended simply because no notice arrived without first verifying the exact date your business switched to general VAT taxation.
2. If There Is No Preliminary Notice, Can You Also Skip Filing in October?
Individual business operators who switched to general VAT taxation in July 1 generally do not have to file a preliminary VAT return in October either.
This is because individual business operators under general VAT taxation normally file final VAT returns twice per 1 year, while those subject to preliminary notices pay the assessed tax instead of submitting a separate preliminary return.
However, whether a preliminary return is required may vary depending on the type of business and individual circumstances.
The distinctions are as follows.
Preliminary tax notice: The tax office issues a notice specifying the tax amount it has calculated.
Preliminary VAT return: The business directly reports its transactions for the relevant preliminary filing period.
Final VAT return: The business reconciles sales and purchases for the entire tax period.
Therefore, even if you did not receive a preliminary notice in October, transactions conducted under general VAT taxation during the second half of 2026 must be included in the next final VAT return.
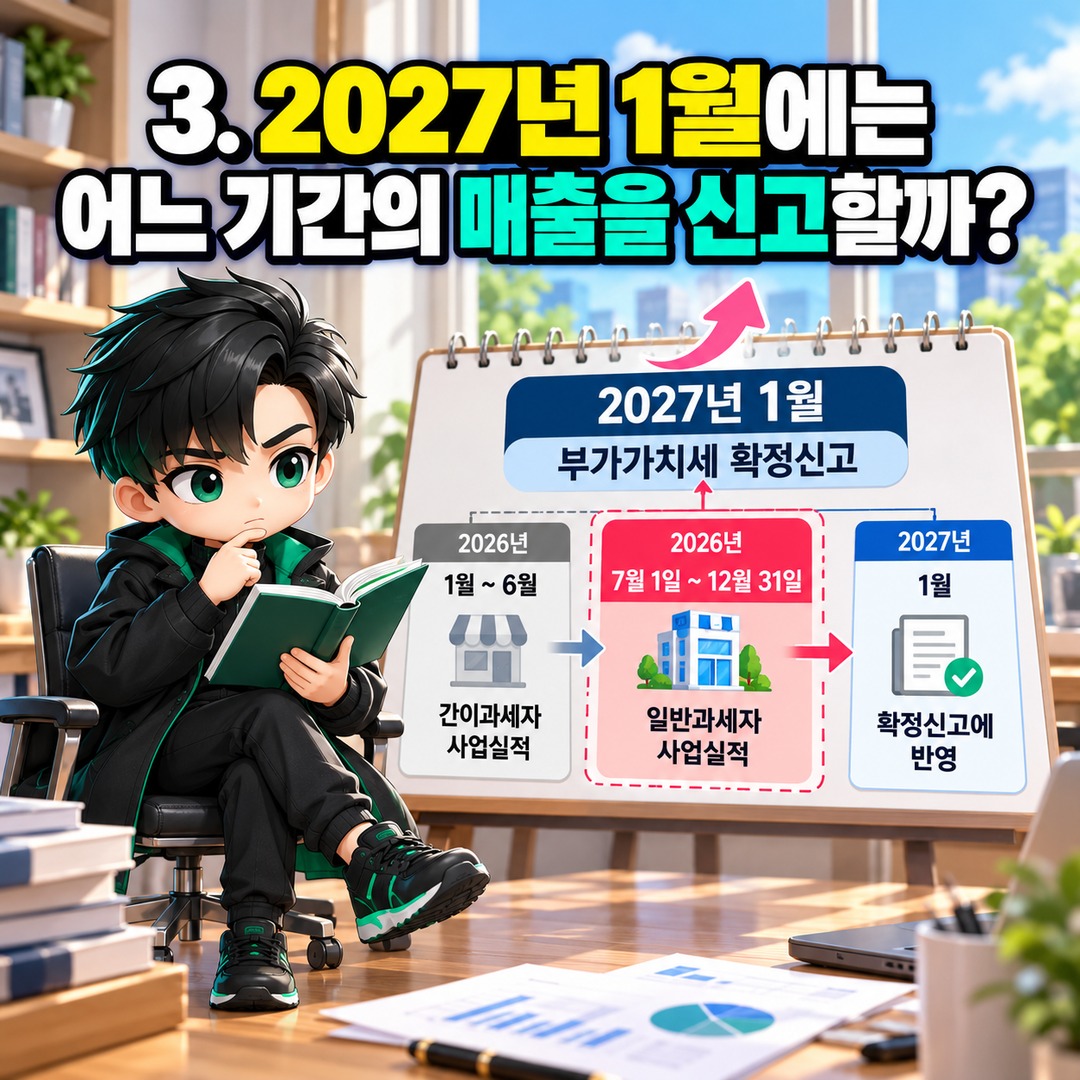
3. Which Period's Sales Should Be Reported in January 2027?
Businesses that switched to general VAT taxation in 2026-07-01 generally include their business activity under general VAT taxation from 2026-07-01 through December 31 in the January 2027 final VAT return.
One easily overlooked issue is the simplified VAT taxation period before the conversion.
According to NTS guidance, businesses that switched from simplified to general VAT taxation in July 1 must file a separate return in July for the preceding simplified VAT taxation period, running from January 1 through June 30.
| Classification | Tax period | Filing time |
|---|---|---|
| Simplified VAT taxation period before conversion | 2026.1.1.–6.30. | July 2026 |
| General VAT taxation period after conversion | 2026.7.1.–12.31. | January 2027 |
In other words, you should not combine all sales from 2026 into a single general VAT return covering the entire year.
You must separate the tax periods before and after conversion and verify that the respective returns have been properly processed.
4. Does the VAT Calculation Change When You Switch to General VAT Taxation?
Yes. Under general VAT taxation, the tax payable is generally calculated by subtracting deductible input VAT from output VAT on sales.
The VAT rate of 10% applies to ordinary taxable transactions.
For example, suppose the following transactions occurred during the second half of 2026.
Sales excluding VAT: KRW 30,000,000
Output VAT: KRW 3,000,000
Purchases excluding VAT: KRW 15,000,000
Deductible input VAT: KRW 1,500,000
Example of Calculating VAT Payable Under General VAT Taxation
Output VAT
KRW 3,000,000
Deductible input VAT
−KRW 1,500,000
Estimated VAT payable
KRW 1,500,000
Author's calculation. This is a simplified example assuming there are no other deductions, additional taxes, or previously paid tax amounts.
In an actual VAT return, not all purchases qualify for an input VAT deduction.
Expenses unrelated to the business and input VAT that is legally non-deductible must be excluded. You should also verify whether the supporting documents meet the requirements and whether the purchases are related to taxable business activities.
In particular, estimating VAT after conversion using only the calculation method that applied under simplified VAT taxation may produce a figure that differs from the actual amount payable.
5. How to Check Your General VAT Conversion Date and Filing History in Hometax
The first things to verify are your current VAT classification and the effective conversion date.
You can review your business registration information through the NTS Hometax service and, if necessary, check your current VAT classification using a business registration certificate or related documentation.
Follow these steps.
1. Visit National Tax Service Hometax and sign in.
2. In the business registration section, check the registration status and VAT classification of the relevant business.
3. Verify the effective date of conversion to general VAT taxation.
4. Check your VAT filing history to confirm whether the return for the first half of 2026 was processed.
5. Organize your sales and purchase records for the second half of 2026 separately.
Hometax menu names and locations may change as the service is updated.
If you cannot verify the VAT classification conversion date or your actual tax notices differ from the general rules, the most reliable approach is to contact your jurisdictional tax office or the National Tax Consultation Center at 126.
6. Situations That Still Require Attention Even Without a October Preliminary Notice
Being excluded from preliminary tax notices does not mean that every business has identical tax filing obligations.
The following situations require additional verification.
First, You Failed to File a Return for the Simplified VAT Taxation Period
Businesses that switched to general VAT taxation in July 1 must verify their filing obligations for the preceding simplified VAT taxation period. Switching to general VAT taxation does not eliminate earlier filing obligations.
Second, Your Business Registration Information Does Not Match the Actual Conversion Date
You should compare the VAT classification conversion notice with your business registration records. The fact that your business is currently classified under general VAT taxation does not, by itself, establish that the conversion took effect in July 1.
Third, You Closed Your Business
Businesses that have closed are subject to different final VAT filing deadlines from businesses that continue operating.
According to the NTS, the deadline for filing and paying VAT following business closure is generally the 25 day of the month following the month in which the business closed.
Therefore, if you closed your business, check the filing deadline based on your closure date rather than waiting until January 2027.
7. Frequently Asked Questions
Q. Does Switching from Simplified to General VAT Taxation Always Mean You Will Not Receive a Preliminary Notice?
No. The exclusion described by the NTS applies to businesses that switched from simplified to general VAT taxation as of the first day of the tax period. For the October 2026 preliminary notice, whether the conversion took effect in July 1 is an important determining factor.
Q. If There Is No October Preliminary Notice, Does That Mean No VAT Will Be Payable in January 2027?
No. Exclusion from a preliminary notice means that no advance tax assessment is issued during the interim period. VAT may still be payable when the final return is filed, depending on business activity during the second half of the year.
Q. Can I Deduct VAT on Goods Purchased Before Switching to General VAT Taxation?
When switching from simplified to general VAT taxation, inventory and depreciable assets held at the time of conversion may qualify for an inventory-related input VAT deduction if the statutory requirements are met. However, not all previous purchases automatically qualify. You must separately verify the eligible assets, supporting documentation, and filing requirements.
8. Ultimately, the Conversion Date and Next VAT Return Matter More Than the October Notice
If you switched from simplified to general VAT taxation in 2026-07-01, you are generally excluded from the October preliminary tax notice.
However, this does not mean your VAT is exempt.
More importantly, you need to confirm whether you completed the return for the simplified VAT taxation period in the first half of 2026 and properly separated sales and purchases for the general VAT taxation period in the second half.
When preparing the January 2027 final VAT return, it is advisable to review not only sales revenue but also deductible input VAT and the possibility of inventory-related deductions at the time of conversion.
Final eligibility and filing obligations must be determined based on each business's actual VAT classification conversion date and filing history.