

2026 Youth Future Savings Account 2th Application Round: Open the New Account Before Switching from the Youth Leap Account
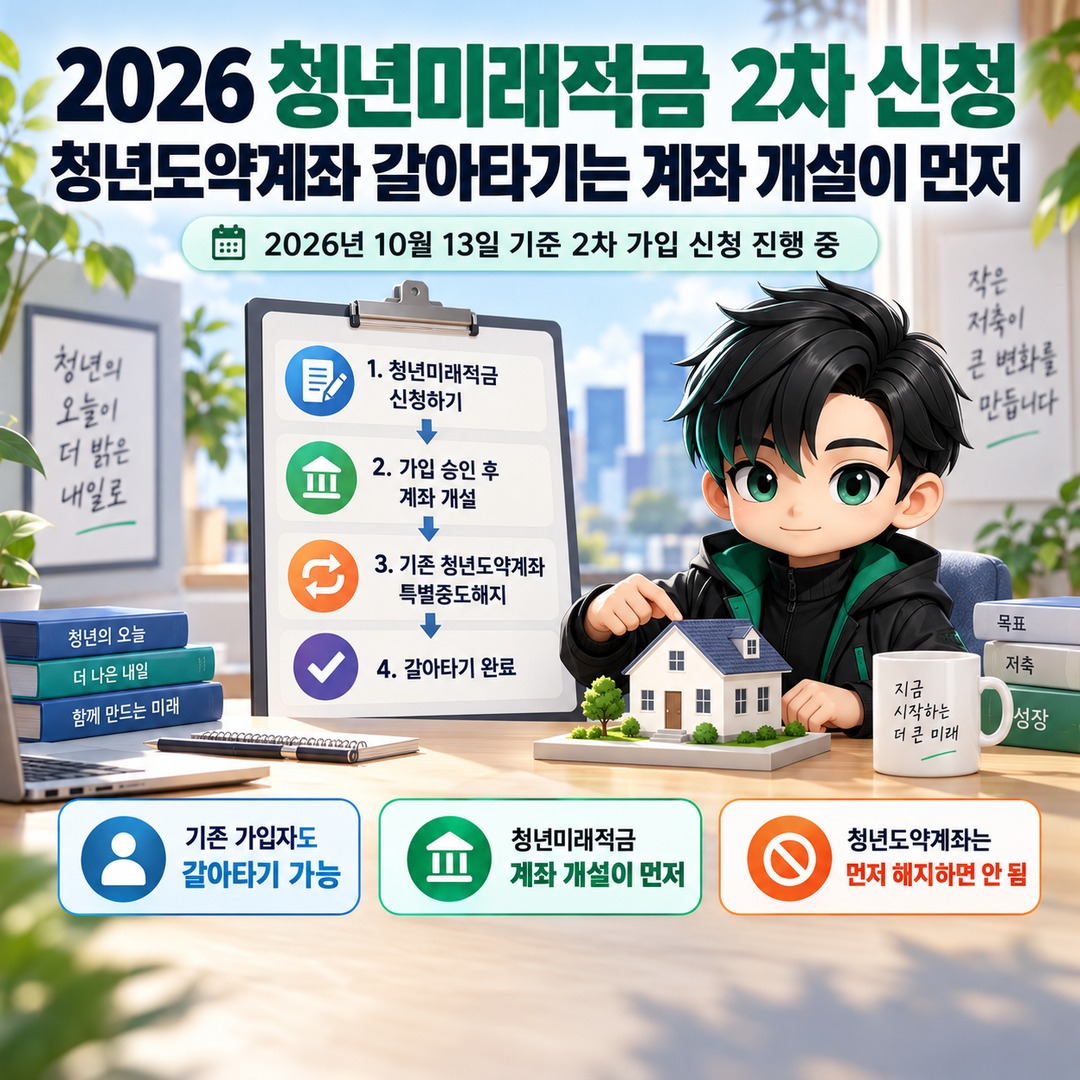
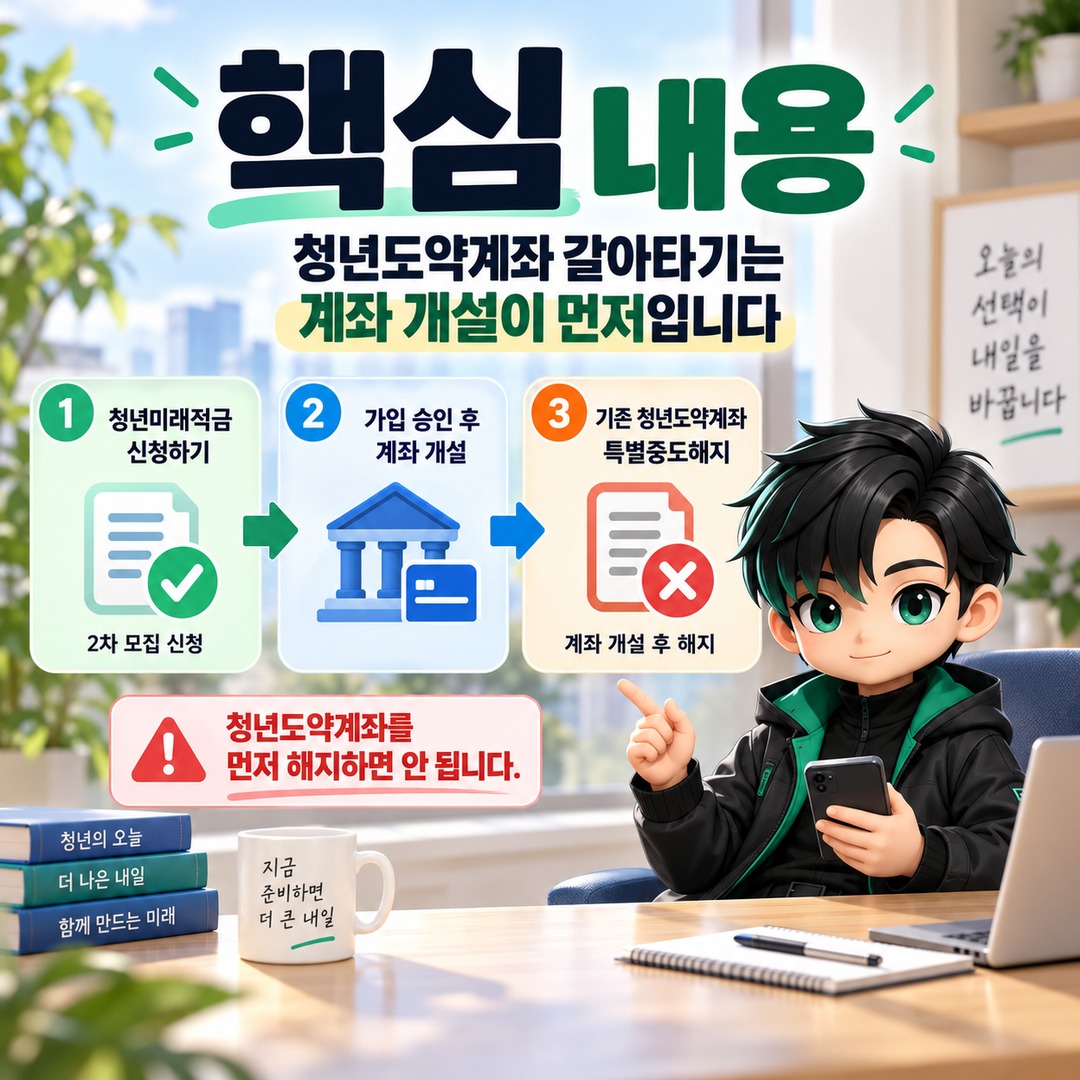
During the 2th application round for the Youth Future Savings Account in 2026, existing Youth Leap Account holders can switch if they meet the eligibility requirements. However, they must not close their Youth Leap Account first. They must receive approval for the Youth Future Savings Account and open the new account before applying for a special early termination of their existing Youth Leap Account.
As of 2026-10-13, applications for the 2th round are underway, with the application deadline set for October 16. Account opening and switching will take place from November 16 through 27.
Can Existing Youth Leap Account Holders Switch During the 2th Application Round?
Yes. In its announcement on 2026-09-30, the Financial Services Commission stated that existing Youth Leap Account holders would receive an additional opportunity to switch to the Youth Future Savings Account.
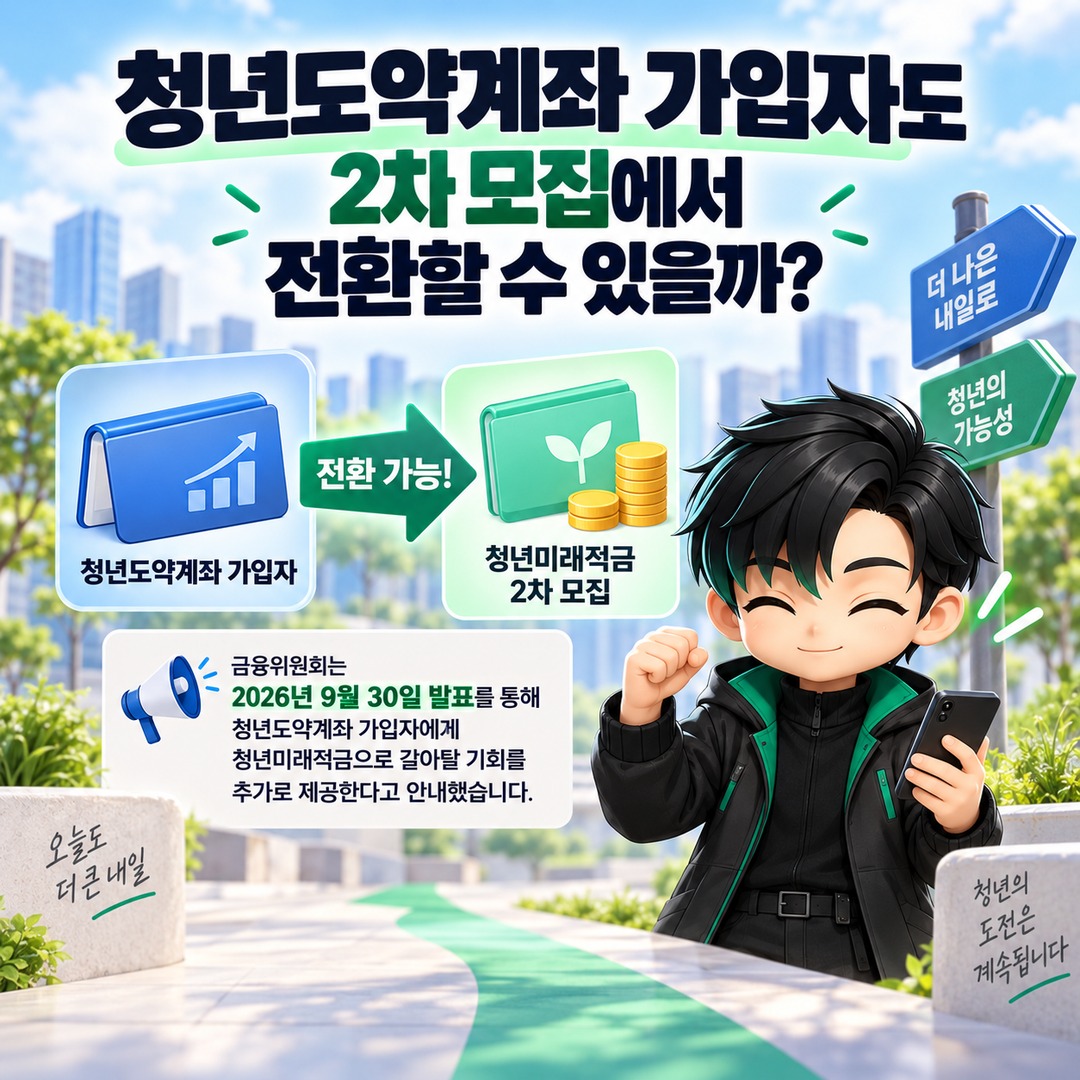
Existing Youth Leap Account holders must meet the Youth Future Savings Account's eligibility requirements, including age and income criteria, and pass the screening process before they can switch.
As a general rule, simultaneous enrollment in both products is restricted. Therefore, account holders cannot continue maintaining their existing account while making contributions to the Youth Future Savings Account at the same time.
Additionally, individuals who have already maintained their Youth Leap Account until its 5-year maturity are not eligible to switch to the Youth Future Savings Account.
The most important distinction under this arrangement is that special early termination for the purpose of enrolling in the Youth Future Savings Account applies, rather than an ordinary savings account closure.
What Happens to Existing Government Contributions If the Youth Leap Account Is Closed Early?
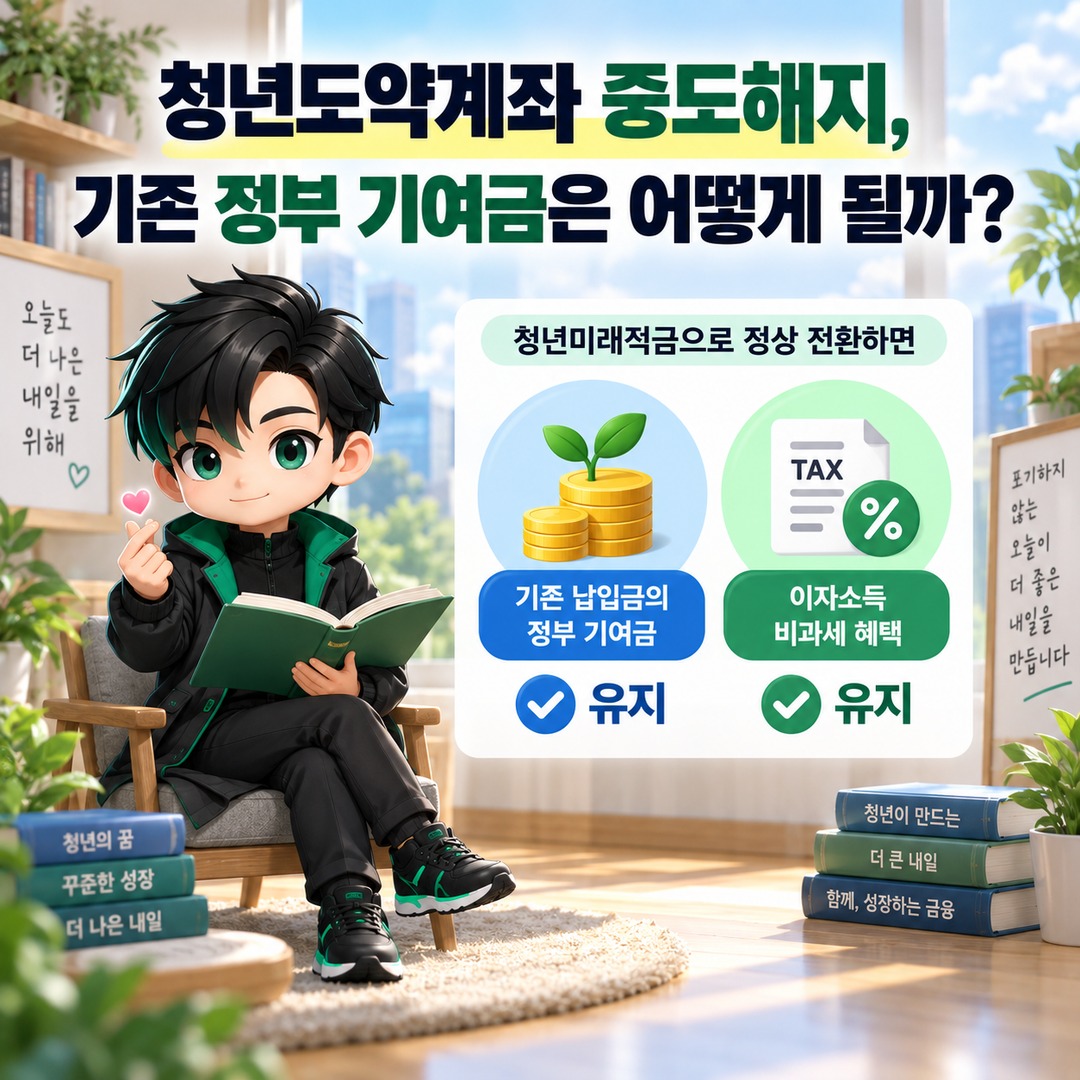
When account holders complete the switch to the Youth Future Savings Account through the prescribed procedure, the government contributions and tax-exempt interest benefits associated with their previous Youth Leap Account deposits are preserved.
The special early termination procedure announced by the Financial Services Commission is distinct from ordinary early termination.
| Category | Switching to the Youth Future Savings Account |
|---|---|
| Closure of existing account | Special early termination |
| Government contributions | Benefits on previous deposits are preserved |
| Tax exemption on interest income | Benefits on previous deposits are preserved |
| Timing of account closure | After opening the Youth Future Savings Account |
| Proceeds from closing the existing savings account | Lump-sum deposits into the Youth Future Savings Account are not permitted |
The key point to watch is the order in which special early termination is carried out.
If an account holder closes their existing Youth Leap Account before receiving approval to enroll in the Youth Future Savings Account, they cannot use the prescribed switching procedure.
This is why they must first confirm their eligibility for the new product while keeping their existing account open.
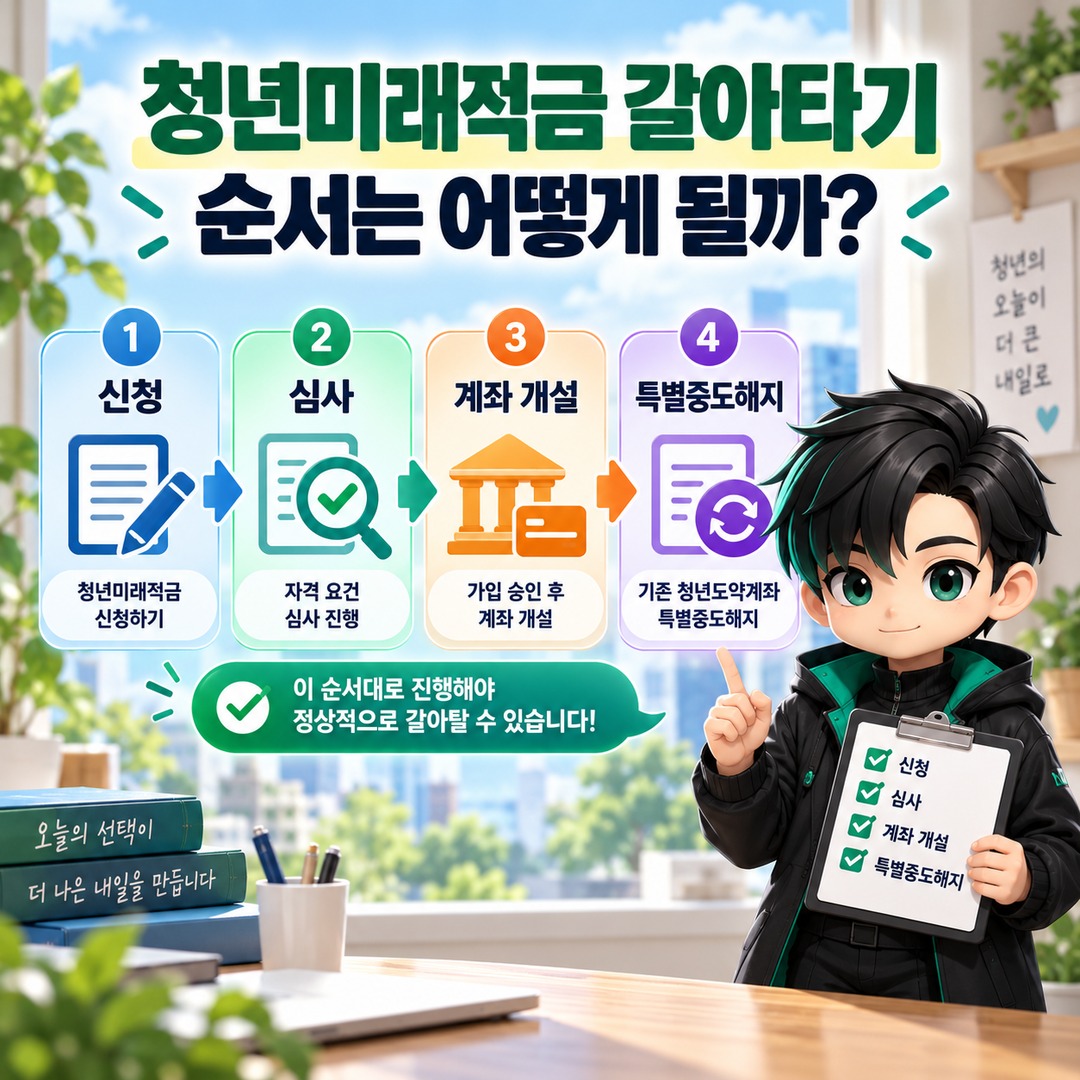
What Is the Correct Procedure for Switching to the Youth Future Savings Account?
To switch from the Youth Leap Account to the Youth Future Savings Account, account holders must complete the process in the following order: application, eligibility screening, account opening, and special early termination.
Step 1. Apply by October 16
Submit an application through the mobile app of a financial institution offering the Youth Future Savings Account. Keep the existing Youth Leap Account open.
Step 2. Eligibility Screening
Income and enrollment category, among other factors, will be reviewed from October 19 through November 13. Final results are expected to be communicated individually on November 12–13.
Step 3. Open the Youth Future Savings Account
After receiving confirmation of eligibility, open the new account between November 16 and 27.
Step 4. Special Early Termination of the Youth Leap Account
After opening the new account, apply for special early termination of the existing Youth Leap Account for the purpose of enrolling in the Youth Future Savings Account. This must be done within the same period through the mobile app of the bank managing the existing Youth Leap Account.
Step 5. Begin Contributions to the Youth Future Savings Account
Contributions to the Youth Future Savings Account can begin from 9 a.m. on the next business day after special early termination has been completed.
Even if the Youth Future Savings Account has been opened, contributions cannot be made unless special early termination of the Youth Leap Account is completed within the designated period.
If the switching process is not completed, the existing Youth Leap Account remains active, and the Youth Future Savings Account with suspended contributions must be closed.
2026 2th Application Schedule and Eligibility Requirements
Applications for the 2th round of the Youth Future Savings Account will be accepted from 2026-10-07 through 16. From October 12 through 16, applicants may apply regardless of their birth year.
| Category | Schedule |
|---|---|
| 2th application round | October 7–16 |
| Enrollment and income screening | October 19–November 13 |
| Preliminary screening results | October 30–November 2, tentative |
| Appeals | November 2–5, tentative |
| Final results notification | November 12–13, scheduled |
| Account opening and switching | November 16–27 |
Applications and account openings must be completed within the designated periods. Applications are accepted on business days, excluding Saturdays, Sundays, and public holidays. Screening schedules may change depending on the progress of the review process.
Eligible Age and Income Requirements
The basic eligibility age for the 2th application round in 2026 is 19–34 years old.
Eligibility covers individuals born from 1991-11-17 through 2007-11-27, based on their age on the account opening date. Up to 6 years of military service may be excluded when calculating age.
The income requirements are as follows.
Individual gross salary of KRW 75,000,000 or less, or comprehensive income of KRW 63,000,000 or less
For small business owners, an annual sales threshold of KRW 300,000,000 or less applies
Household income at or below 200% of the median household income
Income screening based on finalized income for 2025
However, meeting the income requirements does not mean that every applicant receives the same government contribution.
General-income applicants with gross salaries exceeding KRW 60,000,000 but not exceeding KRW 75,000,000 may receive tax-exempt benefits if they meet the enrollment requirements, but they are excluded from government contribution payments.
Additionally, enrollment is restricted for individuals who were subject to comprehensive taxation on financial income at least once during the preceding 3 tax years.
How Much Could You Receive by Switching to the Youth Future Savings Account?
The Youth Future Savings Account is a 3-year maturity product that allows flexible monthly contributions of up to KRW 500,000.
Government contributions are calculated at 6% or 12% of the amount deposited, depending on the enrollment category and income requirements.
If KRW 500,000 is deposited every month for 36 months, the account holder's total principal contributions will amount to KRW 18,000,000.
| Category | Standard Type 6% | Preferential Type 12% |
|---|---|---|
| Personal principal contributions | KRW 18,000,000 | KRW 18,000,000 |
| Government contributions | KRW 1,080,000 | KRW 2,160,000 |
| Interest assuming an 8% rate | KRW 2,300,000 | KRW 2,390,000 |
| Estimated amount at maturity | KRW 21,380,000 | KRW 22,550,000 |
These figures are based on an illustrative annual interest rate of 8% presented by the Financial Services Commission. The actual applicable interest rate will vary depending on factors such as whether the account holder meets each bank's preferential interest rate requirements.
When government contributions and tax exemptions are taken into account, the overall enrollment benefits are described as being comparable to those of a simple-interest savings account offering up to 14.4% annually for the standard type and up to 19.4% annually for the preferential type. However, this does not mean that the actual deposit interest rates themselves are 14.4% or 19.4%.
Furthermore, the maturity amount that an account holder could receive by maintaining the Youth Leap Account and the estimated amount after switching to the Youth Future Savings Account are based on different enrollment periods and contribution conditions.
Therefore, when deciding whether to switch, account holders should consider the remaining term and contribution history of their existing Youth Leap Account rather than simply comparing the advertised interest-equivalent benefits.
Can the Proceeds from Closing the Youth Leap Account Be Deposited All at Once?
The proceeds received from closing a Youth Leap Account cannot be deposited into the Youth Future Savings Account as a single lump sum.
The Youth Future Savings Account allows flexible contributions within a monthly limit of KRW 500,000.
Even if an account holder has accumulated a substantial amount in their existing Youth Leap Account, they cannot transfer the entire balance into the Youth Future Savings Account at once.
The term 'switching' may give the impression that the existing savings balance and enrollment period are transferred unchanged. In practice, however, the procedure involves specially terminating the existing account and newly enrolling in the Youth Future Savings Account.
What Happens If You Close the Youth Future Savings Account Early After Enrolling?
If the Youth Future Savings Account is terminated early, the account holder may reapply once 2 months have passed since the termination date.
However, upon re-enrollment, the government contribution rate is adjusted to reflect the previous enrollment period.
The adjustment method announced by the Financial Services Commission is as follows.
Adjustment Factor = (36 months - Previous Enrollment Period) ÷ 36 months
For example, if the previous enrollment period in the Youth Future Savings Account was 12 months, the adjustment factor would be 24 ÷ 36, or approximately 0.667.
This means that the longer the previous enrollment period, the more the government contribution rate applied after re-enrollment is adjusted. Periods during which contributions were suspended are also included in the enrollment period.
Therefore, having to close the new account because the switching procedure was not completed should not be taken lightly.
What Should You Do Before October 16?
Existing Youth Leap Account holders who wish to participate in the 2th application round for the Youth Future Savings Account must first complete their applications by October 16.
The action required now is to apply for the Youth Future Savings Account, not to close the existing Youth Leap Account.
After submitting the application, wait for the screening results. If eligibility is confirmed, open the Youth Future Savings Account between November 16–27, then complete the special early termination of the existing Youth Leap Account.
If the application process or switching requirements are unclear, contact the Korea Inclusive Finance Agency's Youth Finance Call Center at 1397 and select option 3 for guidance.