

2026 Small Business Agency Loans vs. Direct Loans: How Application Routes Differ by Business Eligibility
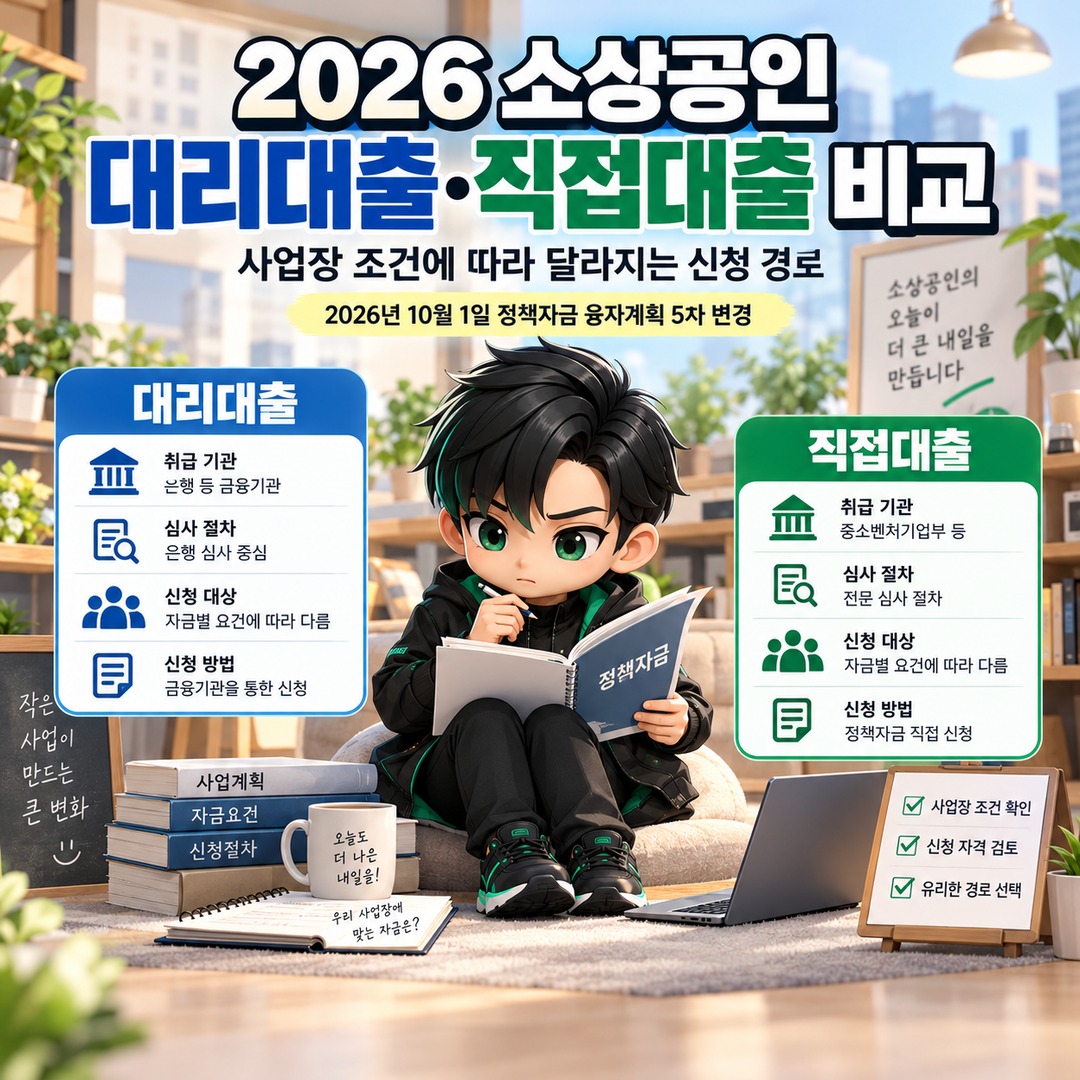
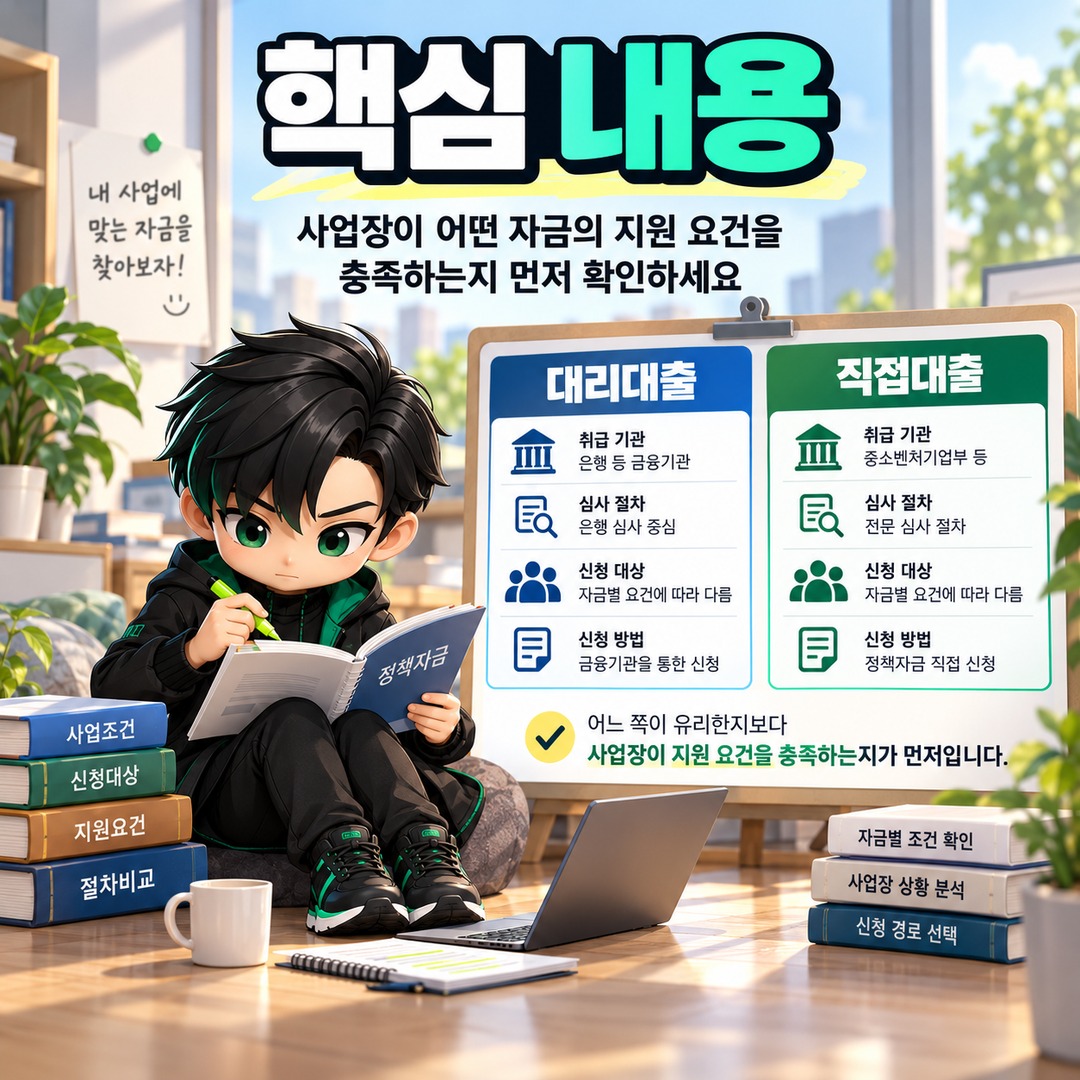
When applying for small business policy financing in 2026, business owners should first determine which funding programs their businesses qualify for, rather than simply deciding whether an agency loan or a direct loan is more advantageous. The two methods differ in their lending institutions and screening procedures, while eligibility requirements and conditions also vary by funding program.
In particular, the Ministry of SMEs and Startups' policy financing plan was revised for the 5 time in 2026-10-01, changing the interest rates and loan limits applicable to certain small businesses affected by disasters.
The funding programs that need to be considered depend on whether a business requires ordinary working capital, is experiencing financial difficulties, or has suffered disaster-related damage.
What Is the Difference Between Agency Loans and Direct Loans?
The biggest difference is which institution conducts the actual loan assessment and provides the financing.
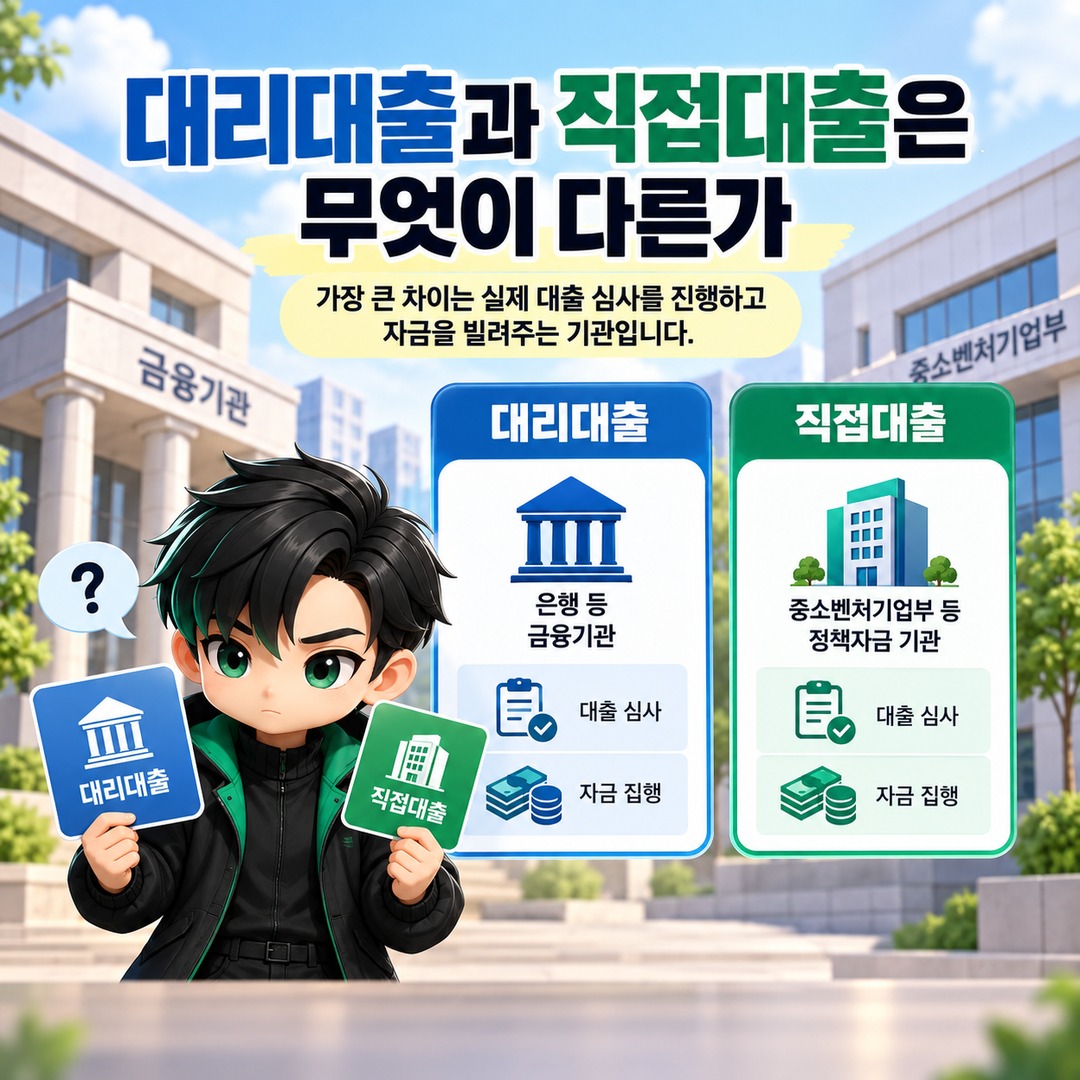
Agency loans are provided through financial institutions after applicants complete the policy financing eligibility confirmation process administered by the Korea SMEs and Startups Agency for Market Promotion (SEMAS). A guarantee assessment by a credit guarantee institution may also be required.
Direct loans are loans for which SEMAS directly handles the assessment and disbursement.
The two methods can be compared as follows.
| Category | Agency Loans | Direct Loans |
|---|---|---|
| Lending institution | Financial institution | SEMAS |
| Main assessment | Financial institution assessment and, if necessary, guarantee assessment | Direct assessment by SEMAS |
| Eligible applicants | Businesses meeting the requirements of policy financing programs operated through agency loans | Businesses meeting the requirements of policy financing programs operated through direct loans |
| Items to verify | Eligibility confirmation, guarantee assessment, and bank assessment | Program-specific requirements and SEMAS assessment |
| Loan approval | Determined by assessment results from financial institutions and other relevant organizations | Determined by SEMAS assessment results |
There is an important point to understand here.
Agency loans do not necessarily have easier screening requirements, and direct loans are not always more advantageous than bank loans.
Business owners need to consider their industry, operating conditions, intended use of funds, credit standing, and existing loans together.
What Should Businesses Check First When They Need Ordinary Working Capital?
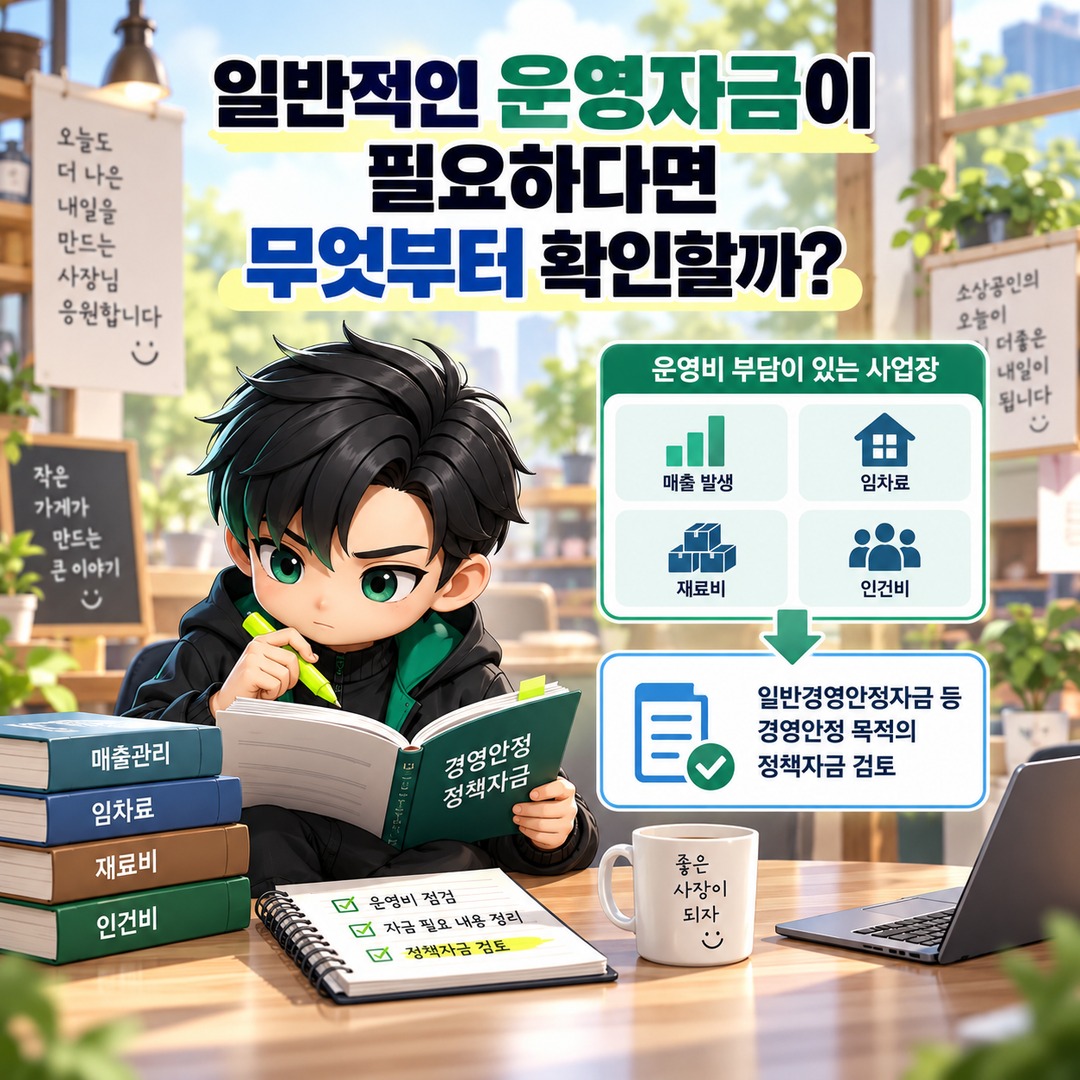
Businesses that generate sales but face operating expenses such as rent, material costs, and labor costs may first consider policy financing programs intended to stabilize business operations, including General Business Stabilization Funds.
However, needing ordinary operating funds does not automatically make a business eligible for every policy financing program.
Business owners must check each program's requirements regarding operating history, business size, excluded industries, and application availability.
For example, a restaurant or retail store owner seeking policy financing to cover operating expenses should consider the following sequence.
First, verify whether the industry listed on the business registration qualifies for small business policy financing.
Second, identify currently available business stabilization funding programs that apply to the business.
Third, determine whether the relevant program provides agency loans or direct loans.
Fourth, compare the available loan amount, repayment period, applicable interest rate, and assessment procedures.
In other words, identifying the appropriate policy financing program before choosing a lending method can help business owners make better decisions.
What If a Business Is Experiencing Declining Sales or Financial Difficulties?
Businesses experiencing temporary financial difficulties should examine the separate eligibility requirements for programs such as Emergency Business Stabilization Funds.
In particular, application eligibility should not be determined solely by whether sales have declined.
In the 4 amendment notice for small business policy financing announced on 2026-07-30, small businesses located in areas designated for preemptive employment crisis response were added to the categories eligible for an exception to the sales-decline verification requirement under the Temporary Business Difficulties Fund.
This means business owners must verify both whether their establishments are located in the relevant areas and whether they satisfy the actual applicable requirements.
They must distinguish between whether their business location falls within a designated support area and whether they meet the detailed requirements of the funding program they intend to apply for.
Furthermore, Emergency Business Stabilization Funds do not automatically approve loans for every business experiencing declining sales.
Application eligibility and loan assessment are separate procedures.
Disaster-Affected Businesses Should Check the Changes Introduced in October 2026
The 5 amendment notice announced by the Ministry of SMEs and Startups in 2026-10-01 included preferential disaster financing conditions for small businesses affected by disasters in Geoje and Tongyeong.
The conditions specified in the notice are as follows.
| Item | Details of the 5 Amendment Notice |
|---|---|
| Eligible businesses | Disaster-affected small businesses in Geoje and Tongyeong |
| Direct loan interest rate | Fixed annual rate of 1.5% |
| Agency loan interest rate | Fixed annual rate of 1.4% |
| Loan limit | KRW 300,000,000 |
| Loan term | 10 years |
These conditions are not general interest rates or loan limits applicable to all small business policy financing programs.
They are preferential conditions announced specifically for eligible disaster-affected small businesses in Geoje and Tongyeong.
Comparing interest rates alone, the annual agency loan rate of 1.4% is 0.1% percentage points lower than the annual direct loan rate of 1.5%.
However, choosing an agency loan solely because its interest rate is lower would not be appropriate.
Actual eligibility, loan assessments, and whether a guarantee is required must also be considered.
In addition, the maximum loan limit of KRW 300,000,000 stated in the notice does not mean every applicant will be approved for that amount.
Some Industries May Be Ineligible for Both Loan Methods
One of the first things to check when considering policy financing is whether the business operates in an excluded industry.
Small business policy financing does not apply equally to every registered business category.
SEMAS guidance on excluded industries includes finance, insurance, certain entertainment businesses, and gambling-related industries.
Industry-specific exceptions also exist for sectors such as real estate and healthcare.
For example, rather than treating the entire real estate industry as a single category, applicants should check detailed industry classification codes and applicable exceptions.
Different exceptions to the general excluded-industry rules may also apply to disaster-affected small businesses.
Therefore, applicants should not determine eligibility solely from the industry name on their business registration certificate. They should compare their actual industry classification with the conditions specified in the relevant notice.
Which Funding Programs Should Businesses Consider First Based on Their Circumstances?
The appropriate policy financing program should be determined by considering both the intended use of funds and the eligibility requirements.
The following examples can help determine which application route to explore.
| Business Situation | Funding Programs or Conditions to Review First |
|---|---|
| Business requiring ordinary operating funds | General Business Stabilization Funds and similar programs |
| Business experiencing temporary financial difficulties | Detailed eligibility requirements for Emergency Business Stabilization Funds |
| Business affected by a disaster | Disaster-related policy financing programs |
| Business having difficulty securing financing due to its credit standing | Eligibility requirements for Credit-Vulnerable Small Business Funds |
| Business meeting conditions related to youth employment | Eligibility requirements for Youth Employment-Linked Funds |
This table is not a standard for determining loan approval. Instead, it provides a way to narrow down funding programs based on a business's circumstances.
Even within the same industry, eligible programs may differ depending on business location, employment conditions, credit standing, and the intended use of funds.
In particular, programs operated through direct loans and those operated through agency loans each have designated application procedures.
Applicants cannot freely choose their preferred lending method for every funding program.
What Should Applicants Check Before Applying?
Before applying for small business policy financing, it is advisable to organize business information in the following order.
1. Verify the industry listed on the business registration and the business's actual operations.
2. Identify the intended use of funds, such as operating expenses, facility investment, or relief from business difficulties.
3. Check the business location and whether it qualifies for special assistance.
4. Review the eligibility requirements of the intended policy financing program.
5. Determine whether the program provides direct loans or agency loans.
6. Check the applicable interest rate, loan limit, repayment period, and assessment procedures.
7. Confirm whether applications are being accepted at the time of submission.
For agency loans, completing the policy financing eligibility confirmation process does not guarantee access to funds. Applicants must also pass the financial institution's loan assessment.
For direct loans, eligibility and loan conditions likewise depend on SEMAS assessment results.
Furthermore, even when an annual policy financing plan has been announced, application availability may change depending on individual program schedules and budget conditions.
As of 2026-10-15, business owners preparing to apply should check the application status of the relevant program through the online small business policy financing application system.
Frequently Asked Questions
Does Receiving an Agency Loan Eligibility Confirmation Certificate Guarantee a Bank Loan?
No. Eligibility confirmation and actual loan approval are separate procedures.
A loan may still be denied depending on the financial institution's assessment and any required guarantee assessment.
Can Applicants With Low Credit Scores Apply for Direct Loans?
Credit standing alone cannot determine eligibility for all direct loan programs.
Some programs, such as Credit-Vulnerable Small Business Funds, are designed for specific applicant groups, so their individual eligibility requirements must be checked.
Even applicants who meet the eligibility requirements must pass the assessment process to receive a loan.
Do Agency Loans or Direct Loans Always Have Lower Interest Rates?
No.
Interest rates should be evaluated based on the individual policy financing program and its applicable conditions, rather than the lending method itself.
The preferential disaster financing conditions announced for Geoje and Tongyeong in 2026-10-01 specified different fixed interest rates for agency loans and direct loans, but those rates cannot be applied to all policy financing programs.
Can Businesses Apply at Any Time Once the 2026 Policy Financing Plan Has Been Announced?
The announcement of an annual financing plan must be distinguished from whether applications are currently being accepted for individual programs.
Before applying, applicants should check the latest application notice and online application page for the relevant funding program.
How to Choose the Right Loan for Your Business
It is difficult to make a blanket judgment that agency loans or direct loans are better for small business policy financing in 2026.
Businesses needing ordinary working capital, businesses experiencing temporary financial difficulties, and disaster-affected businesses face different eligibility requirements.
Therefore, the appropriate approach is to first verify the business's industry and funding needs, then compare the relevant policy financing program's lending method, interest rate, and assessment procedures.
Because the 5 amendment notice applies in October 2026, applicants should avoid relying solely on previously saved loan conditions.
Before submitting an application, business owners should review SEMAS's latest program-specific guidance and application status to make a final determination of the conditions applicable to their businesses.