

2026 Earned Income Tax Credit: September Applicants, Expected Payment on December 17, and Eligibility for Up to KRW 1,150,000
If you applied for the first-half Earned Income Tax Credit in September 2026, payment is scheduled for December 17, with a maximum payment of KRW 1,150,000. However, not every applicant will receive the same amount. 35% of the estimated annual credit is paid first, and the amount may be reduced or payment deferred until June 2027 depending on the income and asset review results.
Based on the payment schedule announced by the National Tax Service (NTS) on 2026-09-01, we will examine how much applicants may actually receive and the conditions that could delay payment.
Is the December Payment Date 17 or 30?
The actual scheduled payment date for the 2026 first-half Earned Income Tax Credit is December 17. This is the schedule announced by the NTS in its September application guidance, while the statutory payment deadline is December 30.
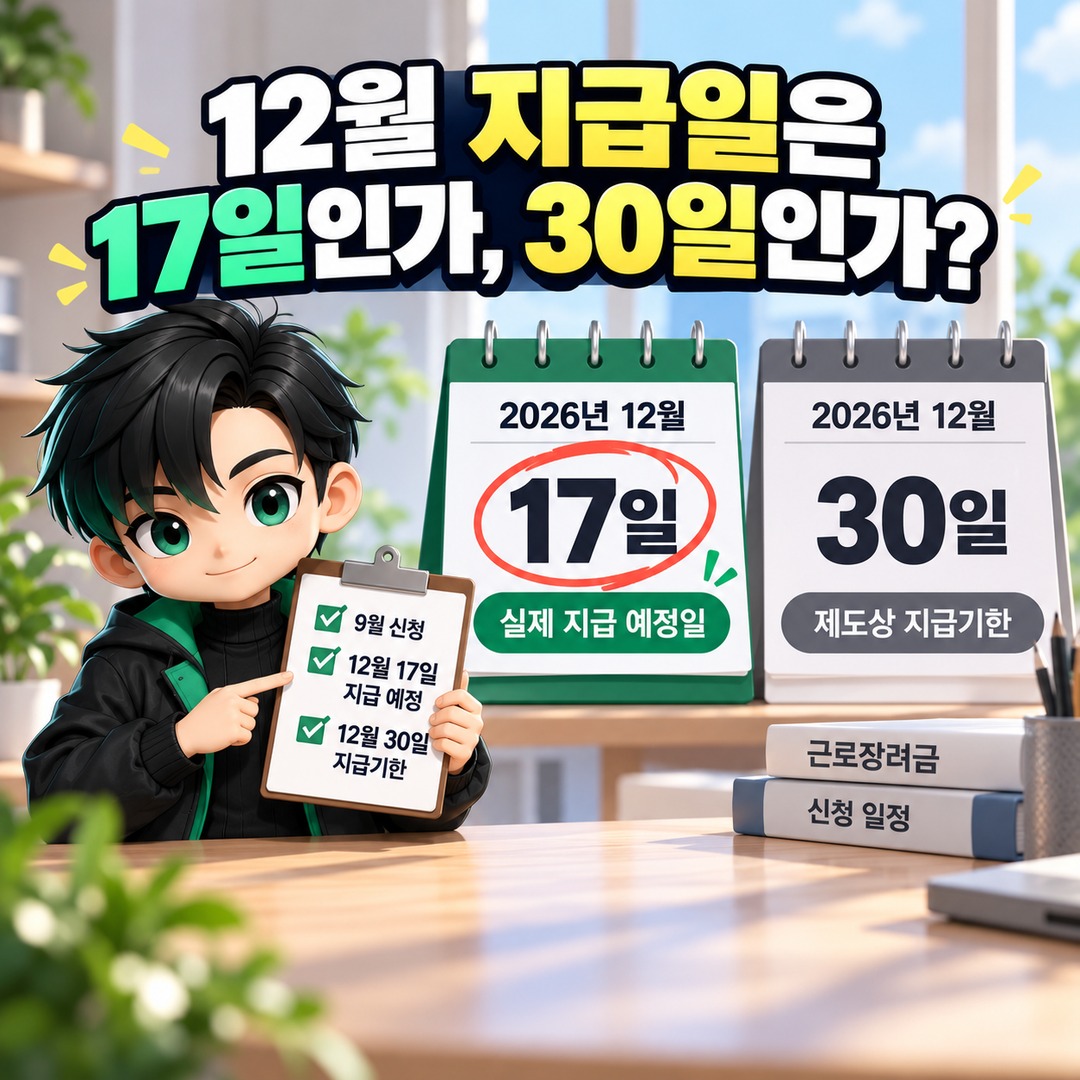
The two dates have different meanings.
| Category | Date and Meaning |
|---|---|
| Scheduled payment date | 2026-12-17 |
| Statutory payment deadline | 2026-12-30 |
| Second-half reconciliation | June 2027 |
December 17 is the date specified in the payment schedule announced by the NTS. Payments are made after applicants' income, assets, and other eligibility factors have been reviewed, so submitting an application does not guarantee that the money will be deposited on that date.
As of 2026-10-16, payments are still scheduled rather than finalized. Applicants must check their review results to confirm whether they will receive a payment and how much it will be.
What Is the Maximum Amount You Can Receive in December?
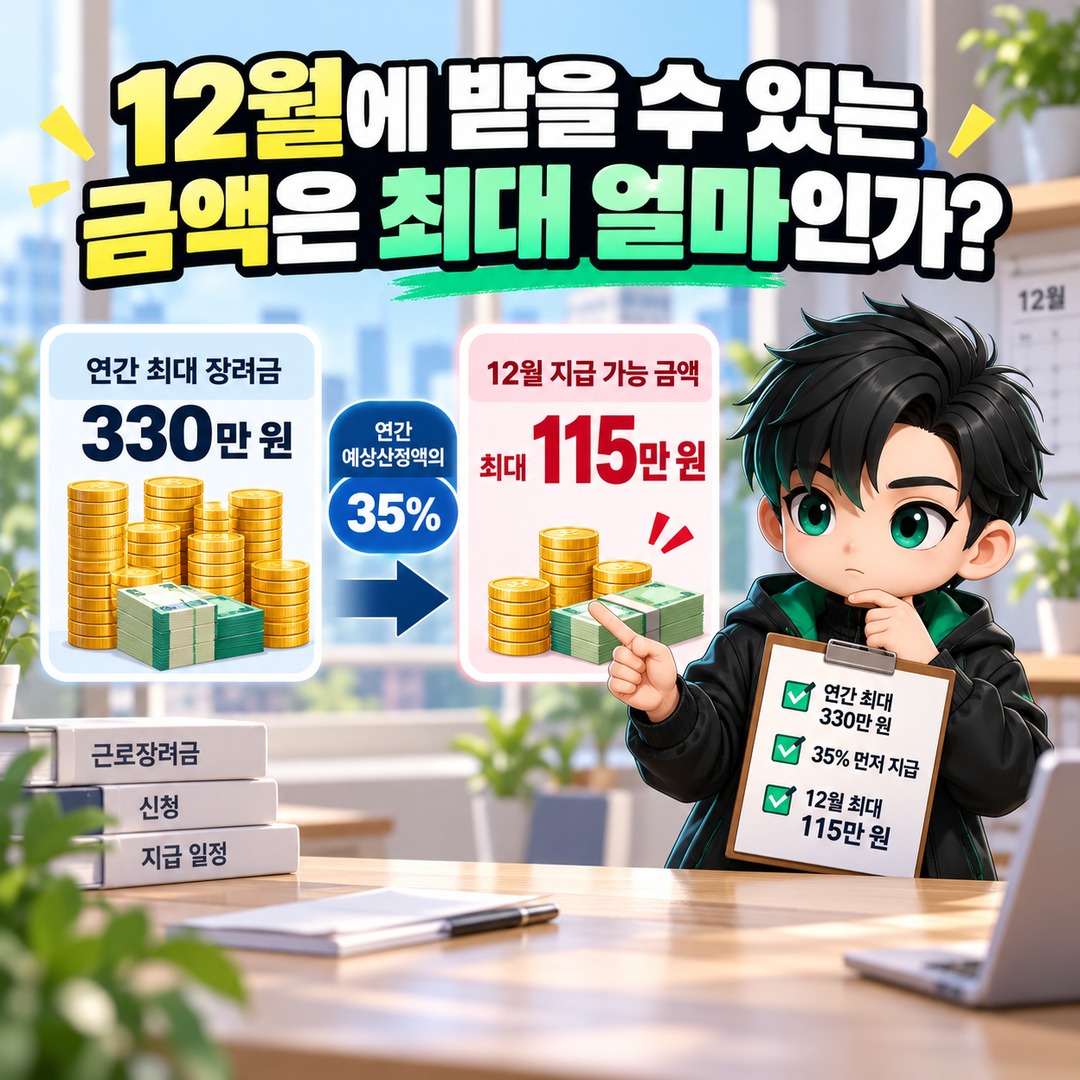
Applicants who submitted a semiannual application in September 2026 can receive up to approximately KRW 1,150,000 in Earned Income Tax Credit payments in December. This is because 35% of the estimated annual credit is paid in advance, rather than paying the full annual maximum of KRW 3,300,000 at once.
The maximum payment amounts by household type are compared below.
| Household Type | Annual Maximum | December Maximum |
|---|---|---|
| Single-person household | KRW 1,650,000 | KRW 577,500 |
| Single-income household | KRW 2,850,000 | KRW 997,500 |
| Dual-income household | KRW 3,300,000 | KRW 1,155,000 |
The December maximum amounts are calculated by applying 35% to the annual maximum amounts. The calculated maximum for a dual-income household is KRW 1,155,000, which the NTS describes as approximately KRW 1,150,000.
However, these figures are intended to illustrate the payment ceilings for each household type. Actual payments vary depending on annualized earned income, assets, household type, and other factors.
For example, if the estimated annual Earned Income Tax Credit is calculated at KRW 2,000,000, the advance payment in December would be KRW 700,000.
KRW 2,000,000 × 35% = KRW 700,000
The remaining KRW 1,300,000 is not automatically paid the following year. In June 2027, the final credit is recalculated using actual annual income for 2026 and the applicable household and asset requirements.
Could You Receive No Payment in December Even If You Applied in September?
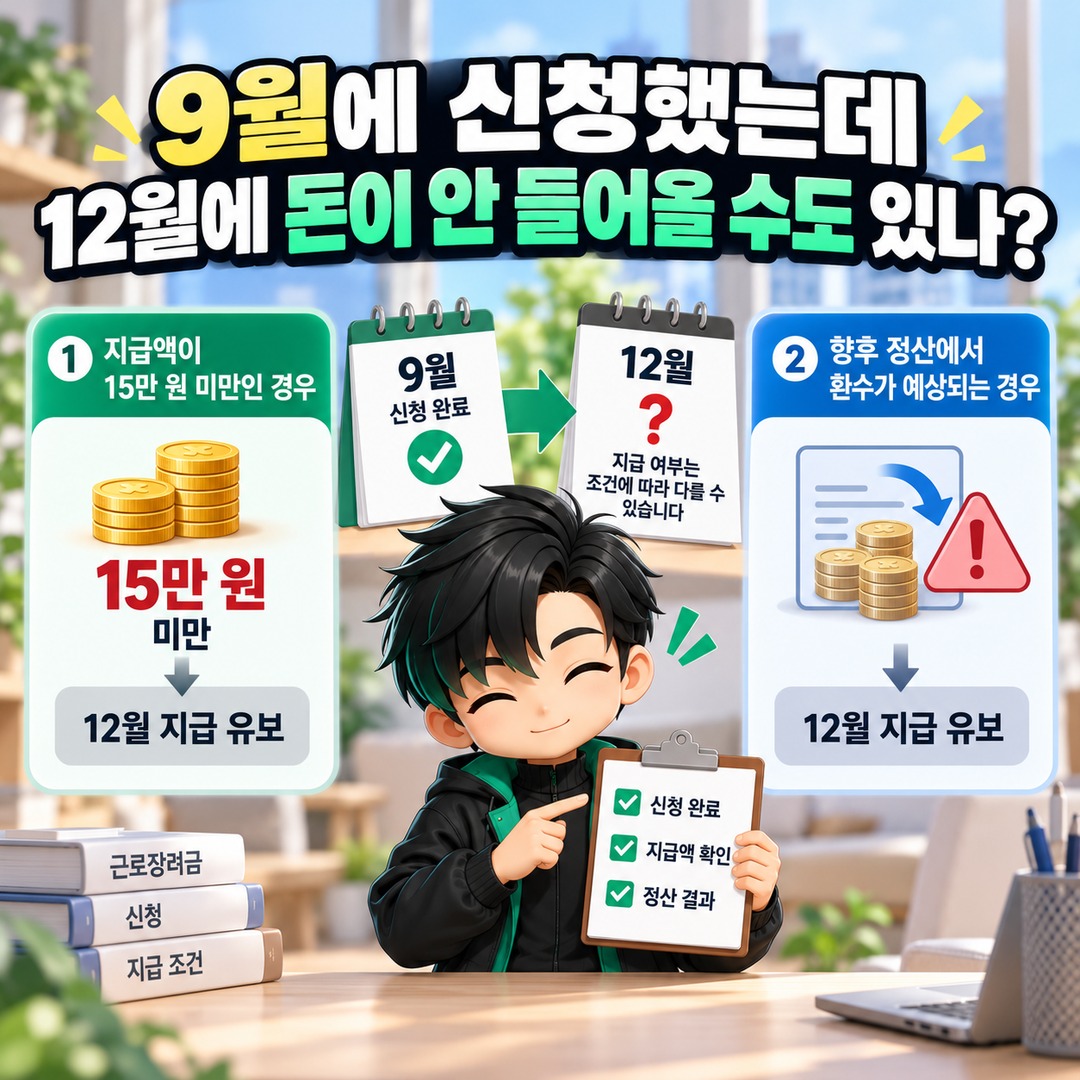
Even if an application has been completed, payment in December may be deferred if the calculated first-half payment is less than KRW 150,000 or if the applicant is expected to have to repay part of the credit during the subsequent reconciliation.
The main conditions identified by the NTS are as follows.
Below KRW 150,000: If the first-half payment is less than KRW 150,000, it will not be paid in December and will instead be reconciled in June 2027.
Expected repayment: If the subsequent year's reconciliation is expected to require repayment of a credit already received, payment in December may be deferred.
Asset requirements: If the combined assets of household members as of 2025-06-01 are at least KRW 170,000,000 but less than KRW 240,000,000, only 50% of the calculated credit is paid.
Types of income: Households with business income or religious income in addition to earned income are subject to the regular payment procedure rather than the semiannual payment procedure.
Importantly, debts are not deducted when assessing assets. In addition to homes and bank deposits, vehicles, rental deposits, and other property may be included in the asset calculation. Applicants therefore should not estimate their payment amounts based solely on their income.
Starting in 2026, improvements were also introduced to collect local tax assessment data earlier for first-half eligibility reviews. This measure is intended to reduce advance payments of credits that are expected to be recovered during subsequent reconciliation.
How Much More Could You Receive in June 2027?
In June 2027, the Earned Income Tax Credit is recalculated based on total income for 2026. The amount already paid in December 2026 is then deducted to determine the final settlement.
For example, if you received KRW 700,000 in advance in December and your final annual credit was determined to be KRW 1,800,000 in June 2027, your additional payment would be KRW 1,100,000.
KRW 1,800,000 - KRW 700,000 = KRW 1,100,000
Conversely, if the final calculated credit is lower than the amount already received, you may be required to repay the difference.
The important point to remember is that the December payment and the final annual credit are two different amounts.
In addition, employees who applied for the first-half credit in September 2026 generally do not need to submit another application for the March 2027 second-half period or the May regular application period.
If they also meet the eligibility requirements for the Child Tax Credit, that credit is not included in the December advance payment. Instead, it is paid together with the Earned Income Tax Credit during the June 2027 reconciliation.
Where Can You Check Your Earned Income Tax Credit Payment Amount?
Applicants who applied in September 2026 can check the progress of their payment eligibility review through the NTS Hometax service.
After logging in to Hometax, follow these steps.
1. Select the Tax Credits, Year-End Tax Settlement, and Donations menu
2. Go to the Regular/Semiannual Earned Income Tax Credit Application menu
3. Select Check Review Progress
4. Check your application and review status
Because payment eligibility and the actual payment amount are determined by the review results, the final payment may differ from the estimated amount provided when the application was submitted.
For questions about tax credits, you can also contact the NTS Tax Credit Consultation Center at 1566-3636.
Key Payment Dates for September 2026 Applicants
Employees who applied for the first-half Earned Income Tax Credit between 2026-09-01 and 15 should check their review results in relation to the scheduled payment date of December 17.
The December payment is 35% of the estimated annual credit, with a maximum of approximately KRW 1,150,000 depending on household type. However, payment may not be made in December if the calculated amount is below KRW 150,000 or repayment is expected, among other reasons.
Because the final reconciliation in June 2027 is based on annual income and asset requirements, the amount received in December does not necessarily represent the entire annual credit.
If you completed your application in September, your priority should be to check your current review status and scheduled payment amount through Hometax rather than submitting a separate application.