

Do You Have to Pay the October VAT Advance Assessment Again in January? How the Deduction Works When Filing Your Final Return
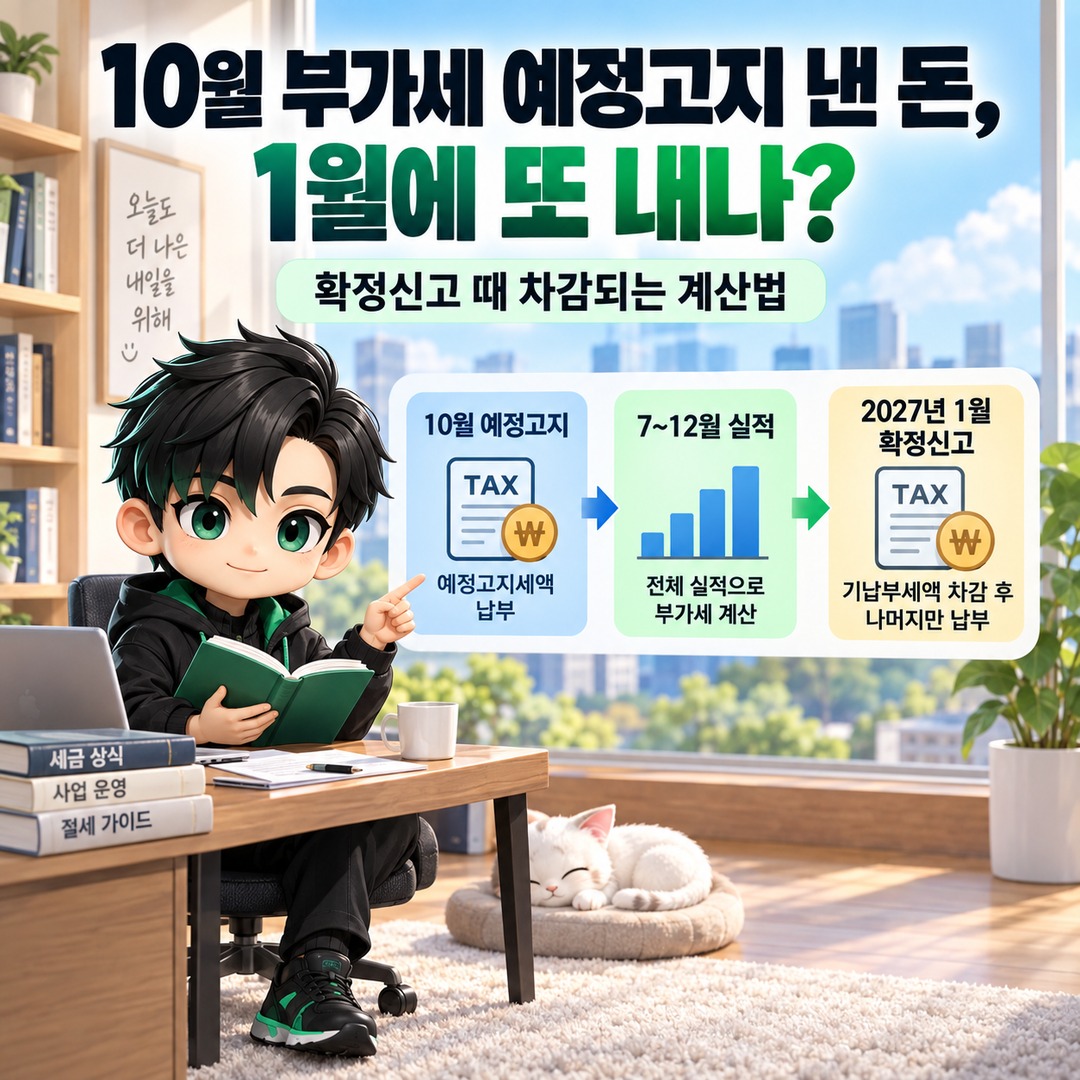
If you paid the VAT advance assessment in October, you do not have to pay the same tax again when filing your final return in January 2027. The advance assessment amount already paid is deducted as tax previously paid, and you pay only the remaining balance after subtracting that amount from the VAT calculated on your total business activity for 7–December.
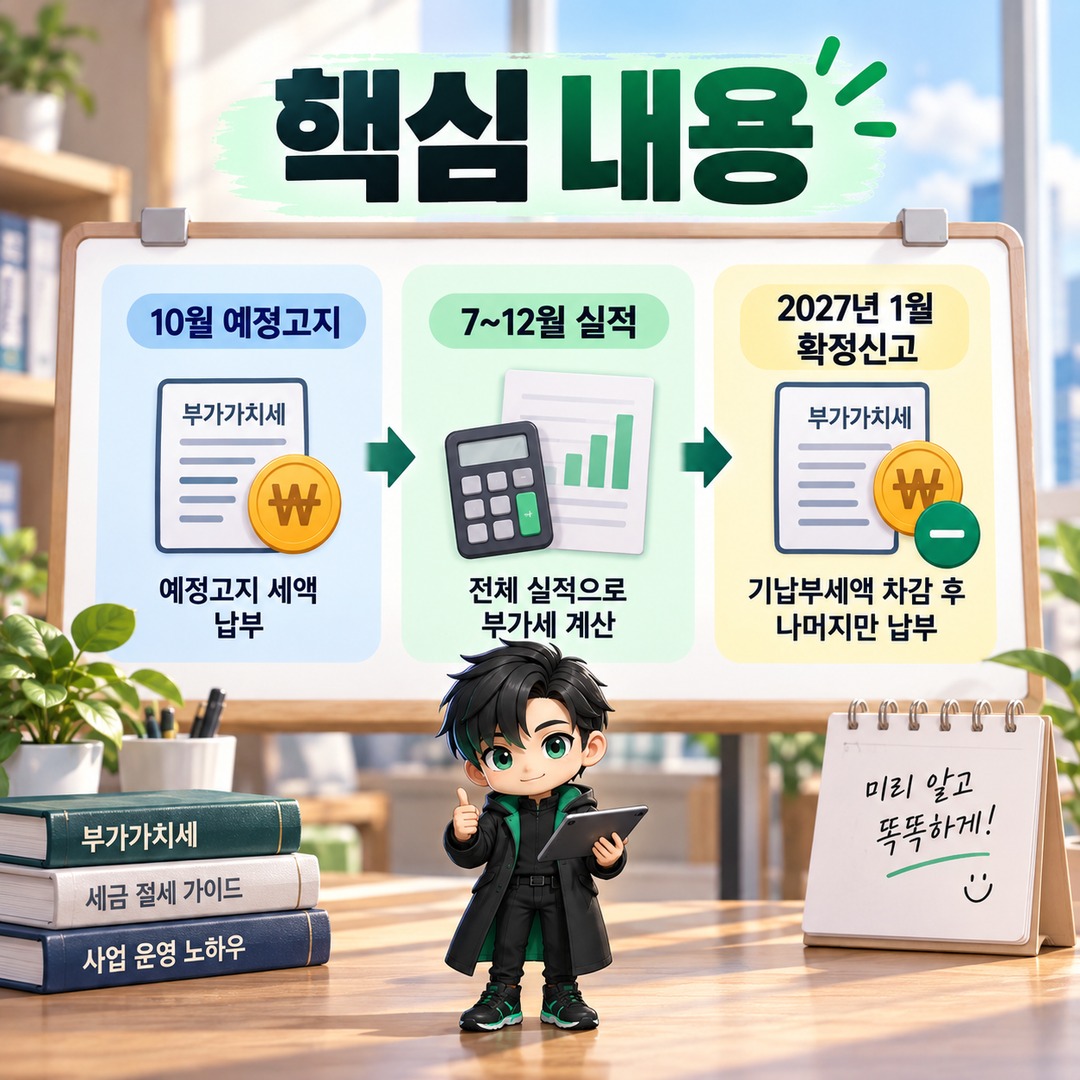
In other words, the payment made in October is not a separate additional tax. Instead, it functions much like an advance payment of part of the VAT that will be settled through the next final return.
Where Is the Advance Assessment Paid in October Deducted in January?
For individual business owners subject to the general VAT taxation system, the reporting period for the 2th VAT period's final return runs from July 1 through December 31. The standard filing and payment deadline is January 25 of the following year.
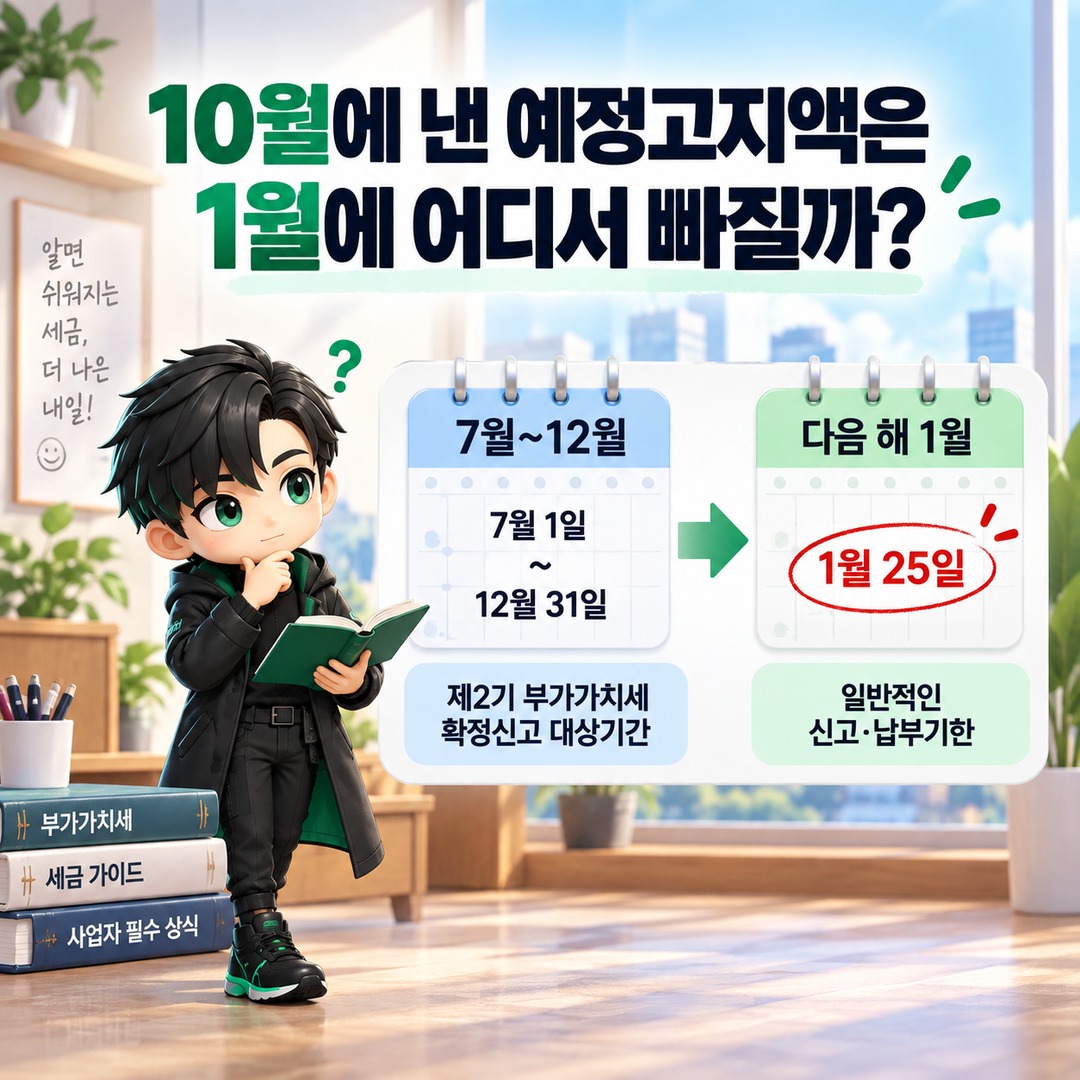
The October advance assessment, by contrast, is a system under which individual business owners subject to general VAT taxation and certain other taxpayers make an interim payment based on the VAT paid during the preceding taxable period. Under Article 48 of the Value-Added Tax Act, the advance assessment is generally determined based on 50% of the VAT paid during the preceding taxable period.
The key is the final VAT return.
Calculate the Total VAT for 7–December → Subtract the Advance Assessment Already Paid in October → Pay the Remaining Balance
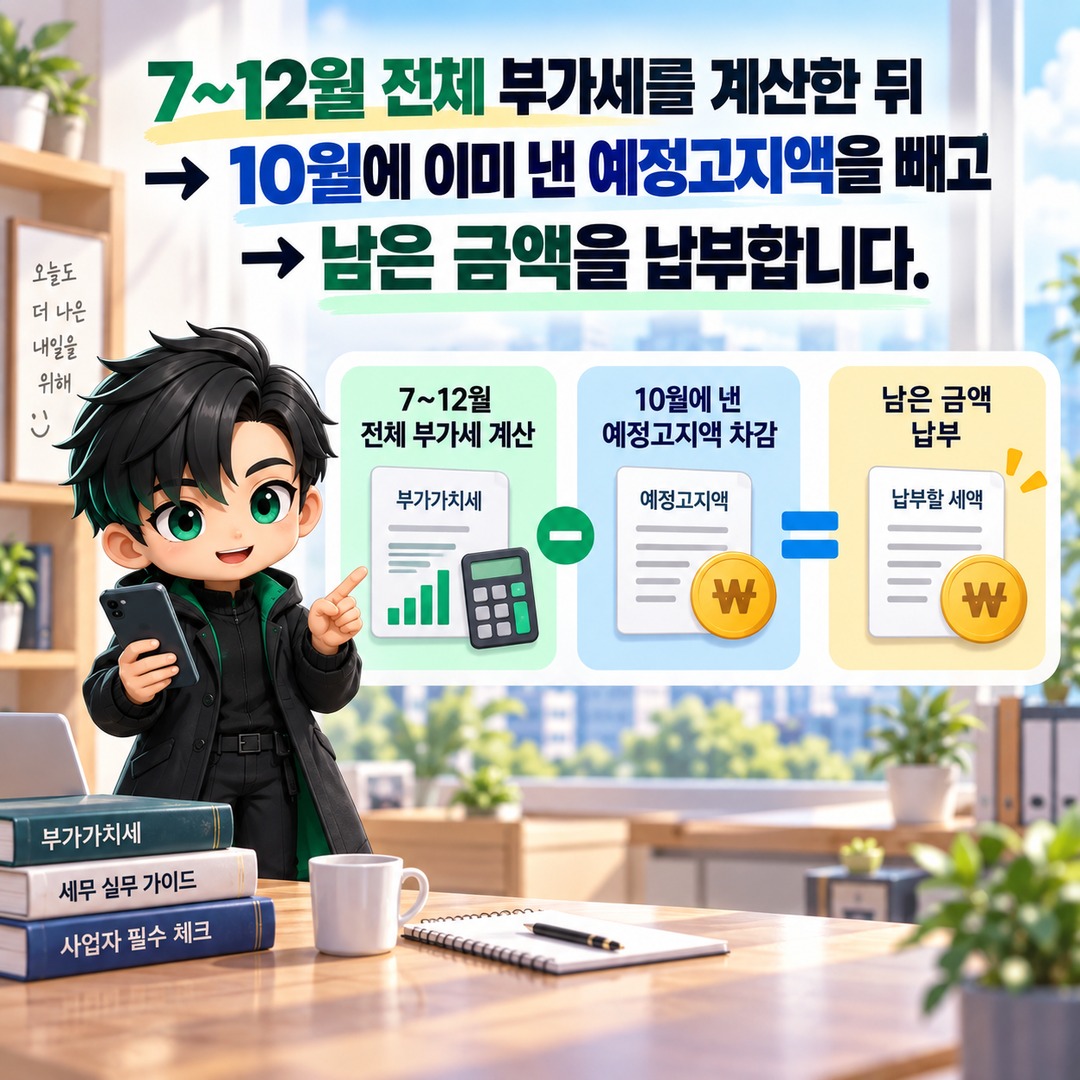
The National Tax Service also explains that the amount assessed in advance is deducted as tax previously paid when the next final VAT return is filed.
For Example, If You Paid KRW 1,000,000 in October, How Much Would You Pay in January?
The calculation becomes much easier to understand with numbers.
| Category | Amount |
|---|---|
| Final VAT payable calculated from business activity during 7–December | KRW 3,000,000 |
| Amount already paid through the October advance assessment | KRW 1,000,000 |
| Additional amount payable in January | KRW 2,000,000 |
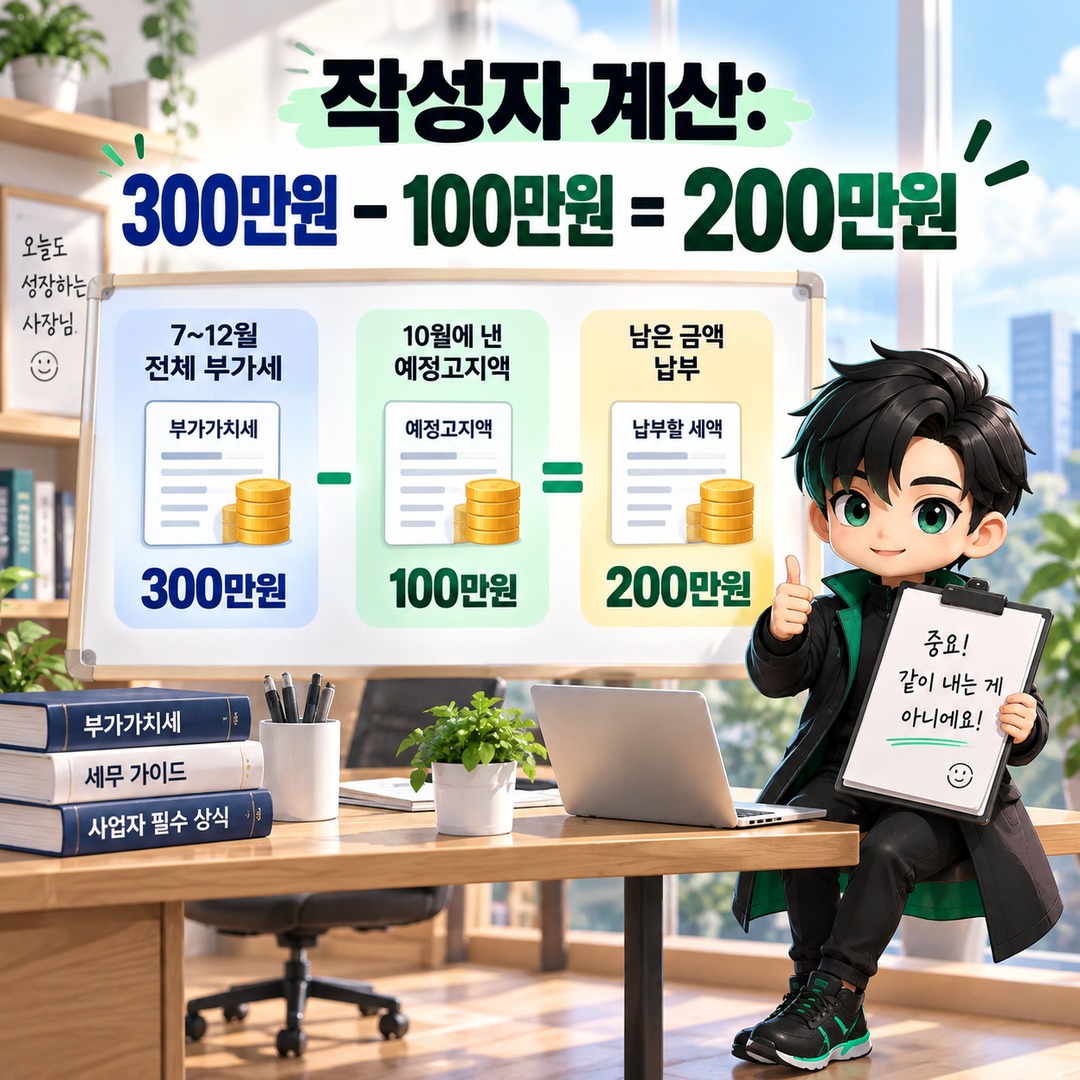
Author's Calculation: KRW 3,000,000 - KRW 1,000,000 = KRW 2,000,000
Therefore, the system does not require you to pay KRW 1,000,000 in October plus KRW 3,000,000 in January, for a combined total of KRW 4,000,000.
If the VAT calculated on your total business activity during 7–December is KRW 3,000,000, you subtract the KRW 1,000,000 already paid in October and pay an additional KRW 2,000,000 in January.
Paying the advance assessment does not, by itself, finalize the total VAT liability for the 2th taxable period. The final amount is determined through the final return, which reflects sales, purchases, and other relevant transactions through December.
What Happens If Your Actual VAT Liability Is Lower Than the October Advance Assessment?
Business conditions can change from one taxable period to the next. Therefore, the October advance assessment and the final VAT liability calculated from actual business activity during 7–December do not necessarily have to match.
For example, suppose you paid KRW 1,000,000 through the advance assessment in October, but the VAT calculated from your business activity during 7–December turns out to be lower. Whether this simply means that no additional payment is required in January or that a refundable amount arises must be determined from the actual final return, including the reported transactions and any applicable deductions or adjustments.
Conversely, if sales and VAT liability increase during the second half of the year, the additional amount payable in January may be substantial even after deducting the advance assessment.
Therefore, you should not determine your January VAT liability solely from the October advance assessment amount.
If You Paid the Advance Assessment, Can You Skip the Final VAT Return in January?
No. Paying the advance assessment and filing the final VAT return are separate obligations.
Individual business owners subject to general VAT taxation must report their business activity from July 1 through December 31 when filing the final return for the 2th taxable period. The advance assessment does not replace this final return; it is simply a procedure for paying part of the tax in advance.
The process can be summarized as follows.
Pay the October Advance Assessment → Finalize Business Results for the 2th Period Through December 31 → File the Final Return in January of the Following Year → Deduct the Advance Assessment Already Paid → Pay the Difference or Settle the Amount According to the Filing Results
Therefore, you should not assume that paying in October means you no longer need to file a return in January.
The Calculation Is Different for Taxpayers Who Never Received an October Advance Assessment Notice
It is important to distinguish between taxpayers who received an advance assessment notice and those who did not.
As of 2026, the Value-Added Tax Act provides that an advance assessment amount subject to collection is not collected if it is less than KRW 500,000. The National Tax Service also explains that business owners excluded from advance assessment must report and pay VAT based on their business activity for the relevant taxable period during the subsequent final filing period.
Importantly, the absence of an advance assessment below KRW 500,000 does not mean that VAT for the relevant period is exempt.
If no advance assessment was issued, there is also no advance assessment payment to deduct. The VAT payable is therefore determined by the actual business activity reported in the final return.
The law also specifies 'less than KRW 500,000,' not 'KRW 500,000 or less.' Therefore, an amount of exactly KRW 500,000 should not be treated the same as an amount of KRW 499,000.
There Are Two Figures You Actually Need to Check
You do not need to memorize numerous complicated figures to understand how VAT payments in October relate to the following year's January filing.
The first is the advance assessment amount you actually paid in October. The second is the total VAT payable for 7–December as calculated in your final return.
You can check the advance assessment amount through the VAT advance assessment inquiry menu on Hometax. The National Tax Service explains that taxpayers can review their advance assessment amounts through Hometax, SonTax, and other available services.
Ultimately, the most important calculation can be expressed in a single line.
Tax Calculated in the Final Return - Advance Assessment Tax Already Paid = Additional Amount to Be Settled
However, actual returns reflect each business owner's circumstances, including input VAT, deductions, reductions, and amendments. Therefore, the actual filing results may differ from this simplified example.
What to Remember If You Paid the October 2026 Advance Assessment
Paying the October 2026 advance assessment does not mean you must pay the same amount again in January 2027. The amount already paid is deducted as tax previously paid when filing the final return for the 2th taxable period.
However, an advance assessment does not replace the final return. Individual business owners subject to general VAT taxation must file the final return for the 2th taxable period based on their total business activity during 7–December of 2026, then subtract the amount paid in October to settle the final balance.
The procedure may vary depending on individual circumstances, including business classification, changes in VAT taxation status, temporary suspension or closure of business, and early refunds. For an actual filing, it is advisable to review both your Hometax filing records and guidance from the tax office with jurisdiction over your business.