

Mortgage Rate Rises from 4% to 4.5%: How Much Principal Must You Repay to Keep Monthly Payments Unchanged?
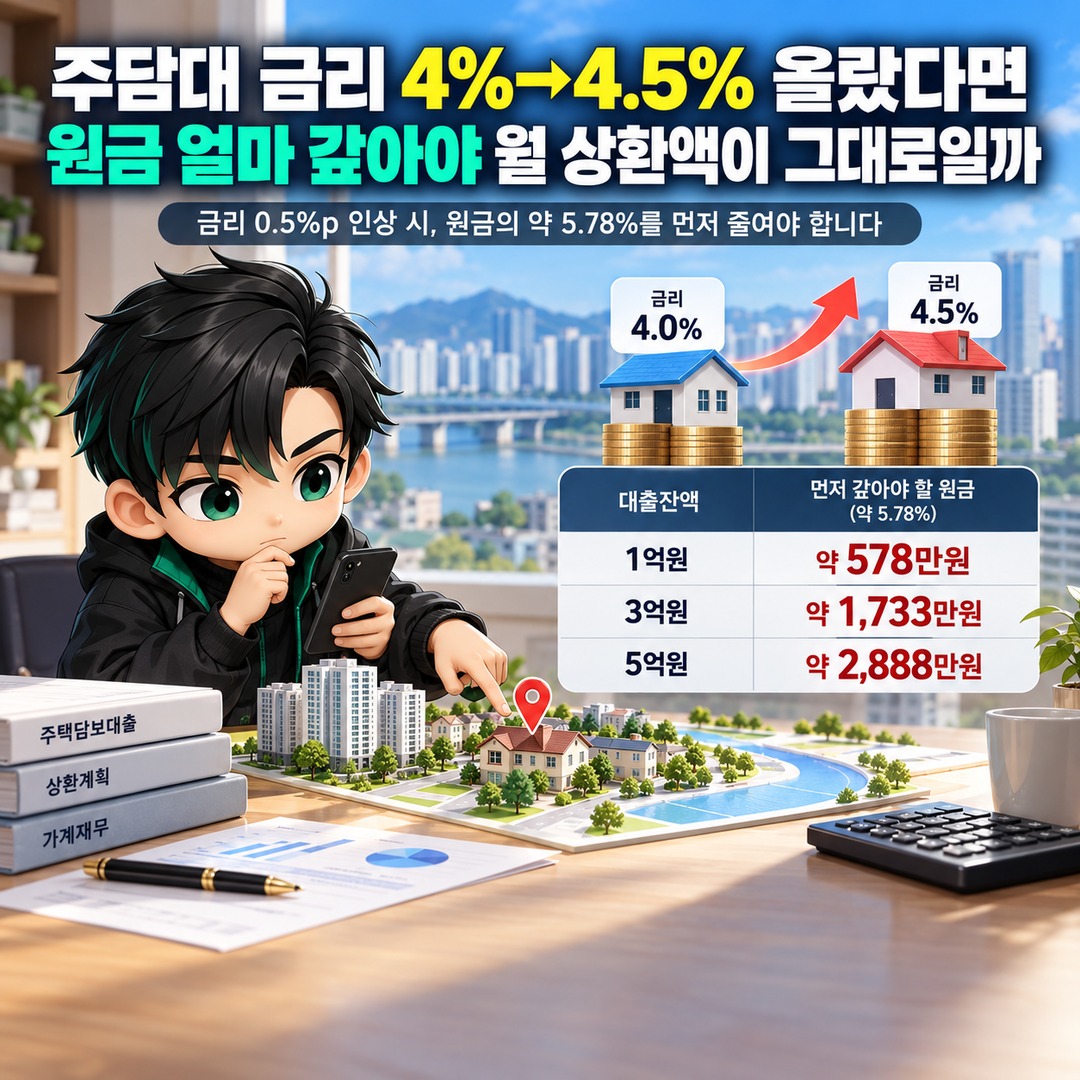
If your mortgage interest rate rises from 4.0% annually to 4.5%, an increase of 0.5% percentage points, a simplified calculation assuming equal monthly principal-and-interest payments over a 30-year term, with 30 years remaining, suggests that you would need to reduce your principal by approximately 5.78% to keep your monthly payment close to its previous level. For outstanding loan balances of KRW 100,000,000, KRW 300,000,000, and KRW 500,000,000, the required principal reductions would be approximately KRW 5,780,000, KRW 17,330,000, and KRW 28,880,000, respectively.
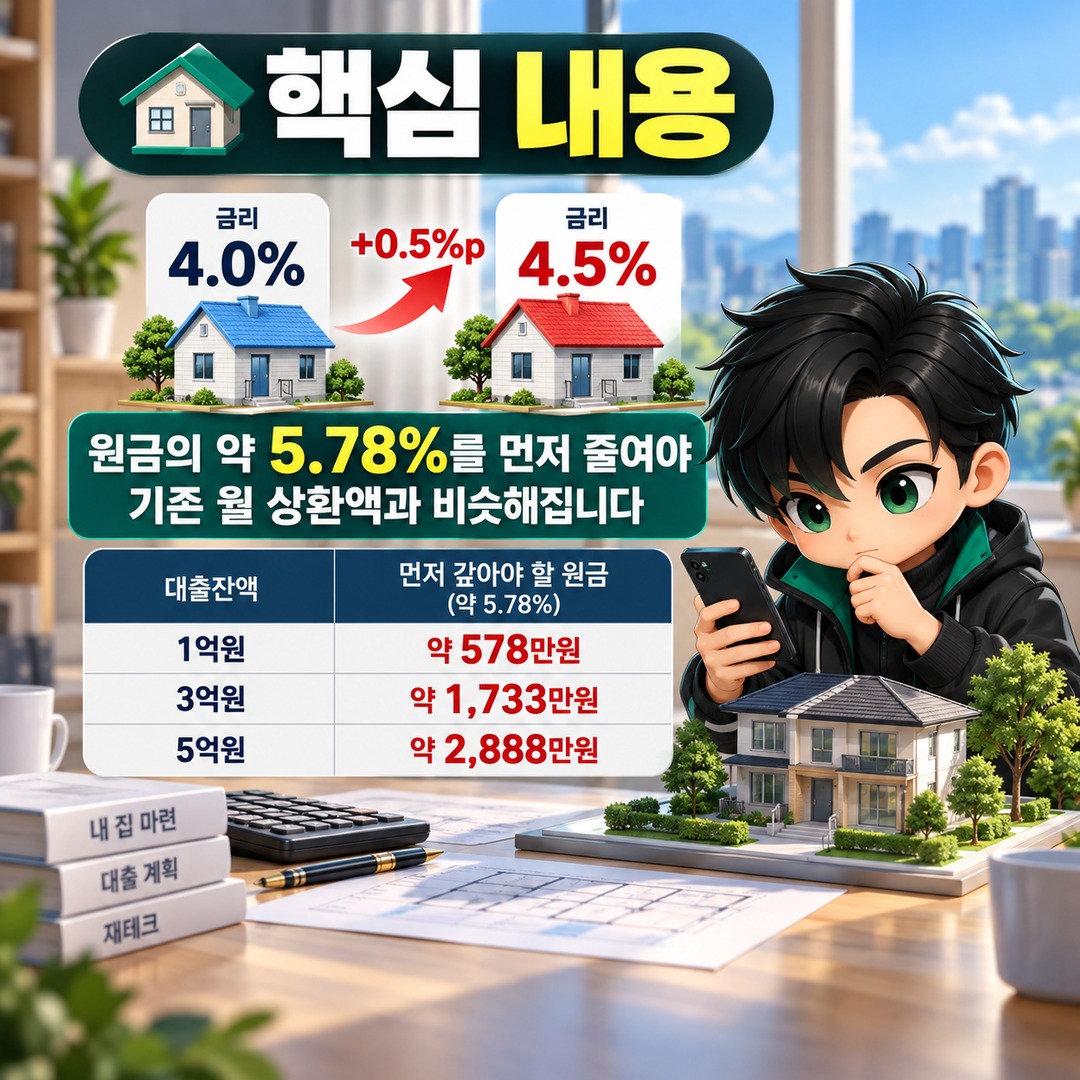
With interest rates changing recently, a natural question arises after asking, "How much will my monthly payment increase?" That question is how much of the loan principal you would need to repay using available funds to offset the interest rate increase.
With KRW 300,000,000 Outstanding, You Would Need to Reduce the Principal by Approximately KRW 17,330,000
At an annual interest rate of 4.0%, using equal monthly principal-and-interest payments over 30 years, the monthly payment on KRW 300,000,000 is approximately KRW 1,432,000.
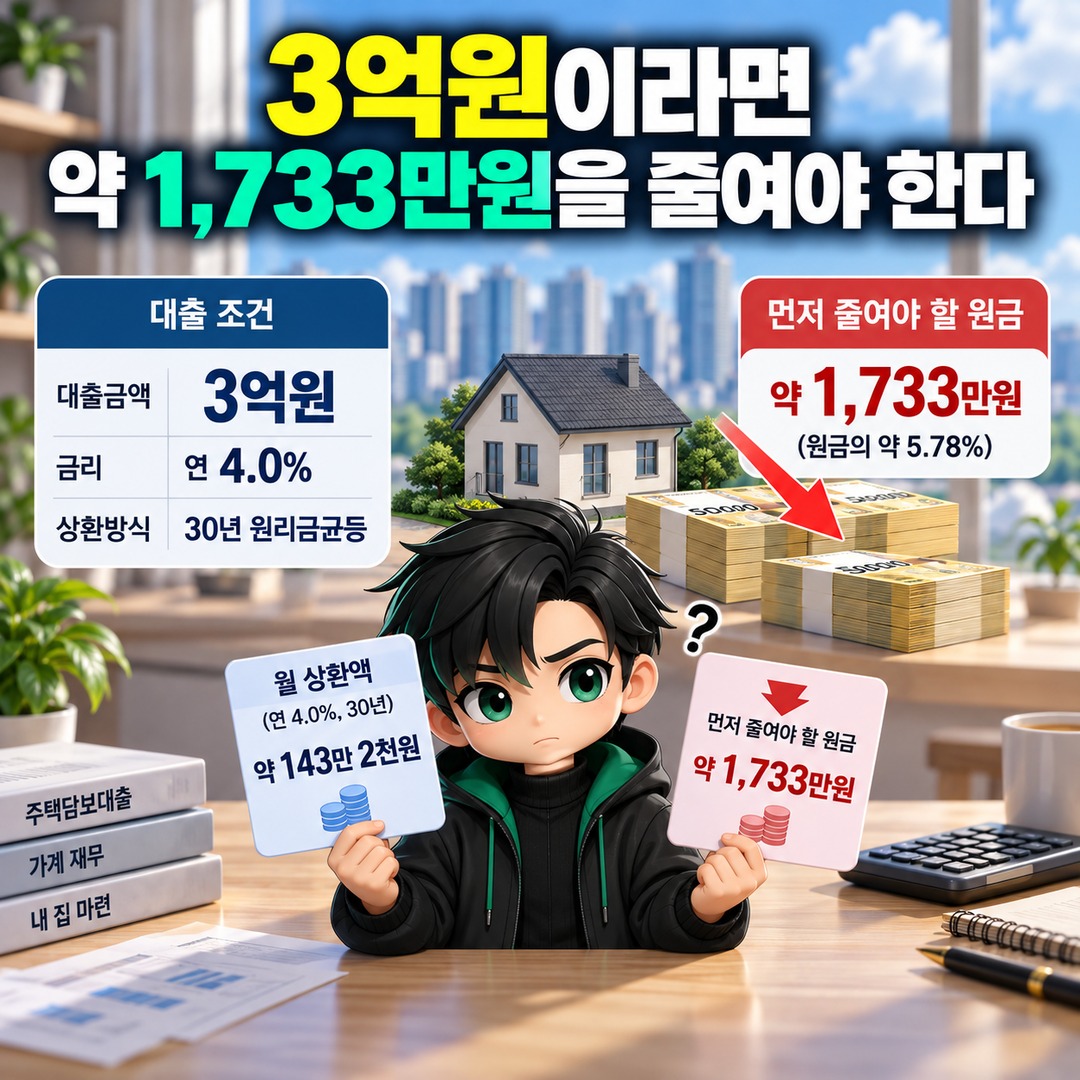
If the annual interest rate rises to 4.5%, the monthly payment under otherwise identical conditions increases to approximately KRW 1,520,000, an increase of about KRW 88,000.
So how far would you need to reduce your outstanding loan balance to keep the monthly payment at approximately KRW 1,432,000, even at the 4.5% interest rate?
| Original Outstanding Loan Balance | Monthly Payment at 4% | Required Principal Reduction at 4.5% |
|---|---|---|
| KRW 100,000,000 | Approx. KRW 477,000.0 | Approx. KRW 5,780,000 |
| KRW 300,000,000 | Approx. KRW 1,432,000.0 | Approx. KRW 17,330,000 |
| KRW 500,000,000 | Approx. KRW 2,387,000.0 | Approx. KRW 28,880,000 |
Author's calculation: This assumes 30 years remaining, equal monthly principal-and-interest payments, an annual interest rate change from 4.0% to 4.5%, and recalculation of the monthly payment based on the remaining principal after an early repayment.
For example, if approximately KRW 17,330,000 is repaid from an outstanding balance of KRW 300,000,000, the remaining balance becomes approximately KRW 282,670,000. Applying an annual interest rate of 4.5% over 30 years to that balance produces a monthly payment close to the original payment on KRW 300,000,000 at an annual rate of 4%.
Why Must You Repay 5.78% of the Principal When the Rate Rises by Only 0.5%?
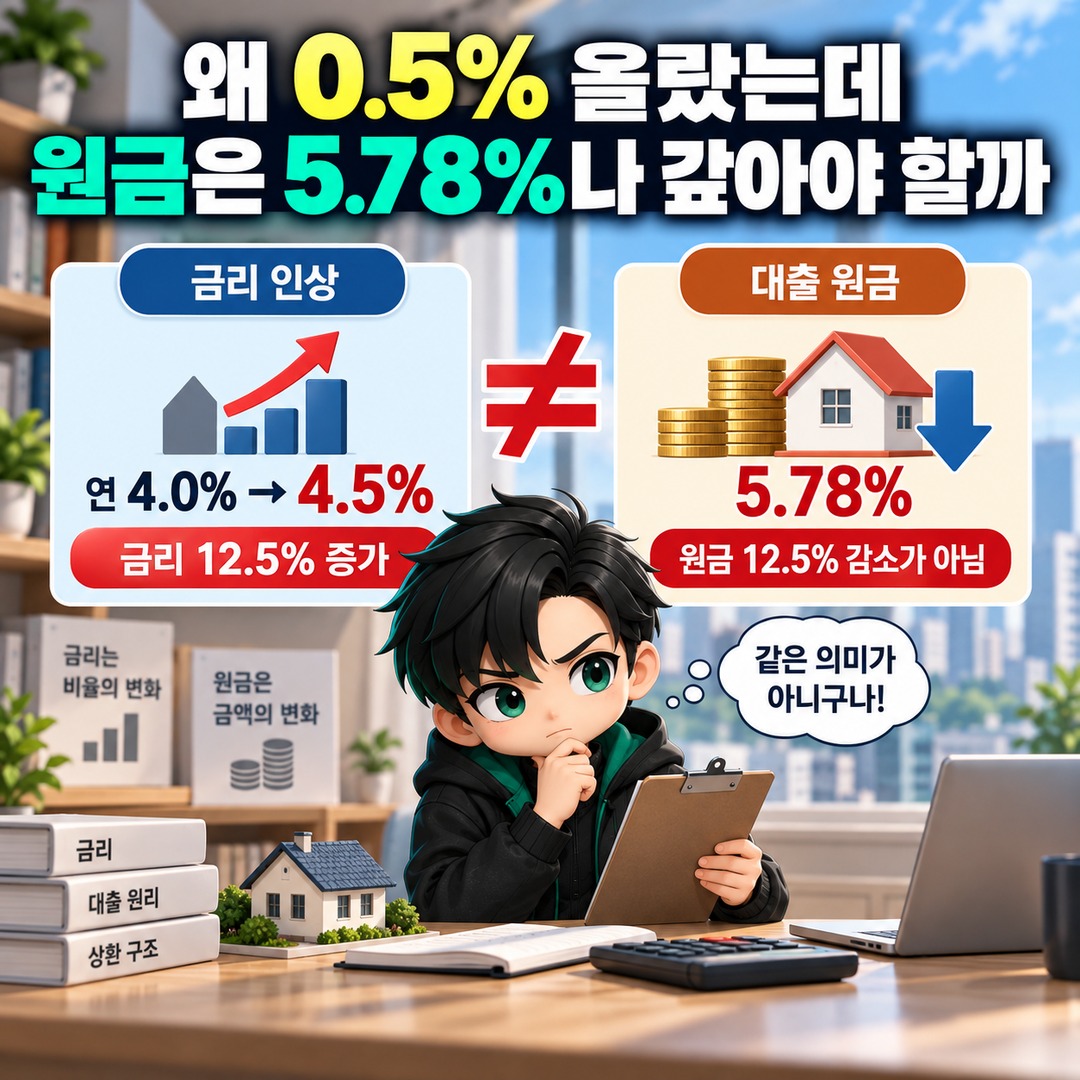
An interest rate increase of 12.5% does not mean that the loan principal must be reduced by 12.5%.
When the annual interest rate changes from 4% to 4.5%, the rate itself rises by 0.5% percentage points. However, this does not translate directly into the same percentage change in the monthly payment because equal monthly principal-and-interest payments include both interest and principal repayment.
A direct calculation of the monthly payment on KRW 100,000,000 over 30 years produces the following results.
Annual rate of 4.0%: Approximately KRW 477,415
Annual rate of 4.5%: Approximately KRW 506,685
Difference: Approximately KRW 29,270
If the loan principal is reduced to approximately KRW 94,220,000 while the interest rate is 4.5%, the monthly payment falls back to approximately KRW 477,000.
The required principal reduction is therefore approximately KRW 5,780,000, or about 5.78% of the original outstanding balance.
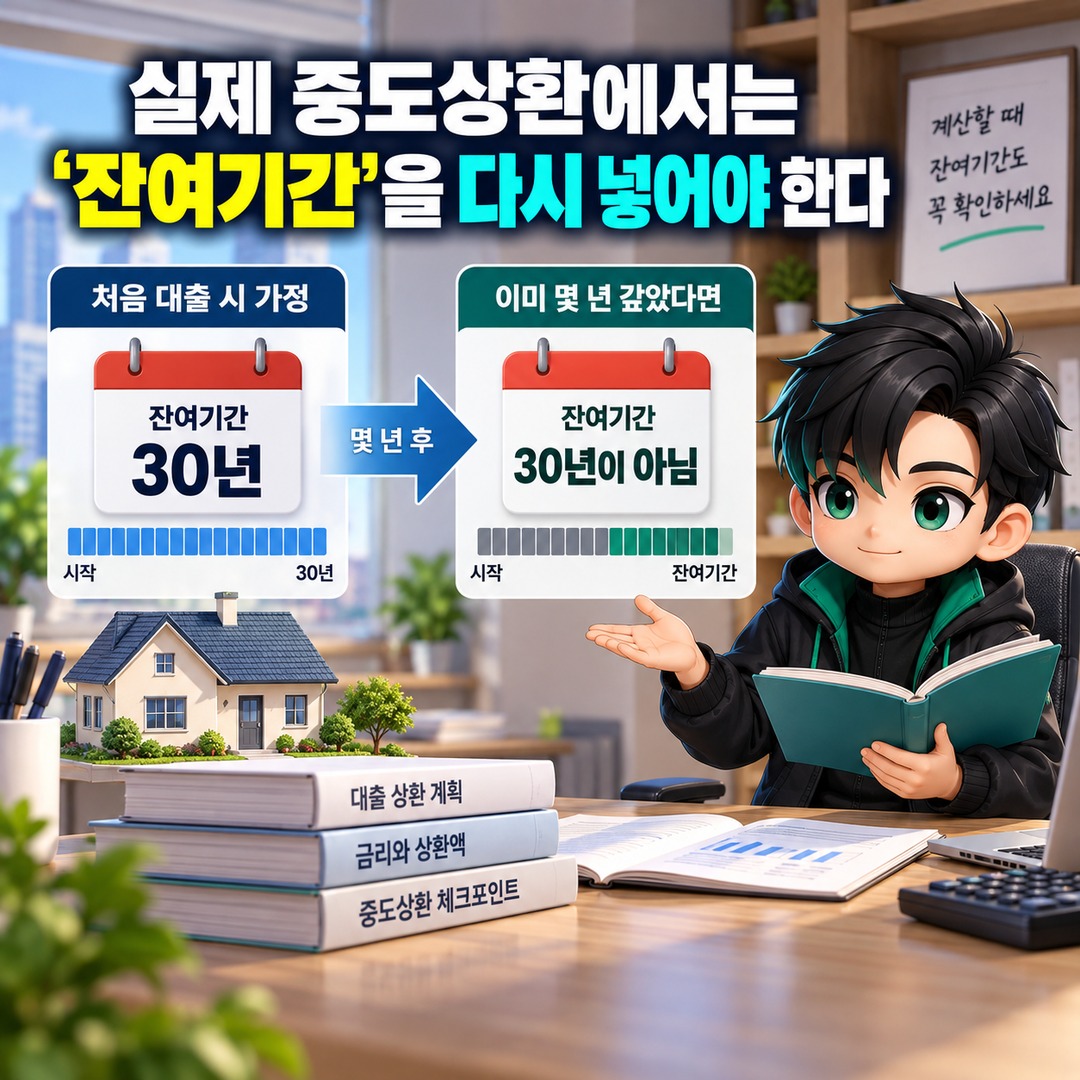
For an Actual Early Repayment, You Must Recalculate Using the Remaining Loan Term
The most important condition in the calculation above is the assumption that 30 years remain on the loan. If you have already been repaying your mortgage for several years, you should not apply these figures directly.
For example, even if the original mortgage term was 30 years, after making repayments for 5 years, the calculation must use the current outstanding balance and the remaining 25 years.
Actual payment amounts may also vary depending on how the bank recalculates monthly payments after an interest rate adjustment, the effective date of the rate change, payment dates, and whether the loan includes an interest-only grace period.
For an accurate calculation of your own mortgage, first check the following four figures.
Current Outstanding Balance → New Applicable Interest Rate → Remaining Repayment Period → Actual Repayment Method
Equal principal-and-interest payments and equal principal repayments produce different results, even at the same interest rate.
Check Early Repayment Fees Before Paying Down Your Principal
Having sufficient spare funds does not necessarily mean that making the calculated early repayment will always produce the same result. If an early repayment fee still applies, you need to compare the interest savings from reducing the principal with the fee you would incur.
South Korea's Financial Services Commission reformed the early repayment fee system beginning in 2025 so that fees would reflect only costs actually incurred. From January 2026, the relevant reforms were also extended to mutual financial institutions. However, the applicable fee rates and exemption conditions vary by financial institution and loan agreement.
In particular, you should not assume that existing and newly issued loan agreements have identical conditions. It is more accurate to check the estimated early repayment fee applicable at the current date in your loan agreement or through your financial institution's app before making a decision.
A Higher Interest Rate Does Not Automatically Mean You Should Repay Principal First
Early principal repayment has the advantage of reducing the outstanding loan balance on which future interest accrues. However, once you have repaid that money, it may be difficult to access it immediately for living expenses or emergency needs.
Therefore, rather than focusing solely on lowering your monthly payment, you should consider three factors together.
First, check whether you will still have sufficient emergency funds after making the early repayment.
Second, if an early repayment fee applies, compare it with the actual interest savings.
Third, separately compare whether refinancing into a loan with a lower interest rate is possible. Refinancing reduces the interest rate, while early repayment reduces the principal itself, so the two approaches have different effects.
The right to request an interest rate reduction also does not automatically apply to every mortgage. The Korea Housing Finance Corporation explains that borrowers may request a rate reduction based on an improvement in their creditworthiness only for loan products in which the borrower's credit status influenced the interest rate determination when the loan was originated.
Also Consider Interest Rate Movements as of October 2026
According to the latest data released by the Bank of Korea on 2026-09-30, the average interest rate on all newly issued loans at deposit-taking banks in August 2026 was 4.40% annually, up 0.13% percentage points from the previous month. This is an average across all loans and is not necessarily the same as the interest rate applied to an individual's mortgage.
Therefore, rather than making a large lump-sum repayment solely because you expect interest rates to rise further, first check your actual interest rate reset date and the rate that will apply to your loan.
How Much Should You Actually Repay on Your Mortgage?
Under the same assumptions of an annual interest rate increase from 4% to 4.5%, equal monthly principal-and-interest payments, and 30 years remaining, reducing your current outstanding balance by approximately 5.78% can bring your monthly payment close to its level before the rate increase.
For outstanding balances of KRW 100,000,000, KRW 300,000,000, and KRW 500,000,000, the corresponding principal reductions are approximately KRW 5,780,000, KRW 17,330,000, and KRW 28,880,000, respectively.
However, these figures are not universally applicable to every mortgage. If you have already repaid part of your loan over time, you must recalculate using your current outstanding balance, new interest rate, remaining repayment period, and repayment method. You should also check any applicable fees before making an actual early repayment.