
Same 20% Investment Return, Different Account Balances: Calculating the KRW 200,000 Difference Based on When Additional Funds Are Deposited
Even when investment returns are identical at 20%, the final account balance and actual investment profit can differ depending on when additional funds are deposited. This is because the money is invested for different lengths of time, even if the initial investment and additional deposit are the same. When comparing returns, investors need to consider both the timing of deposits and the method used to calculate returns.
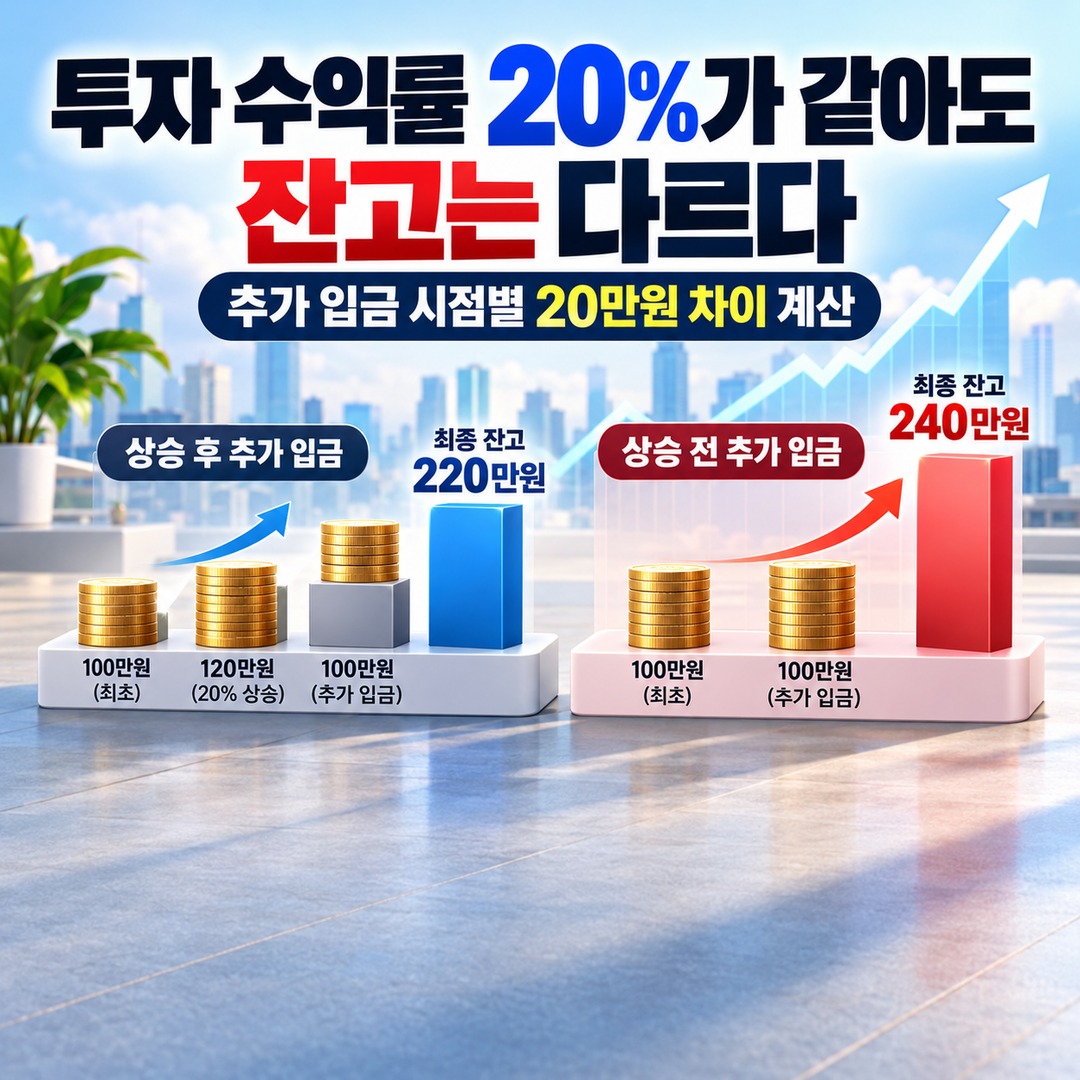
Consider a hypothetical example in which two investors each start with KRW 1,000,000 and subsequently deposit an additional KRW 1,000,000. The investment itself delivers a total return of 20% over the full period for both investors.
Yet changing only the timing of the additional deposit can result in final balances of KRW 2,400,000 and KRW 2,600,000.
This difference does not necessarily mean the investors earned different rates of return. The outcome depends on how much money was exposed to the same return and for how long.
Why Does Changing Only the Timing of an Additional KRW 1,000,000 Deposit Create a KRW 200,000 Difference?
The final balance depends on how long the additional funds remain invested during the price increase. Even when the investment's total return is the same, money deposited before the increase and money deposited after it has ended produce different investment outcomes.
The following is a hypothetical example designed to explain the calculation.
Both investors hold the same investment and initially invest KRW 1,000,000 at the same time.
Assume the investment's price rises by 20% from the beginning to the end of the period. The price increase occurs in the latter part of the period, and fees, taxes, and dividends are excluded. All deposited funds are assumed to be invested immediately and in full at the specified time.
Hypothetical Example: Comparing the Timing of Additional Deposits
| Comparison | Investor A | Investor B |
|---|---|---|
| Initial investment | KRW 1,000,000 | KRW 1,000,000 |
| Additional deposit | KRW 1,000,000 | KRW 1,000,000 |
| Timing of additional deposit | Before the price increase | After the price increase |
| Investment's total return | +20% | +20% |
| Total deposits | KRW 2,000,000 | KRW 2,000,000 |
| Final balance | KRW 2,400,000 | KRW 2,600,000 |
| Actual investment profit | KRW 400,000 | KRW 600,000 |
The final balances in the table can be calculated as follows.
Investor A: Additional Deposit After the Price Increase
Initial investment: KRW 1,000,000
Value of the initial investment: KRW 1,000,000 × 1.20 = KRW 1,200,000
Additional deposit after the price increase ends: KRW 1,000,000
Final balance: KRW 1,200,000 + KRW 1,000,000 = KRW 2,200,000
Investor B: Additional Deposit Before the Price Increase
Initial investment: KRW 1,000,000
Additional deposit before the price increase: KRW 1,000,000
Amount invested during the price increase: KRW 2,000,000
Final balance: KRW 2,000,000 × 1.20 = KRW 2,400,000
Therefore, under the assumptions above, the correct comparison is as follows.
| Category | Investor A: Deposit After the Increase | Investor B: Deposit Before the Increase |
|---|---|---|
| Total deposits | KRW 2,000,000 | KRW 2,000,000 |
| Final balance | KRW 2,200,000 | KRW 2,400,000 |
| Actual investment profit | KRW 200,000 | KRW 400,000 |
| Profit as a percentage of total deposits | 10% | 20% |
According to the author's calculations, the difference between the two investors' final balances is KRW 200,000.
Both investors experienced the same 20% increase in the value of the investment, but their profits differed depending on whether their additional KRW 1,000,000 deposit participated in that increase.
There is an important distinction to make here.
The investment's own return of 20% and each investor's profit as a percentage of total deposits are different measures.
Why Can Return Calculations Become Misleading After You Add Money to an Investment Account?
An additional deposit is not investment profit. If an account balance increases, treating the entire increase as investment performance can overstate the actual profit.
For example, suppose an investment account starts with a balance of KRW 1,000,000 and ends with a balance of KRW 2,200,000.
Simply comparing the opening and closing balances gives the following result.
(KRW 2,200,000 - KRW 1,000,000) ÷ KRW 1,000,000 × 100 = 120%
However, the calculation changes if the investor deposited an additional KRW 1,000,000 during the period.
The actual investment profit should be calculated as follows.
KRW 2,200,000 - KRW 1,000,000 - KRW 1,000,000 = KRW 200,000
The simple profit percentage calculated against total deposits of KRW 2,000,000 is 10%.
Here, 10% represents the profit earned as a percentage of the total amount contributed by the investor. It is not an annualized rate of return that accounts for the investment period and the timing of deposits.
If additional deposits have been made multiple times, it is difficult to assess investment performance using a single simple rate of return.
What Is the Difference Between Time-Weighted and Money-Weighted Returns?
Time-weighted returns are suitable for comparing the performance of investment assets or portfolios, while money-weighted returns are suitable for reflecting when an investor actually contributes or withdraws money.
In its 2026 educational materials on measuring investment returns, CFA Institute, which administers the Global Investment Performance Standards (GIPS), explains that time-weighted and money-weighted returns should be distinguished when evaluating investment performance.
The two metrics serve different purposes from the outset.
| Category | Time-Weighted Return (TWR) | Money-Weighted Return (MWR) |
|---|---|---|
| Primary purpose | Compare investment management performance | Measure actual investor performance |
| Timing of additional deposits | Removes the effects of external cash flows | Reflects deposit timing and amounts |
| Calculation method | Links returns across individual periods | Cash flow-based internal rate of return |
| Main applications | Comparing funds and portfolios | Analyzing individual investment performance |
A time-weighted return divides the investment period into subperiods based on when deposits or withdrawals occur, then links the returns from those subperiods.
For example, if the investment rises by 10% in the first half of the period and approximately 9.09% in the second half, the return over the entire period is approximately 20%.
The calculation is as follows.
(1 + 0.10) × (1 + 0.090909...) - 1 = 0.20
Even if additional funds are deposited during the investment period, calculating the investment performance of each subperiod separately prevents the inflow of external funds itself from being treated as an increase in returns.
Money-weighted returns, by contrast, reflect the investor's actual cash flows.
Even when investing in the same asset, the money-weighted return experienced by an investor can vary depending on when a large amount of money is invested.
J.P. Morgan Wealth Management also explains, in its discussion of time-weighted returns published 2026-05-22, how to separate the effects of external deposits and withdrawals and calculate returns over individual investment subperiods.
Therefore, when checking the return displayed in an investment account, it is important to first determine how that figure was calculated.
If the Price Falls Before an Additional Deposit, Could the Outcome Be Reversed Despite the Same 20% Return?
If the price falls before an additional deposit, the final account balance will depend on how much money is invested during the subsequent recovery. However, this does not mean that making an additional deposit necessarily produces a higher profit.
This time, consider a hypothetical scenario in which the price of an investment asset first falls by 20% and then rises by 50%.
Assuming an initial price of 100, the price changes as follows.
100 → 80 → 120
The investment asset's return over the entire period is 20%.
If Investor A initially invests KRW 1,000,000 and holds the investment without making any additional deposits, the ending value is KRW 1,200,000.
By contrast, if Investor B invests an additional KRW 1,000,000 when the price falls to 80, the calculation is as follows.
The final value of the initial investment is KRW 1,200,000.
Because the additional investment is purchased at 80 and the price subsequently rises to 120, it earns a return of 50%.
KRW 1,000,000 × 1.50 = KRW 1,500,000
The final account balance is KRW 1,200,000 + KRW 1,500,000 = KRW 2,700,000.
Total deposits amount to KRW 2,000,000, and the investment profit is KRW 700,000.
However, if the price had fallen again from 80 to 60, the additional investment would also have incurred a loss.
In other words, the outcome of an additional deposit depends on the actual price movements after the money is invested.
A favorable time to make an additional investment in the past is not necessarily a favorable time in the future.
How Can You Check the Actual Investment Profit in Your Brokerage Account?
To determine your actual investment profit, you need to look beyond the account's valuation and consider the initial investment, additional deposits, withdrawals, and investment period together.
You can start with the following formula.
Investment Profit = Ending Account Value + Cumulative Withdrawals - Beginning Account Value - Cumulative Additional Deposits
This calculation is based on money entering or leaving the investment account from external sources. It assumes that cash flows during the same period are not counted more than once.
For example, consider the following hypothetical account.
Beginning account value: KRW 5,000,000
Additional deposits: KRW 2,000,000
Withdrawals during the period: KRW 500,000
Ending account value: KRW 7,500,000
The investment profit is calculated as follows.
KRW 7,500,000 + KRW 500,000 - KRW 5,000,000 - KRW 2,000,000 = KRW 1,000,000
Therefore, the account is calculated to have generated an investment profit of KRW 1,000,000 during the period.
However, this calculation alone cannot determine either the money-weighted return, which accounts for the timing of deposits, or the time-weighted return.
To assess investment performance more accurately, check the dates and amounts of deposits and withdrawals in your brokerage transaction history and, when necessary, calculate a cash flow-based rate of return.
Money-weighted returns can be calculated using the internal rate of return (IRR) method, which accounts for the actual dates on which an investor contributes funds. When deposits and withdrawals occur at irregular intervals, the XIRR method can also be used to account for their specific dates.
However, when comparing calculated results, it is important to distinguish between returns over a specific period and annualized returns. Fees, taxes, dividends, and foreign currency conversion methods must also be consistent for a meaningful comparison.
Does an Account Return of 20% Mean the Same Thing as My Personal Investment Return of 20%?
The two figures can be meaningfully compared as equivalent only when they are calculated on the same basis.
An investment rising by 20% may refer to its price performance or total return over a given period.
By contrast, a personal investment account showing a return of 20% may represent the unrealized gain or loss percentage on specific holdings, the overall account's return over a particular period, or another metric, depending on the calculation method used by the brokerage.
It is particularly important not to compare the figures directly in the following situations.
Additional funds were deposited or some funds were withdrawn during the investment period.
The same security was purchased on different dates.
Dividends were reinvested or held as cash.
Valuations use different bases for Korean won and foreign currencies.
Fees and taxes are included in one calculation but excluded from another.
When comparing investment performance, the first things to examine are not the size of the reported returns but what those returns measure, the periods they cover, and how cash flows are accounted for.
The principles of return measurement available as of 2026-10-27 also distinguish time-weighted returns from money-weighted returns as metrics designed for different purposes.
A larger final account balance does not necessarily indicate better investment management performance. Likewise, even when the same return is reported for an investment, that does not mean every investor earned the same actual profit.
When reviewing your own investment account, start by checking the dates and amounts of additional deposits in your recent transaction history. Those records provide a starting point for understanding the difference between your final account balance and the displayed return.
※ This article is provided for informational purposes to help readers understand market dynamics and does not constitute a recommendation to invest in any particular security or asset. You are responsible for your own investment decisions and their outcomes.