

Switching from the Youth Leap Account to the 2 Round of the Youth Future Savings Plan: Why You Should Not Close Your Existing Account First and the Correct Procedure
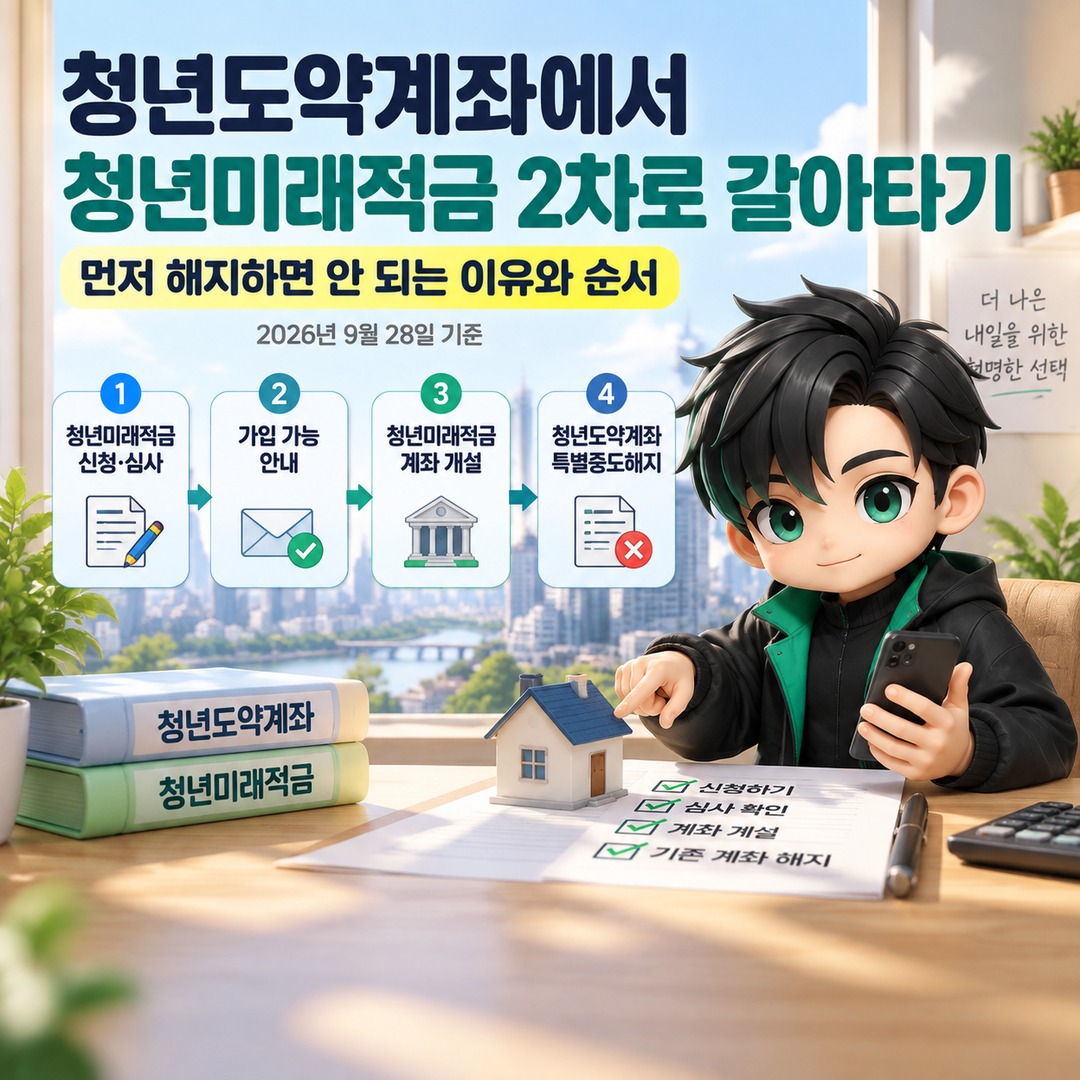
If you currently hold a Youth Leap Account, you should not close your existing account before applying for the 2 round of the Youth Future Savings Plan. As of 2026-09-28, the Financial Services Commission has outlined the following sequence: apply for the Youth Future Savings Plan and undergo eligibility screening → receive confirmation of eligibility → open a Youth Future Savings Plan account → complete a special early termination of the Youth Leap Account.
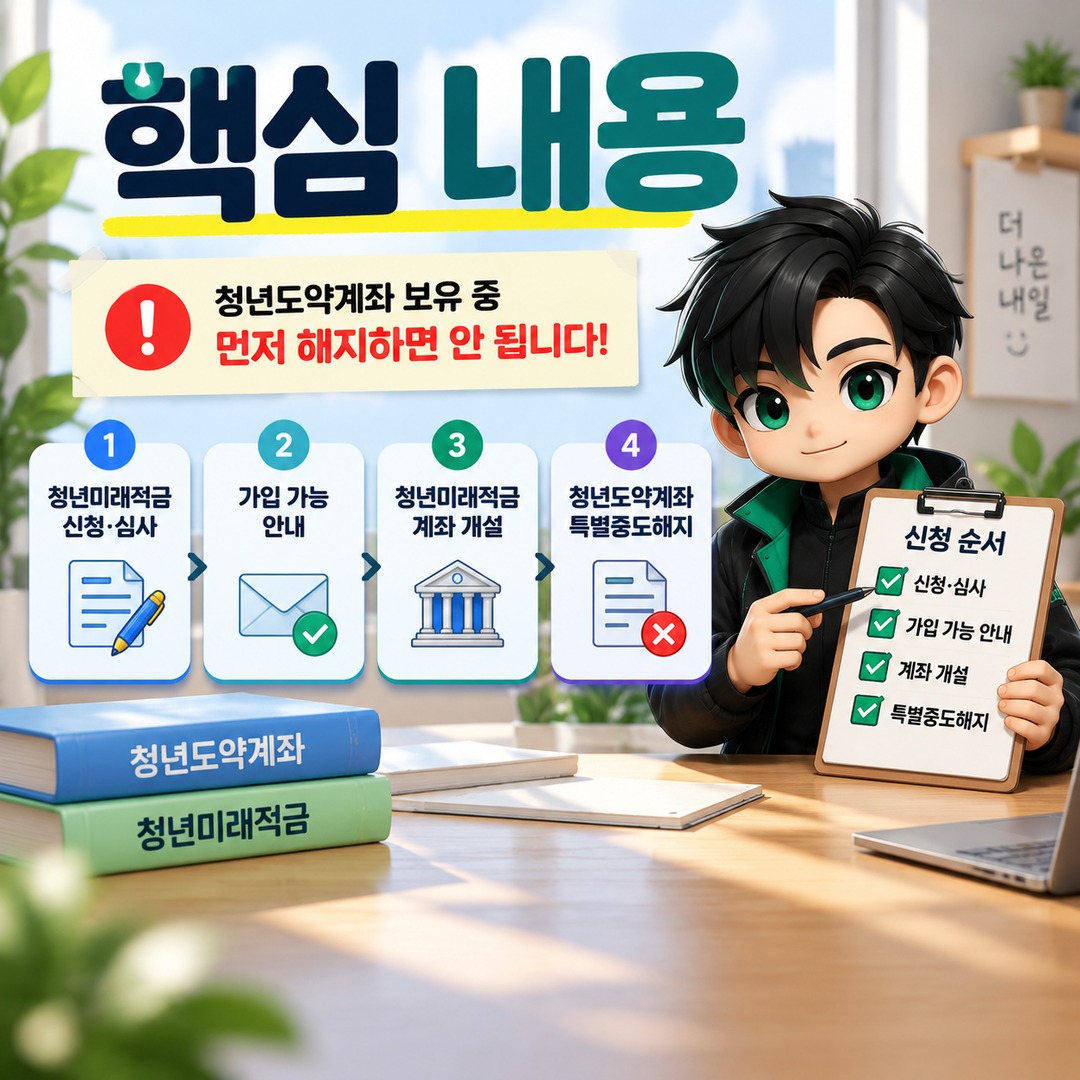
With existing Youth Leap Account holders once again allowed to switch during the 2 recruitment round of the Youth Future Savings Plan, the most important question after confirming eligibility is straightforward: “When should I close my existing Youth Leap Account?”
Why You Should Not Close Your Youth Leap Account First
This switching process is not simply a matter of closing your Youth Leap Account and then opening a new Youth Future Savings Plan account.
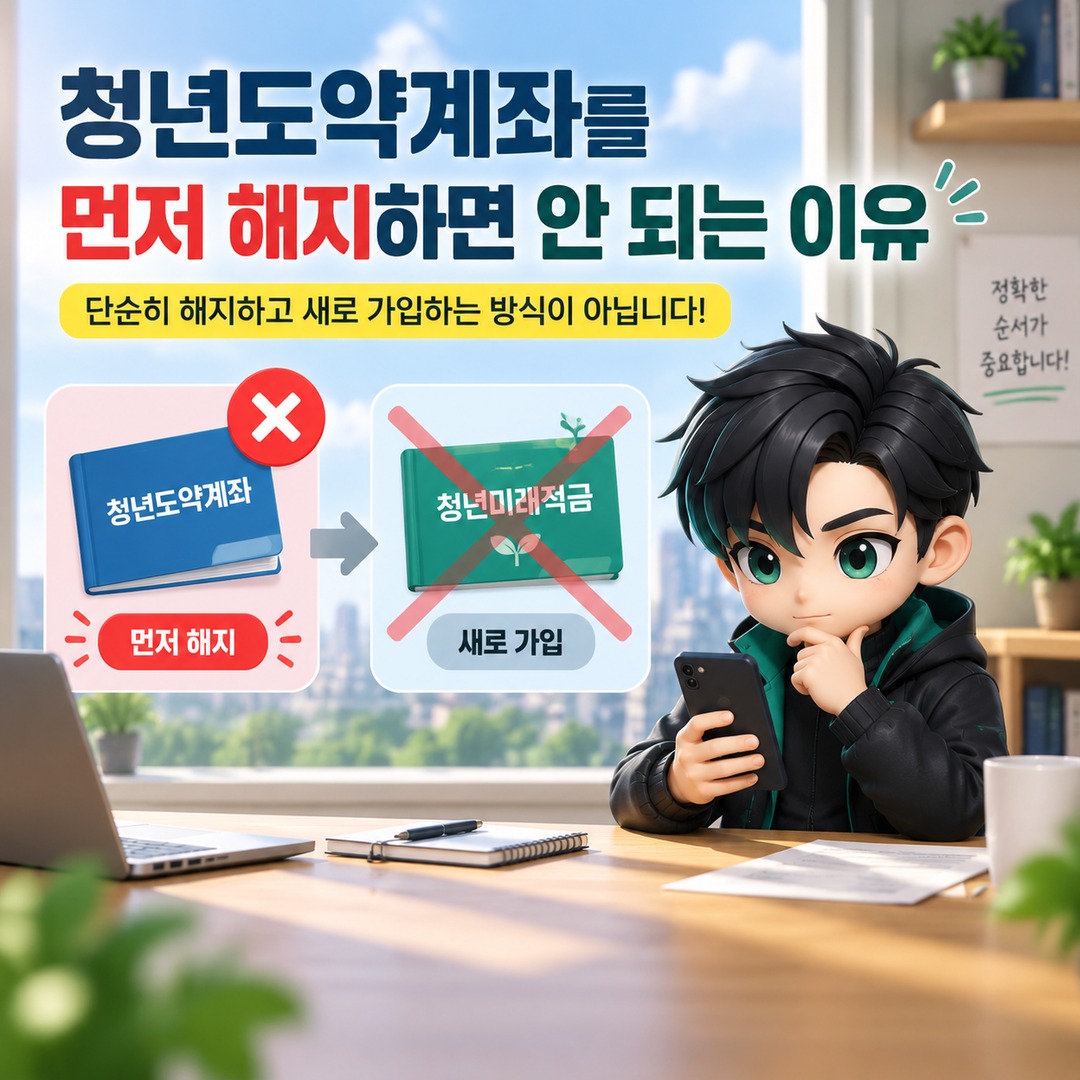
The Financial Services Commission has announced the following procedure for the 2 recruitment round.
1. Apply for the Youth Future Savings Plan
2. Undergo eligibility screening
3. Confirm notification of eligibility
4. Open a Youth Future Savings Plan account
5. Complete a special early termination of the Youth Leap Account for the purpose of joining the Youth Future Savings Plan
In other words, the process is designed to confirm eligibility for the new account before closing the existing account.
The distinction between ordinary early termination and special early termination is particularly important. According to the official guidance issued during the initial recruitment round, participants who specially terminated their Youth Leap Accounts to transfer to the Youth Future Savings Plan would receive government contributions on their previous deposits and retain their tax exemption on interest income, unlike those who terminated their accounts under ordinary conditions.
Therefore, voluntarily closing an account through ordinary early termination must be distinguished from completing a special early termination under the official switching procedure.
Application and Account Opening Dates Are Different for the 2 Round
Applying during the 2 round of the Youth Future Savings Plan does not mean that an account will be opened immediately.
| Stage | 2 Round Schedule |
|---|---|
| Application | October 7~16 |
| Eligibility screening | October 19~November 13 |
| Account opening | November 16~27 |
Applicants whose birth years end in an odd digit may apply on October 7, while those whose birth years end in an even digit may apply on October 8. From October 12 through 16, applications are accepted regardless of birth year.
Therefore, applying on October does not mean you need to close your Youth Leap Account immediately.
The official sequence is to pass eligibility screening, receive confirmation that you can enroll, open a Youth Future Savings Plan account, and then complete the special early termination of your Youth Leap Account according to the subsequent instructions.
The Financial Services Commission has stated that it plans to provide additional details about the switching procedure before the enrollment period for the 2 round begins.
Can You Continue Contributing to Both the Youth Leap Account and the Youth Future Savings Plan Simultaneously?
As a general rule, maintaining overlapping enrollments in both products and continuing to make contributions to both through the ordinary enrollment process is not permitted.
The Korea Inclusive Finance Agency also explains in its product guidance that the Youth Future Savings Plan allows 1 account per person across all participating financial institutions, and that overlapping enrollment is restricted for holders of Youth Hope Savings Accounts and Youth Leap Accounts.
However, the switching procedure is specifically designed to allow participants to open a Youth Future Savings Plan account first and then specially terminate their Youth Leap Account.
During the initial recruitment round, the new Youth Future Savings Plan account was opened in a KRW 0 status, with contributions restricted until the special early termination of the Youth Leap Account was completed. Contributions to the Youth Future Savings Plan could then begin.
For the 2 recruitment round, the Financial Services Commission has again specified the sequence of opening the new account before completing special early termination. However, because additional guidance on the detailed processing schedule and procedures is still forthcoming, applicants should carefully review the notifications they receive when proceeding with the switch.
What Happens to Your Existing Youth Leap Account Benefits When You Switch?
A special early termination completed for the purpose of officially transferring to the new savings product is not treated in the same way as an ordinary early termination.
According to the official guidance applied during the initial recruitment round, participants who specially terminated their Youth Leap Accounts for the purpose of transferring could receive the following benefits.
Payment of government contributions on previously deposited funds
Continued tax exemption on interest income
Application of the base interest rate and any preferential interest rates for which the participant qualified
Recognition of certain preferential interest rate conditions based on the extent to which they had been satisfied by the date of special early termination
The system is also designed to include the enrollment period and contribution amounts from the Youth Leap Account when calculating eligibility for credit score bonuses for participants who switch to the Youth Future Savings Plan. Youth Future Savings Plan participants may qualify for additional points in their personal credit assessment scores if they meet conditions such as remaining enrolled for 2 year and making contributions of at least KRW 8,000,000.
However, the actual amount each participant receives upon terminating a Youth Leap Account will vary depending on the enrollment date, contribution amounts, government contributions, applicable interest rates, and preferential interest rate conditions.
Switching to the Youth Future Savings Plan Is Not Automatically More Advantageous
Being allowed to switch and determining whether switching is financially beneficial are two separate matters.
The Youth Future Savings Plan is a flexible installment savings product with a 3-year maturity, allowing monthly contributions ranging from KRW 1,000 to a maximum of KRW 500,000. Under the current system, government contributions equal 6% of actual deposits for the standard category and 12% for the preferential category. Interest income is also tax-exempt.
By contrast, if you have already maintained your Youth Leap Account for a considerable period, you should also compare the remaining time until maturity and the benefits accumulated so far.
The outcome will depend particularly on whether you qualify for the standard or preferential category of the Youth Future Savings Plan and how much you can realistically contribute each month.
Under a simplified calculation assuming monthly contributions of KRW 500,000 for all 36 months, the total principal contributed by the account holder would be KRW 18,000,000.
Applying the current government contribution rate of 6%, the maximum government contribution for the standard category would be KRW 1,080,000, while the maximum for the preferential category at the 12% rate would be KRW 2,160,000.
Standard category: KRW 500,000 × 6% × 36 months = KRW 1,080,000
Preferential category: KRW 500,000 × 12% × 36 months = KRW 2,160,000
These amounts are calculated using the current contribution rates and assume that KRW 500,000 is deposited every month without interruption. The actual amount received at maturity will also include interest based on the applicable interest rate.
In addition, the government's proposed 2027 budget includes measures such as increasing the preferential-category contribution rate from 12% to 15%. However, as of 2026-09-28, these changes have not been finalized through National Assembly deliberations. The Financial Services Commission has stated that, if the budget proposal is approved, it plans to retroactively pay the increased preferential government contributions to existing participants as well.
Three Things to Check Before October 7
If you currently hold a Youth Leap Account and are considering switching during the 2 round, there are several things you should check before closing your existing account.
First, confirm whether you meet the eligibility requirements for the 2 round of the Youth Future Savings Plan. As with the initial recruitment round, eligibility criteria such as individual income and household income apply.
Second, check how long you have been contributing to your current Youth Leap Account and the estimated amount you would receive upon termination. Someone who has maintained the account for a long time is not in the same financial position as someone who enrolled recently.
Third, do not voluntarily close your Youth Leap Account before completing the required steps. Under the switching procedure announced by the Financial Services Commission, you must first receive confirmation of eligibility for the Youth Future Savings Plan and open the new account before applying for special early termination of the existing account.
As of 2026-09-28, more detailed instructions beyond those already announced are expected to be released before applications open for the 2 round. When applying, it is advisable to check the notifications sent by the Korea Inclusive Finance Agency and the latest information on the official Youth Future Savings Plan website before taking any final action.
※ This article is provided for informational purposes to help readers understand market developments and does not constitute an investment recommendation regarding any specific security or asset. All final investment decisions and responsibility rest with the individual investor.