

Refinancing a Mortgage Before 3 Years: Is It Worth Paying an Early Repayment Fee for a 0.5%p Lower Interest Rate?
Refinancing your mortgage at a lower interest rate can be beneficial even if less than 3 years have passed since you took out the loan. The key is to compare not only the interest rate difference but also your future interest savings, early repayment fees, and the costs of obtaining a new loan.
For example, if your outstanding loan balance is KRW 300,000,000 and your annual interest rate falls from 4.5% to 4.0%, the simple first-year interest difference calculated using your current balance is KRW 1,500,000.
However, your actual savings will depend on how quickly you repay the principal and the terms of your loan. In particular, if less than 3 years have passed since the loan was issued, you should first check the early repayment fee on your existing mortgage.
How Much Is the Early Repayment Fee If Your Mortgage Is Less Than 3 Years Old?
An early repayment fee is a charge that may apply when you repay a loan before the agreed repayment period ends.
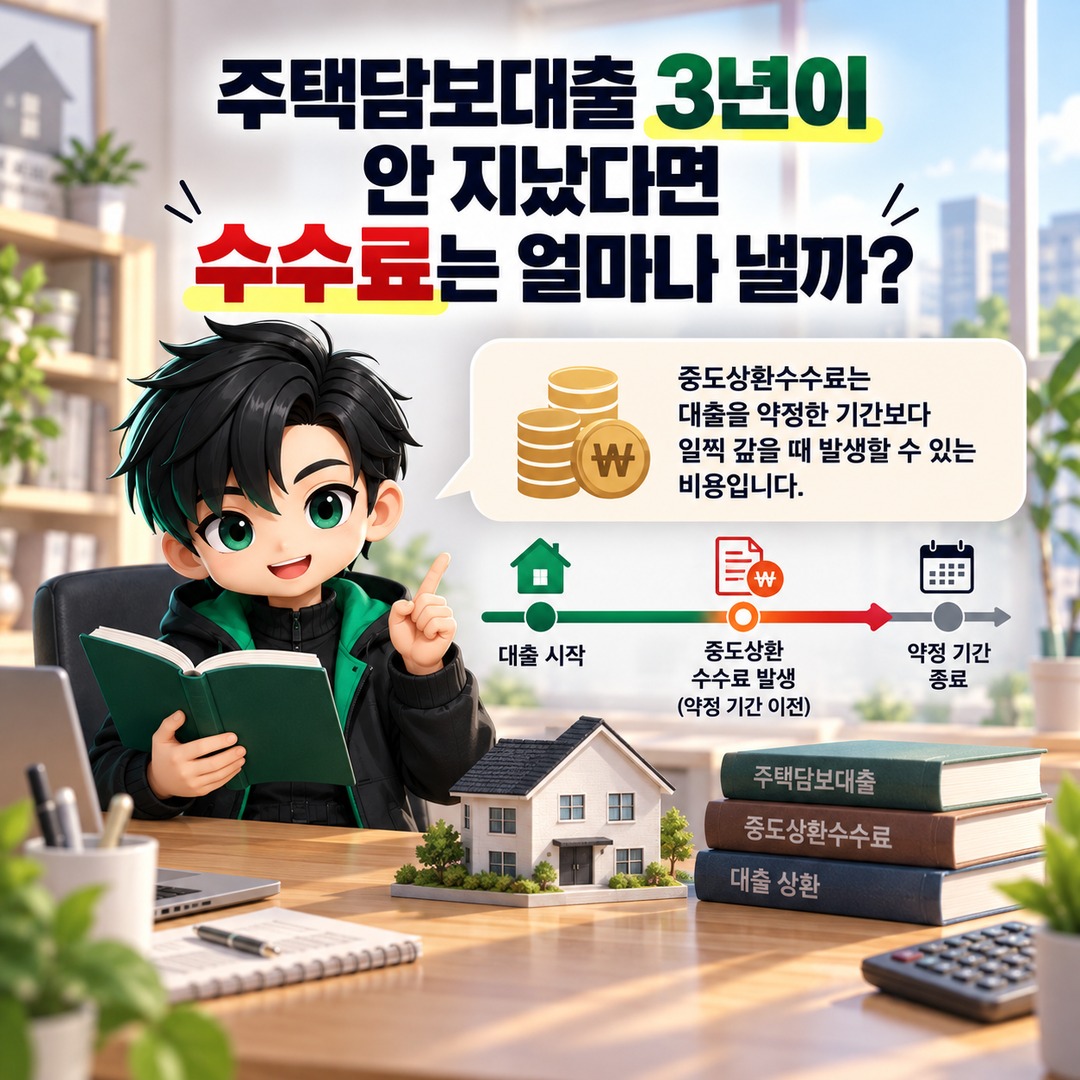
Under the Financial Consumer Protection Act, early repayment fees are generally restricted. However, they may exceptionally be charged when a loan is repaid within 3 years of its origination date.
Starting from 2025-01-13, the system was revised to require financial institutions to calculate early repayment fees based on costs actually incurred.
According to the Financial Services Commission's announcement at the time, the average early repayment fee rate for fixed-rate mortgages in the banking sector decreased from 1.43% to 0.56%.
However, 0.56% was the banking sector average at that time, not a fee rate applicable to every mortgage.
The revised fee rates do not automatically apply retroactively to existing loans contracted before 2025-01-13. Even if an existing contract is renewed, it may be excluded from the revised rules if its principal contractual terms remain substantially unchanged.
As of 2026-10-09, you should verify the fee rate actually applicable to your mortgage based on the original contract date and agreed terms.
How Much Can You Actually Save With an Outstanding Balance of KRW 300,000,000 and a 0.5%p Interest Rate Difference?
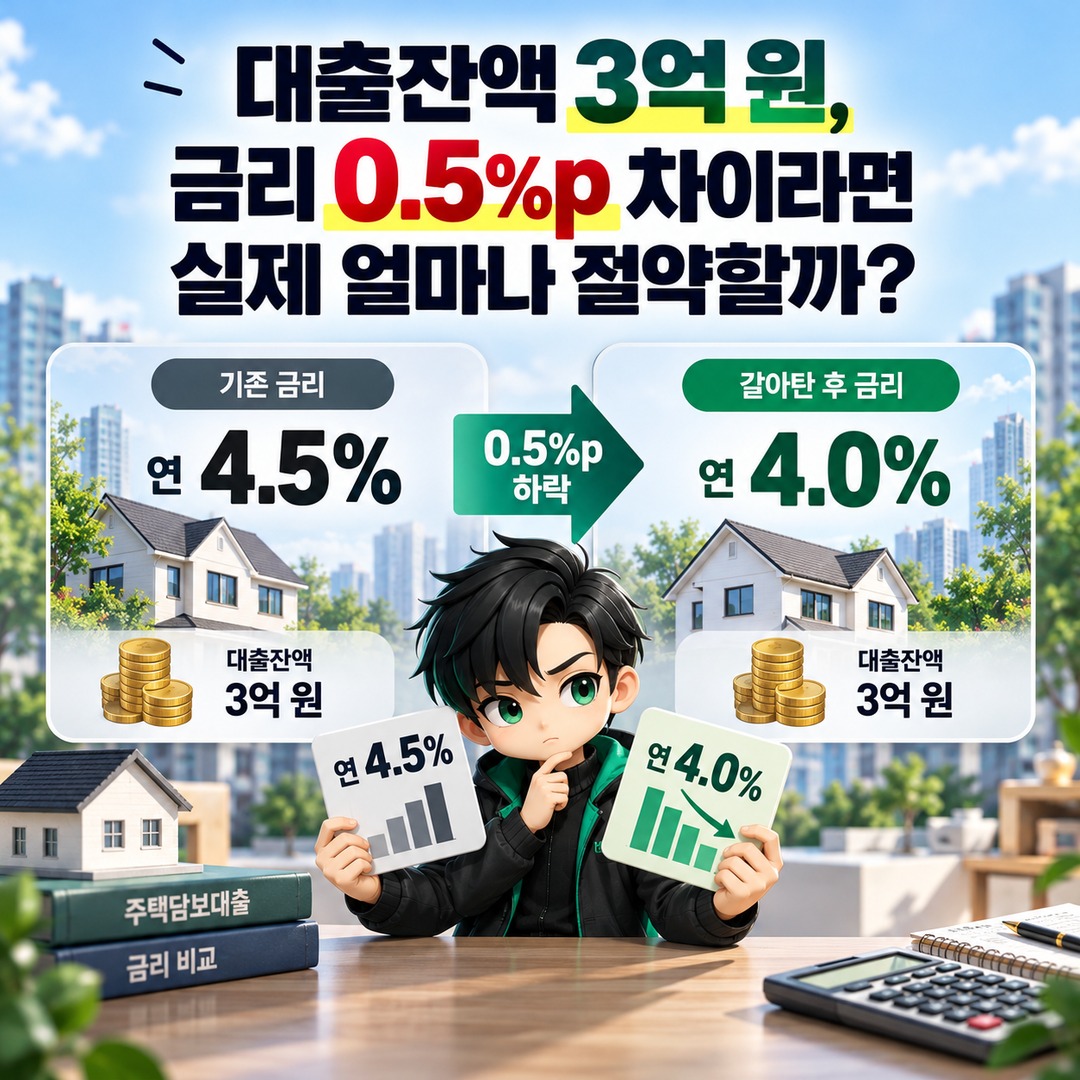
Suppose you have an outstanding mortgage balance of KRW 300,000,000 and your annual interest rate decreases from 4.5% to 4.0%.
Assuming both loans have the same principal and comparison period, and that the principal balance does not decrease, the simplified calculation is as follows.
| Comparison Item | Calculation Result |
|---|---|
| Current mortgage interest rate | Annual 4.5% |
| Refinanced mortgage interest rate | Annual 4.0% |
| Interest rate difference | 0.5%p |
| Simple annual interest difference | KRW 1,500,000 |
| Simple average monthly interest difference | KRW 125,000 |
The calculation is as follows.
KRW 300,000,000 × 0.005 = Annual KRW 1,500,000
There is an important point to understand here.
The Annual KRW 1,500,000 Figure Assumes That the Principal Remains Unchanged.
If your mortgage uses equal principal-and-interest payments or equal principal payments, the outstanding principal decreases each month, which means your actual interest savings will also differ.
Furthermore, if the existing and new loans have different remaining terms, fixed-rate periods, or repayment methods, you should not compare their total costs based solely on the interest rate difference.
Is Refinancing Still Worthwhile If You Have to Pay an Early Repayment Fee of KRW 1,000,000?
If your outstanding loan balance is KRW 300,000,000 and the interest rate difference is 0.5%p, the decision depends on the combined amount of the early repayment fee and new loan costs.
You can calculate the time needed to recover your refinancing costs using the previously calculated simple average monthly interest difference of KRW 125,000.
| Total Refinancing Cost | Simple Cost Recovery Period |
|---|---|
| KRW 500,000 | 4 months |
| KRW 1,000,000 | 8 months |
| KRW 1,500,000 | 12 months |
| KRW 2,000,000 | 16 months |
*Author's calculation. Assumes the outstanding loan balance remains at KRW 300,000,000 and the annual interest rate difference stays at 0.5%p. Changes resulting from principal repayment are not reflected.*
For example, if the combined early repayment fee and new loan costs amount to KRW 1,000,000, the calculation suggests that the costs can be recovered through approximately 8 months of interest savings.
On the other hand, if you plan to sell your home or repay the loan in full after 6 months, the outcome may be different even under the same conditions.
Therefore, what matters is not only how quickly you can recover the costs but also how long you actually intend to keep the mortgage.
Can You Calculate the Early Repayment Fee Simply by Multiplying the Outstanding Balance by the Fee Rate?
To calculate an early repayment fee, you need to check both the calculation method specified in your contract and the period during which the fee applies.
Some mortgages use a structure in which the early repayment fee decreases as more time passes after the loan is issued.
An example formula that may be used for such contracts is as follows.
Early repayment amount × Contractual fee rate × (Remaining days in the fee period ÷ Total days in the fee period)
Suppose the following conditions apply.
Early repayment amount: KRW 300,000,000
Contractual fee rate: 0.6%
Fee application period: 3 years
Elapsed period: 2 years
Remaining fee period: 1 years
Using a simplified calculation based on 2 years elapsed and 1 years remaining, the result is as follows.
KRW 300,000,000 × 0.006 × (1 ÷ 3) = KRW 600,000
The calculated early repayment fee in this example is approximately KRW 600,000.
However, actual contracts may differ in how they calculate the number of days, apply fee exemptions, and determine the principal amount subject to the fee.
Therefore, this is only an illustrative calculation. For an accurate figure, you should confirm the amount calculated by your existing bank based on your actual planned repayment date.
Is It Better to Wait Until 3 Years Have Passed or Refinance Now?
Comparing the interest savings available during the remaining period before the 3-year mark with the fee payable for refinancing now can help you make a decision.
For example, suppose 6 months remain until the early repayment fee exemption takes effect.
Assume your outstanding loan balance is KRW 300,000,000, the interest rate difference is 0.5%p, and the currently calculated early repayment fee is KRW 600,000.
Under the simplified assumption that the principal remains unchanged, the interest difference over 6 months would be KRW 750,000.
KRW 1,500,000 × (6 ÷ 12) = KRW 750,000
If the early repayment fee for refinancing now is KRW 600,000, the amount remaining after subtracting that fee from the simple interest difference over 6 months is KRW 150,000.
However, if the new loan incurs additional costs of KRW 200,000, this difference disappears.
Conversely, if there are no additional costs for the new loan and the actual interest savings remain consistent with the assumptions, refinancing now may be more advantageous than waiting.
There is one more condition to consider.
There is no guarantee that the lower interest rate currently offered will still be available after 6 months. Choosing to wait before refinancing also requires considering the possibility that future interest rates and loan approval conditions may change.
A Lower Monthly Payment Does Not Necessarily Mean Lower Total Interest
Comparing only the monthly payments when refinancing a mortgage can lead to an incorrect assessment of the actual costs.
For example, if your existing mortgage has 20 years remaining but you set the term of your new mortgage at 30 years, your monthly payment may decrease.
However, because you will be spreading principal repayment over a longer period, you need to calculate the total interest burden separately.
It is particularly important to compare the following factors on an equivalent basis.
Outstanding loan balance and new loan amount
Remaining term of the existing mortgage and term of the new mortgage
Repayment method, such as equal principal-and-interest payments or equal principal payments
Fixed or variable interest rates and conditions for interest rate adjustments
Conditions for preferential interest rates and how long those benefits remain valid
Even if the advertised interest rate is lower, the rate actually applied to your loan may differ if you fail to meet preferential-rate requirements, such as salary deposits or credit card spending thresholds.
Therefore, rather than focusing solely on the lowest advertised rate, you should compare the interest rate you will actually receive and the applicable repayment conditions.
What Should You Check With Your Bank Before Refinancing a Mortgage?
You should first ask your existing bank to confirm your exact outstanding loan balance and the early repayment fee based on your planned repayment date.
At the new bank, you should check the interest rate available after the actual credit assessment, the maximum loan amount, the repayment period, and any associated costs.
The interest rate displayed on a loan comparison platform does not always match the final approved rate.
The refinancing process may involve not only repaying the existing mortgage but also undergoing a new loan assessment and completing procedures related to the collateral.
In particular, refinancing does not mean that a new loan for the same amount will automatically be approved simply because you already have a mortgage. The outcome may vary depending on your income, debts, collateral value, lending regulations, and the financial institution's underwriting criteria.
If your existing mortgage is a government-backed financing product or is subject to special contractual conditions, your refinancing eligibility and costs may differ from those of a standard bank mortgage.
How Large Must the Interest Rate Difference Be for Refinancing to Make Financial Sense?
There is no single interest rate difference that makes refinancing worthwhile for everyone.
The larger your outstanding loan balance, the greater the potential interest savings from the same rate difference. However, early repayment fees and other associated costs must also be taken into account.
The simplest decision-making formula is as follows.
Expected Interest Savings − Early Repayment Fee − New Loan Costs = Expected Net Savings
However, because the principal balance may decrease or interest rates may change, an accurate assessment requires comparing the repayment schedules of the existing and new loans over the same period.
If the expected net savings are positive, refinancing may be financially advantageous. Nevertheless, it is advisable to make a decision only after reviewing the loan assessment results and the risks associated with future interest rate changes.
If you are considering refinancing your mortgage as of 2026-10-09, start by requesting an estimate of the early repayment fee from your existing bank, then confirm the actual applicable interest rate and costs with the new bank.
※ This article is provided for reference purposes to help readers understand market conditions and does not constitute an investment recommendation for any specific security or asset. Final decisions and investment responsibility rest with the individual.