

Why NVIDIA's USD 108,000,000,000 Forecast Excludes China Revenue and How to Assess the H200 Factor
NVIDIA's next-quarter revenue forecast of USD 108,000,000,000 does not include data center computing revenue from China. However, this should not be interpreted as meaning that NVIDIA's total revenue from China is 0. Even if sales of H200 to China increase, supply constraints mean investors must separately assess whether those sales would translate directly into additional revenue.
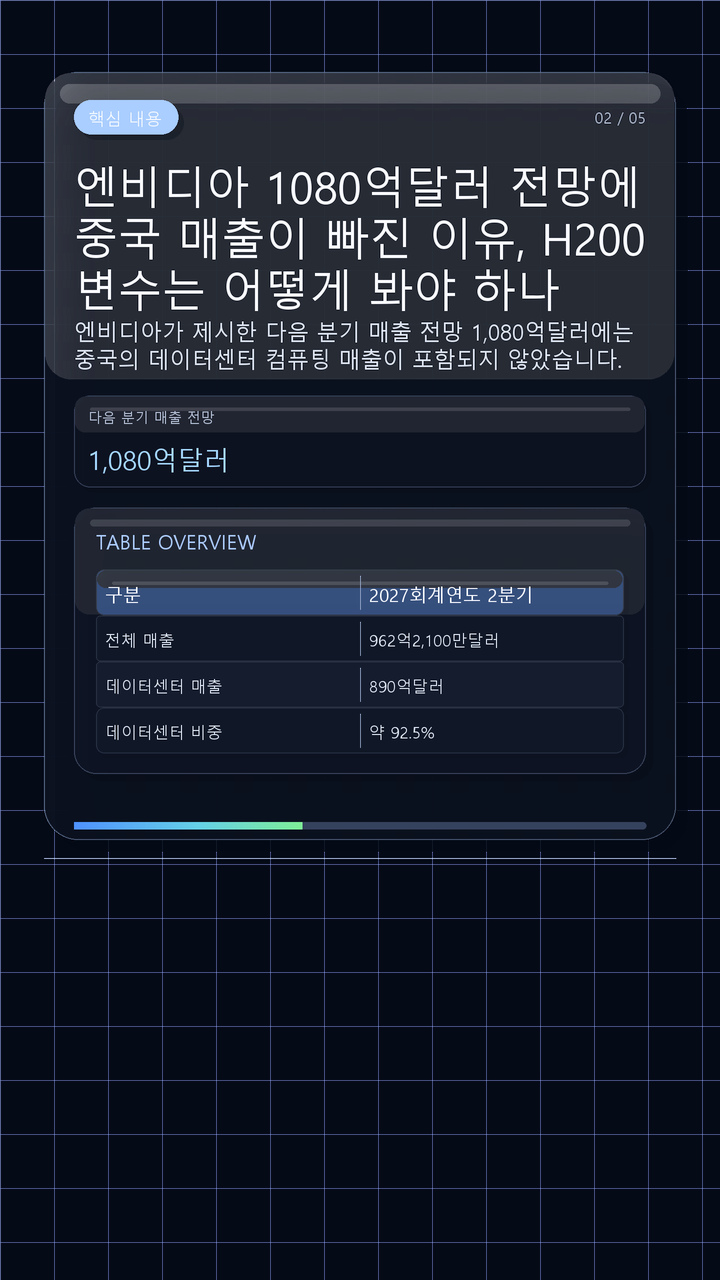
NVIDIA reported revenue of USD 96,221,000,000 in the 2 quarter of fiscal 2027, including data center revenue of USD 89,000,000,000. For the following quarter, the company projected revenue of USD 108,000,000,000±2% without assuming any data center computing revenue from China.
Excluding China Revenue Does Not Mean 'All China Revenue Is 0'
A closer look at NVIDIA's official wording shows that the company 'did not assume any data center computing revenue from China in its forecast.' This does not mean that all China-related revenue, including gaming GPUs and other business segments, will disappear.
This distinction matters because the data center business is the core of NVIDIA's financial performance.
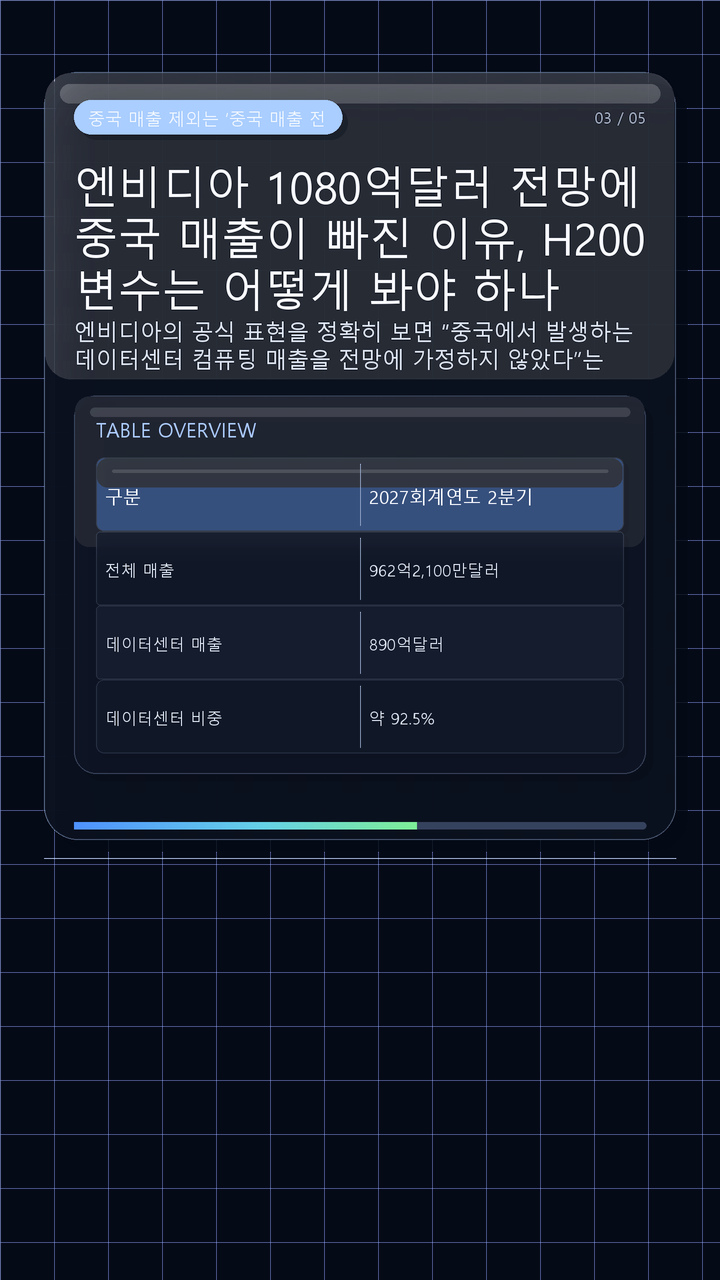
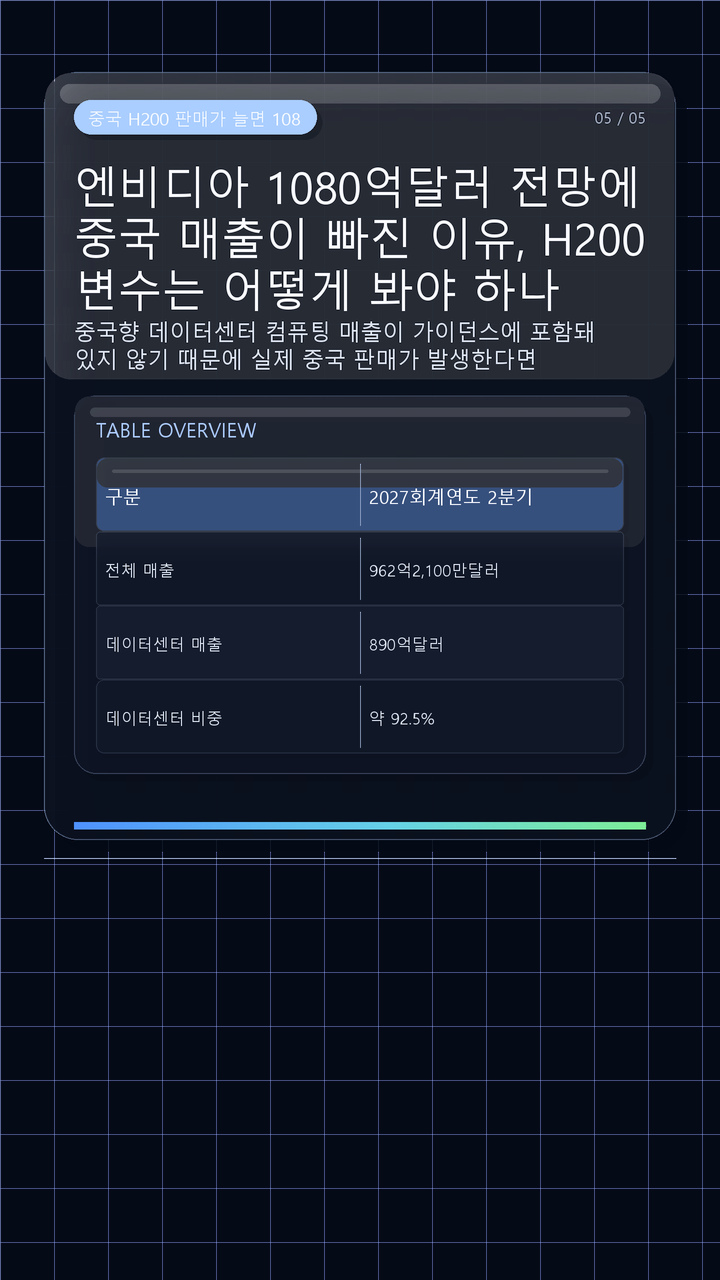
In the 2 quarter of fiscal 2027, total revenue was USD 96,221,000,000, while data center revenue reached USD 89,000,000,000. A simple calculation shows that data centers accounted for approximately 92.5% of total revenue.
| Category | Fiscal 2027, 2 Quarter |
|---|---|
| Total revenue | USD 96,221,000,000 |
| Data center revenue | USD 89,000,000,000 |
| Data center share | Approximately 92.5% |
Therefore, when evaluating developments involving China, the key question is not simply whether NVIDIA is 'reentering the Chinese market,' but how many AI chips for data centers are actually shipped and recognized as revenue.
What Is the Actual Range of the USD 108,000,000,000 Forecast?
NVIDIA's next-quarter revenue guidance is not a single figure of USD 108,000,000,000, but a range of ±2%. Expressed as individual figures, the official guidance is as follows.
Lower end: Approximately USD 105,840,000,000
Midpoint: USD 108,000,000,000
Upper end: Approximately USD 110,160,000,000
Comparing actual revenue of USD 96,221,000,000 in the previous quarter with the midpoint of USD 108,000,000,000 suggests that NVIDIA expects approximately 12.2% in quarter-over-quarter growth.
What deserves even closer attention is that the company prepared this forecast without including data center computing revenue from China. Rather than relying on a recovery in Chinese sales, NVIDIA expects quarterly revenue exceeding USD 100,000,000,000 based solely on demand for AI infrastructure in the United States and other regions.
If H200 Sales to China Increase, Will That Revenue Be Added Directly to USD 108,000,000,000?
Not necessarily.
Because data center computing revenue from China is not included in the guidance, actual sales to China could, on the surface, provide an additional source of revenue. However, NVIDIA has stated that supply is currently insufficient to meet demand for AI semiconductors.
In other words, even if NVIDIA sells an additional USD 1,000,000,000 worth of H200 products to China, it would be difficult to simply assume that USD 1,000,000,000 would automatically be added to its existing revenue forecast.
If the company could already sell the same volume of products to customers in the United States or other regions, sales to China might not create new demand. Instead, they could primarily represent a shift in the geographic destination of sales.
For example, if all available products are already being sold, one possible outcome is:
Increased sales to China → Increased total sales volume
However, another possible outcome is:
Increased sales to China → Some products previously destined for other regions are redirected to China
Therefore, assessing the impact of reopening the Chinese market requires examining not only whether sales are permitted, but also whether additional production capacity becomes available.
Can H200 Be Sold in China Immediately After Receiving U.S. Approval?
The situation is not that simple.
According to Reuters, the United States allowed certain Chinese companies, including Alibaba, Tencent, and ByteDance, to purchase H200 in May 2026, but actual deliveries were subsequently delayed for a considerable period. In July, a U.S. government official explained that shipments had begun, although volumes remained extremely small.
Therefore, evaluating H200 revenue from China requires considering at least all of the following stages.
U.S. export authorization → Permission to import into China → Actual orders → Product supply → Customer delivery → Revenue recognition
Resolving just one intermediate stage does not automatically lead to large-scale revenue.
Indeed, because of these uncertainties, NVIDIA did not assume any data center computing revenue from China when issuing its USD 108,000,000,000 guidance.
Would a Recovery in China Revenue Automatically Be Good News for NVIDIA's Stock Price?
An expansion of the Chinese market could be positive because it would increase the market accessible to NVIDIA. However, this factor alone is not enough to determine the direction of its stock price.
First, actual sales volume matters. Even if export approvals expand, the impact on earnings could remain limited if orders or supply volumes are small.
Second, supply conditions are important. NVIDIA has stated that it faces supply constraints, with customer demand exceeding available production capacity. Shortages of components, including memory, have also been identified as factors that could limit the pace of growth.
Third, the product mix matters. Even if sales to China increase, profitability may differ by product and from that of the latest AI platforms sold in other regions.
Therefore, rather than relying on the simplistic equation 'Resumption of China sales = Surge in NVIDIA earnings,' it is more accurate to examine whether actual data center revenue from China and overall supply volumes increase simultaneously.
China-Related Figures to Watch in NVIDIA's Next Earnings Report
In the next earnings report, it is worth examining the actual figures before focusing on headlines about China.
The first thing to check is whether NVIDIA actually generated data center computing revenue from China. Because this revenue is not included in the current 3-quarter guidance, any China revenue recorded in the actual results would indicate that the assumptions underlying the company's forecast had changed.
Next is total data center revenue. The data center business currently generates quarterly revenue of USD 89,000,000,000 and accounts for more than 90% of total revenue, making it the primary driver of NVIDIA's growth.
Finally, investors should examine expanded shipments to China alongside overall supply capacity. If sales to China increase while total shipment volumes remain unchanged, the company may simply have shifted sales between regions. If sales to China and other regions increase simultaneously, that would also provide evidence of expanded production capacity.
Ultimately, the most important question surrounding NVIDIA's China exposure does not end with 'Can NVIDIA sell H200 in China?'
What investors really need to determine is whether sales to China replace existing revenue or generate additional revenue by increasing NVIDIA's total sales volume. The exclusion of China data center computing revenue from the USD 108,000,000,000 guidance provides a benchmark for evaluating that distinction.