

Does Receiving a Small Business Policy Loan Eligibility Certificate Guarantee Approval? General Business Stabilization Loans Still Require Bank Review
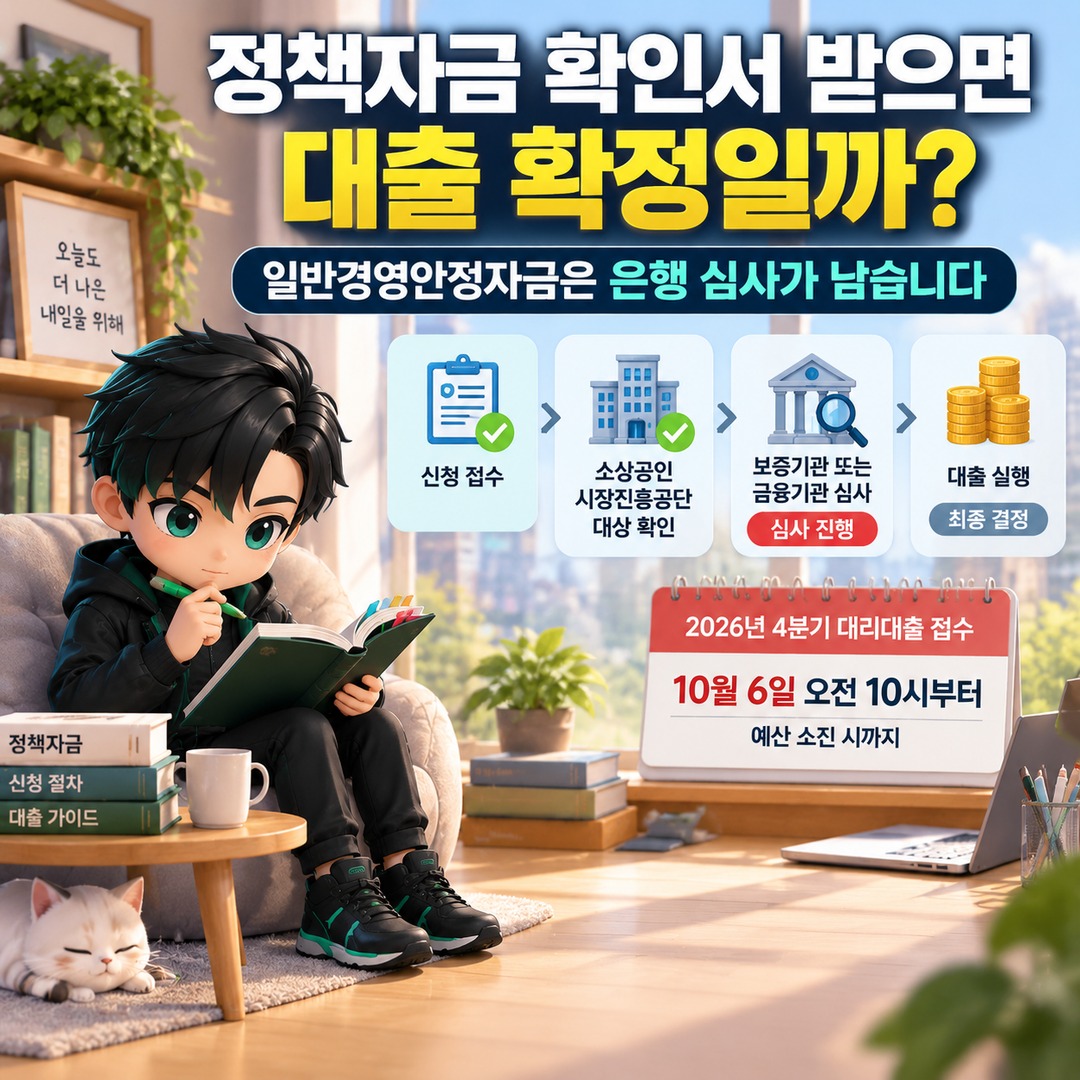
Receiving an eligibility certificate for the Small Business General Business Stabilization Fund does not guarantee loan approval. Because the program uses an indirect lending system, applicants must still pass a guarantee institution's or financial institution's review after the Small Enterprise and Market Service (SEMAS) confirms their eligibility before the loan can actually be disbursed.
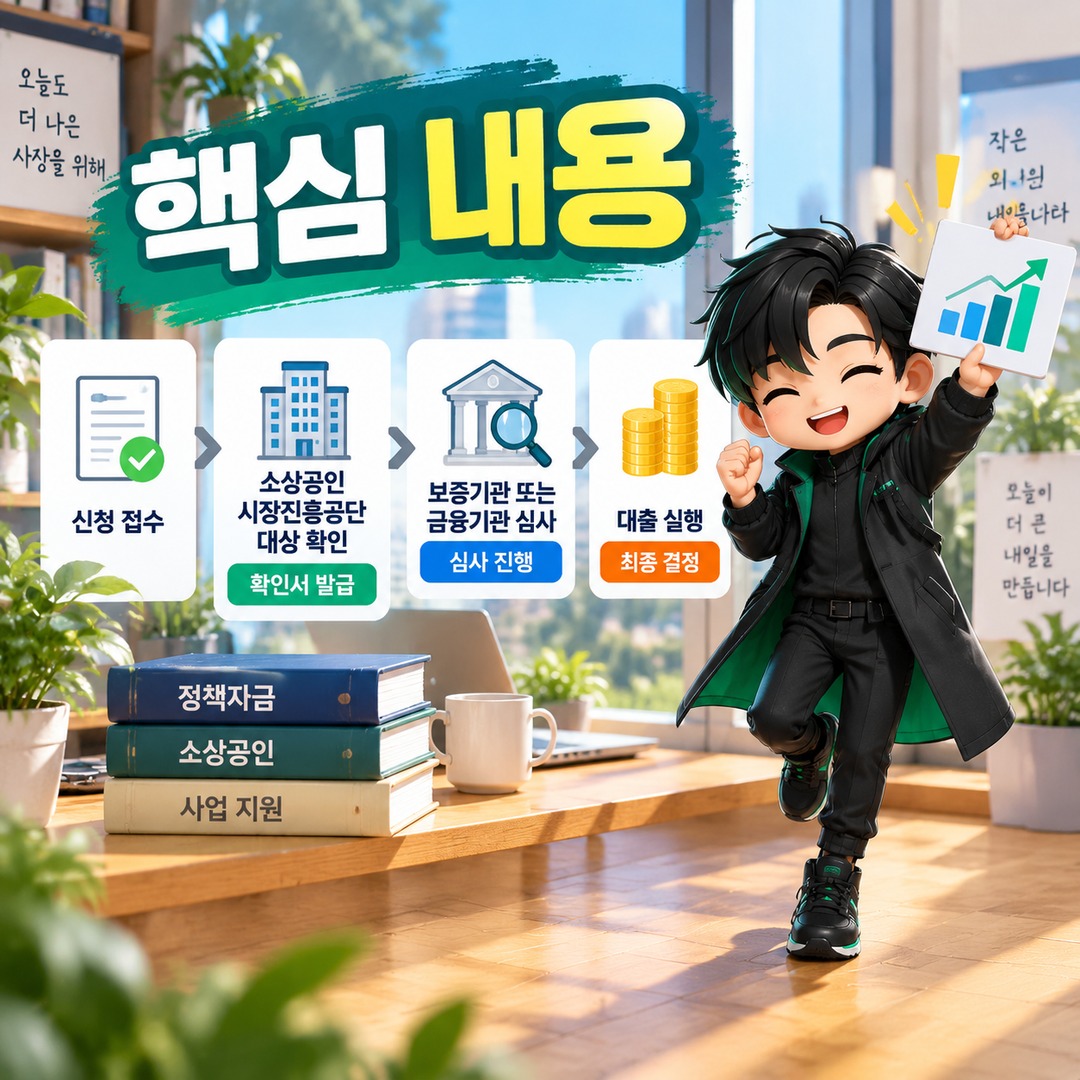
Applications for indirect loans in the 4 quarter of 2026 are scheduled to be accepted from 10 a.m. on October 6 until the budget is exhausted. If you are preparing to apply, it is important not to confuse receiving an eligibility certificate with actually receiving the loan funds.
What Exactly Does an Eligibility Certificate Confirm?
An eligibility certificate is, as its name suggests, a document issued at the stage when SEMAS verifies whether an applicant qualifies for the relevant policy financing program.
In 2026, the General Business Stabilization Fund is available to ordinary small business owners regardless of how long they have been operating, with an annual loan limit of 7 thousand won per business. However, 7 thousand won represents the program's maximum limit, not a guaranteed loan amount.
The process is easier to understand when divided into separate stages.
| Stage | What Is Reviewed? | Is the Loan Confirmed? |
|---|---|---|
| Policy loan application | Application for policy financing and eligibility | Not confirmed |
| Eligibility verification | Whether the applicant qualifies for the policy financing program | Not confirmed |
| Guarantee review | Creditworthiness, business viability, and other factors when a guarantee certificate is used | Loan not yet disbursed |
| Financial institution review | Whether a loan can be granted and the amount available | Determined by the review results |
| Loan agreement and disbursement | Funds are released after the final agreement | Loan actually disbursed |
The government's 2026 policy financing guidance also describes the indirect lending process as application and registration with SEMAS → review by a guarantee institution or financial institution → loan disbursement by a financial institution.
Can a Bank Reject Your Application Even After You Receive the Certificate?
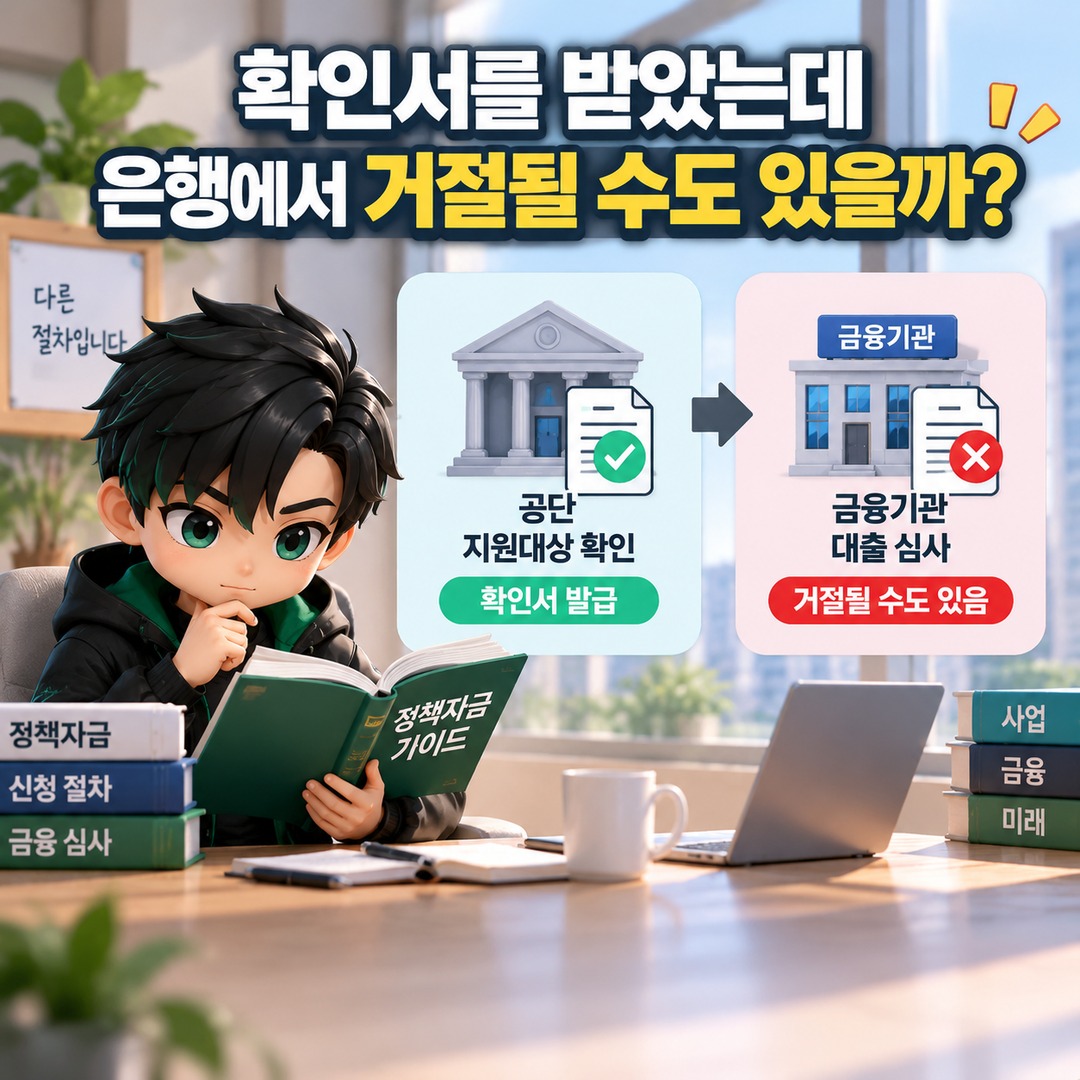
Yes, it can. This is because SEMAS confirming that an applicant qualifies for policy financing and a financial institution deciding that it can actually lend money are two separate procedures.
In particular, loans backed by a guarantee certificate require an additional guarantee review by an institution such as a regional credit guarantee foundation after SEMAS verifies eligibility. Even after the guarantee is approved, the applicant must complete the loan agreement and disbursement procedures with the financial institution.
Financial institutions' own policy financing guidance also distinguishes the steps as policy financing eligibility certificate application → regional credit guarantee foundation guarantee application → guarantee approval → loan agreement → disbursement.
Therefore, applicants should be cautious about committing to contract deposits or scheduling major expenditures simply because they have received an eligibility certificate. It is safer to base spending plans on the final amount actually disbursed.
Guarantee-Backed Loans Follow a Different Process From Credit-Based and Collateral-Backed Loans
Because the General Business Stabilization Fund operates through indirect lending, the intermediate steps may vary depending on how the applicant undergoes the bank's loan review.
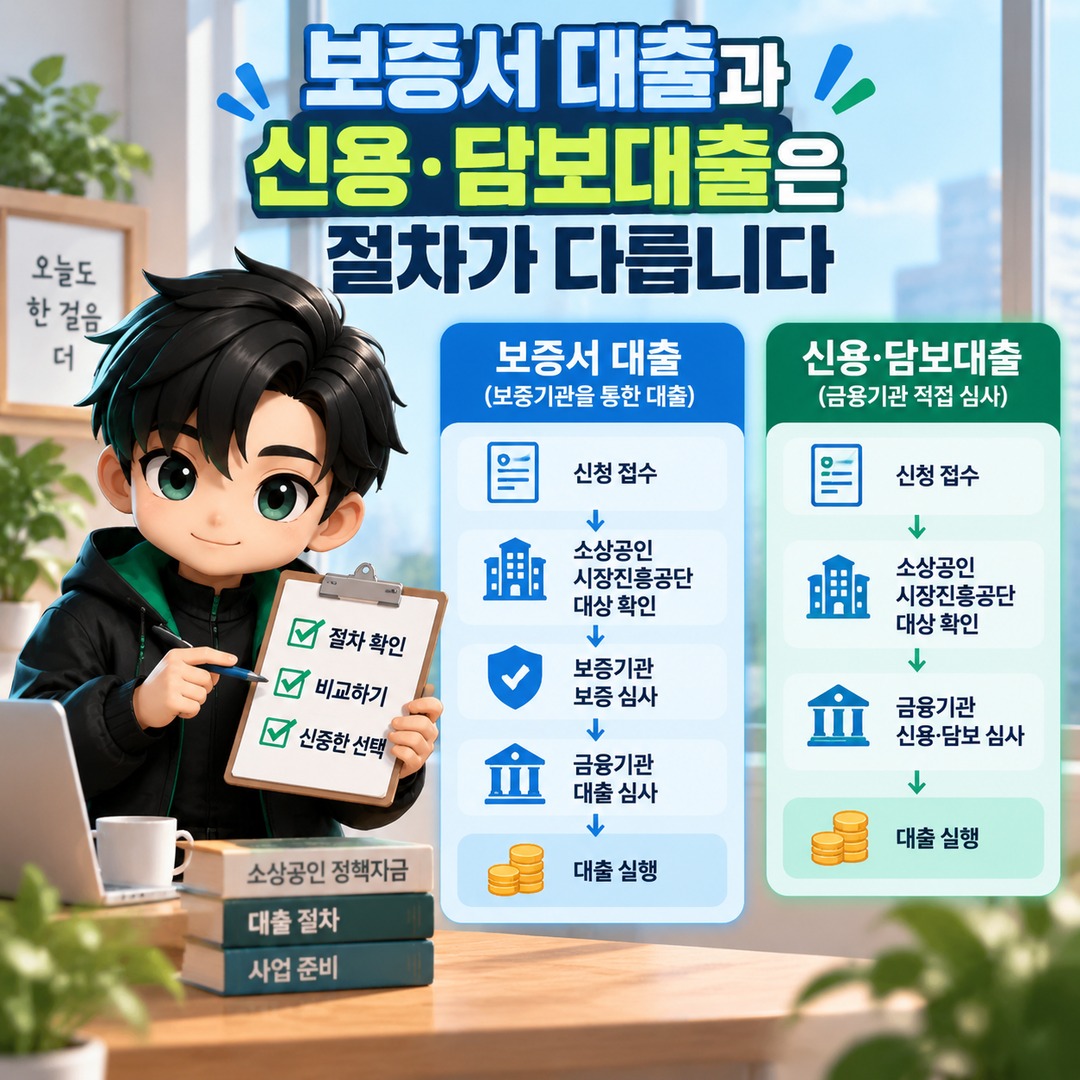
For guarantee-backed loans, SEMAS first confirms eligibility, a credit guarantee institution then reviews the guarantee application, and a financial institution subsequently disburses the loan.
By contrast, credit-based and collateral-backed loans do not require a separate guarantee certificate issuance process. Instead, the financial institution assesses the applicant's creditworthiness or collateral and decides whether to approve the loan.
In other words, even if another business owner says they went straight to the bank after receiving their certificate or visited a guarantee foundation first, their process may not necessarily be the same as yours.
Applicants should check the next steps based on the lending method specified after applying and the requirements of the participating financial institution.
A Maximum Limit of 7 Thousand Won Does Not Mean You Will Receive the Full 7 Thousand Won
The General Business Stabilization Fund's 2026 annual limit is 7 thousand won per business, but this is not a fixed grant paid equally to every applicant. The fund provides policy loans that must be repaid, and whether a loan is disbursed, as well as the amount, depends on subsequent reviews.
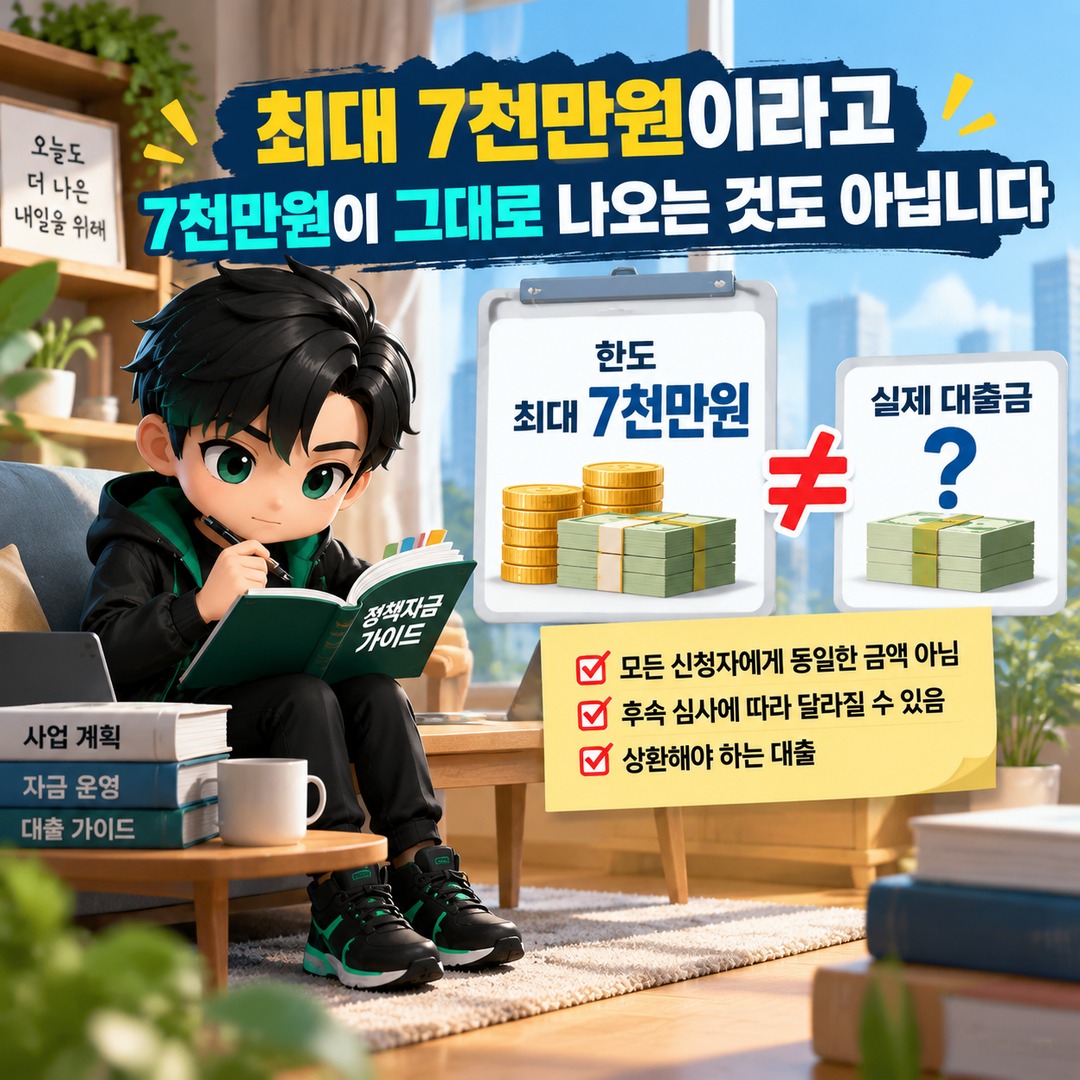
Three commonly confused amounts should be distinguished.
Requested loan amount is the amount the business owner states they need when submitting the application.
Policy loan limit is the maximum amount permitted under the relevant financing program.
Actual loan disbursement amount is the amount ultimately provided after the guarantee and financial institution procedures are completed.
Therefore, applicants should not assume that requesting 7 thousand won will automatically result in receiving 7 thousand won simply because that is the program's limit.
What Should You Prepare Before Applying in the 4 Quarter of 2026?
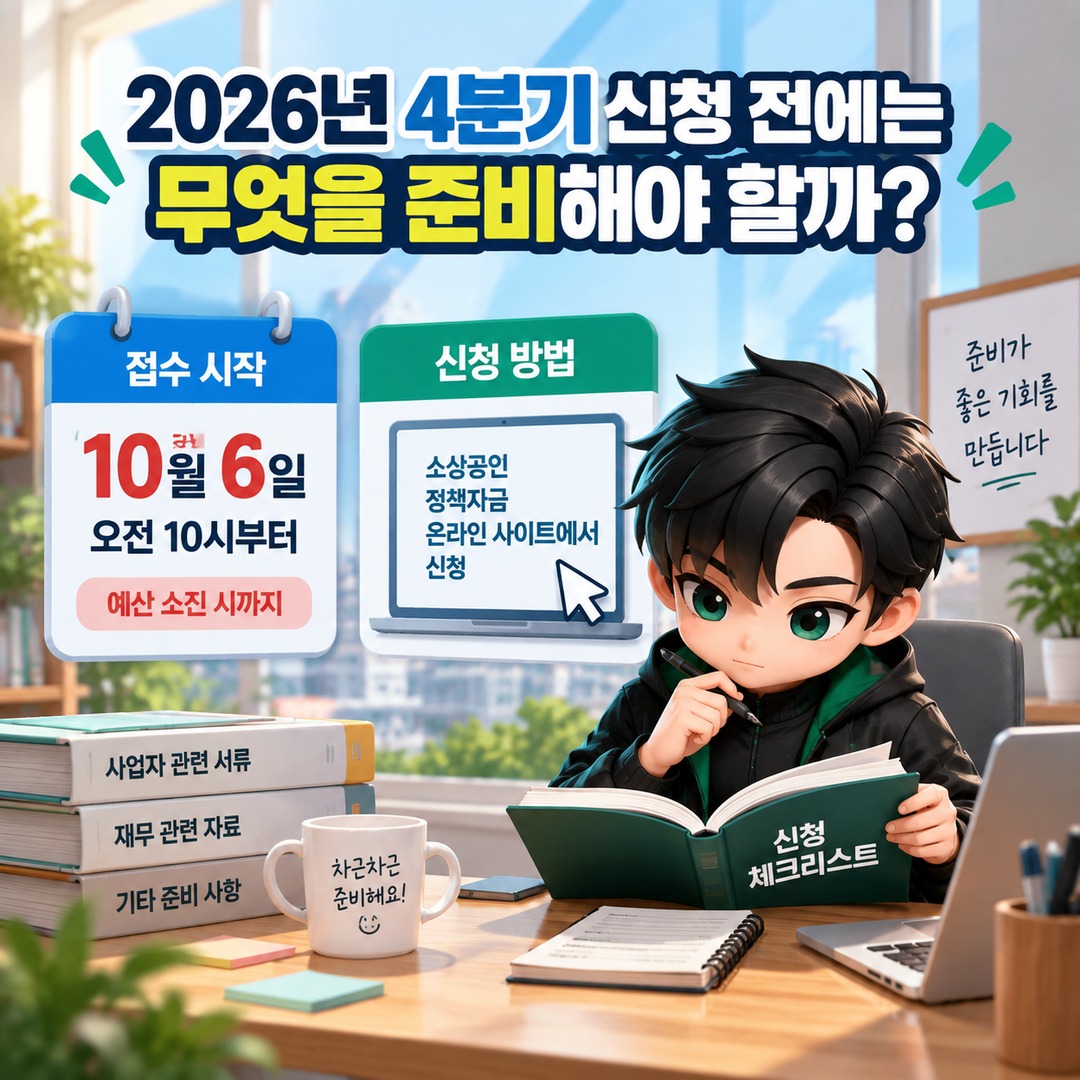
Applications for small business policy financing through indirect lending in the 4 quarter of 2026 are scheduled to open at 10 a.m. on October 6 and remain open until the budget is exhausted. Applicants are instructed to apply through the official Small Business Policy Financing online website.
Before applications open, it is advisable to prepare not only business registration information and documents establishing small business eligibility but also the materials needed for subsequent stages.
In particular, applicants should check in advance whether they will need to go through a guarantee institution after receiving their eligibility certificate, what documents their chosen financial institution requires, and how much they actually need to borrow after considering existing debts and repayment obligations.
The indirect lending instructions on the policy financing website also specify separate application procedures, including self-assessment, completing application forms, and submitting documents.
What Should You Do After Your Eligibility Certificate Is Issued?
The key is not to assume that the process ends when the certificate appears on the issuance screen, but to immediately confirm which additional procedures apply to your application.
If you are applying for a guarantee-backed loan, check the review procedures of the relevant guarantee institution. If you are using a credit-based or collateral-backed lending method, prepare for the participating financial institution's loan review. Required documents and assessment criteria may differ between guarantee institutions and financial institutions.
Additionally, as of 2026-09-29, before applications for the 4 quarter of 2026 begin, applicants should review the latest official announcement to confirm the detailed conditions that will apply when they actually submit their applications. This is because policy financing applicants need to verify not only application schedules but also quarterly conditions, including interest rates.
Whether an individual business owner will ultimately qualify for a loan and how much will be disbursed cannot be determined solely from SEMAS's eligibility confirmation. Applicants must check the review results from the relevant institutions and the financial institution actually handling the loan.
Frequently Asked Questions
Does Receiving an Eligibility Certificate Mean My 7 Thousand Won Loan Has Been Approved?
No. 7 thousand won is the annual maximum limit for the General Business Stabilization Fund, and an eligibility certificate does not guarantee loan disbursement. Any required guarantee and financial institution reviews must still be completed.
Can a Bank Refuse to Lend Even After I Receive an Eligibility Certificate?
Yes. Under the indirect lending system, eligibility verification by SEMAS and loan assessment by a financial institution are separate procedures. Guarantee-backed loans also require an additional review by a guarantee institution.
Is the General Business Stabilization Fund a Grant?
No. The General Business Stabilization Fund provides working capital to support small business operations through financing that must be repaid, meaning a policy loan rather than a grant.
When Can I Apply for the 4 Quarter of 2026?
According to the currently published guidance, applications open at 10 a.m. on Tuesday, 2026-10-06, and remain open until the budget is exhausted. Immediately before applying, it is advisable to check the Small Business Policy Financing announcement again for the current application status and detailed conditions.
Related Articles
Why Did Freechal Fail? User Exodus Was More Damaging Than the KRW 3,000 Monthly Subscription Fee
Former Freechal Founder Jeon Je-wan's Recent Life as a Pension House Cleaner: What Happened to Him?