

Overdraft Line Balance Is KRW 0, but Your Mortgage Limit Drops? How DSR Counts It and What to Do
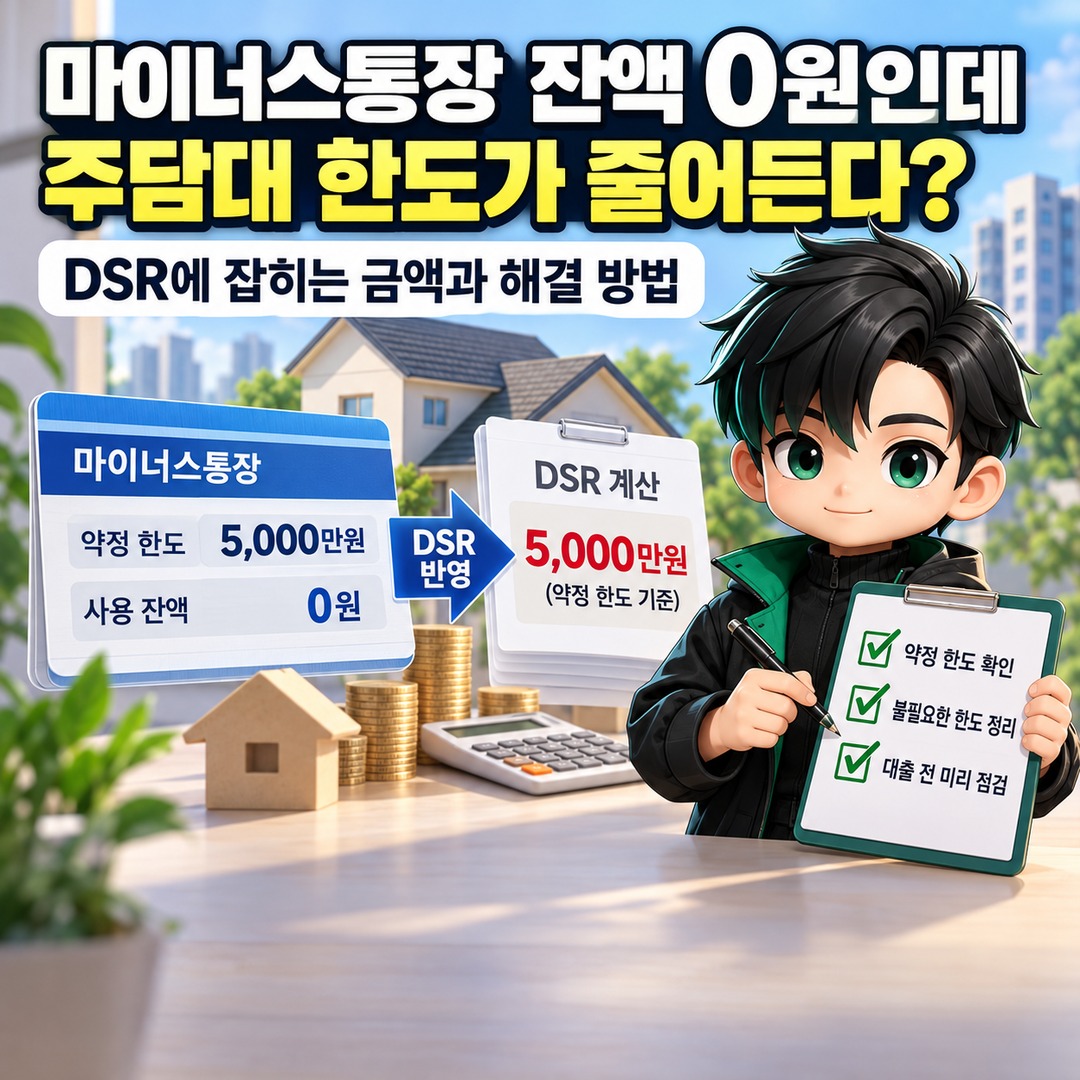
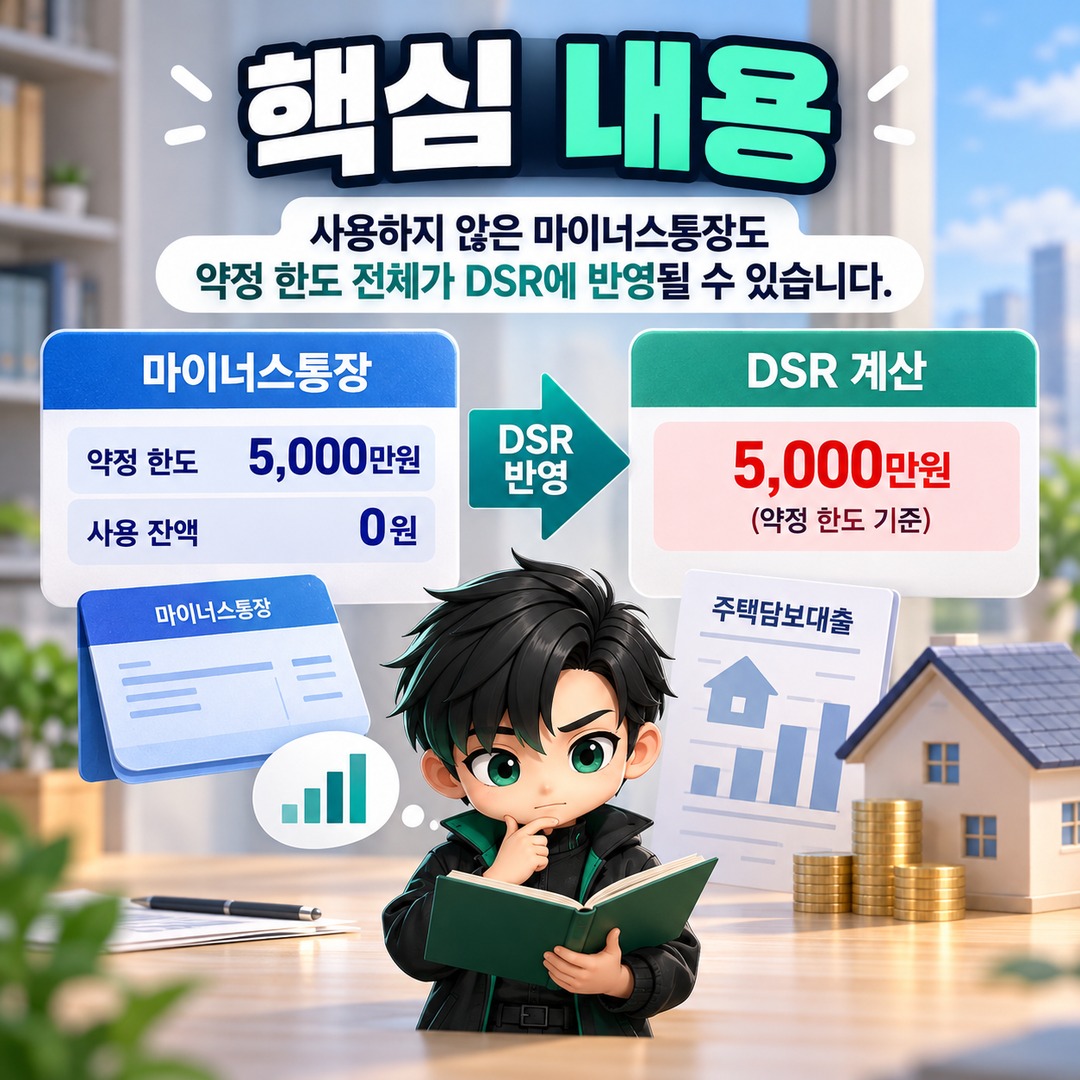
Even if you have never used your overdraft line of credit, the full contracted credit limit may be reflected in your mortgage assessment. For example, if your overdraft limit is KRW 50,000,000 and your outstanding balance is KRW 0, the repayment burden is calculated based on KRW 50,000,000 for DSR purposes.
Therefore, if you are preparing to apply for a mortgage, you should check not only your outstanding overdraft balance but also your contracted credit limit, whether the facility has been closed, and whether the changes have been reflected in the financial institution's systems.
*Information verified as of: 2026-10-17*
1. Why Is an Overdraft Line Counted as a Loan When the Balance Is KRW 0?
Unlike a conventional installment-repayment personal loan, an overdraft line is a revolving credit facility that allows you to borrow and repay money within an agreed limit.
Banks assess repayment capacity by considering not only the amount currently borrowed but also the amount that could be withdrawn in the future.
The Financial Services Commission's explanatory materials on borrower-level DSR explicitly state that the total loan amount for credit lines, including overdraft facilities, is calculated based on the contracted credit limit rather than the amount actually used.
Consider the following comparison of three borrowers.
| Contracted overdraft limit | Amount actually used | Amount counted as a loan |
|---|---|---|
| KRW 10,000,000 | KRW 0 | KRW 10,000,000 |
| KRW 30,000,000 | KRW 5,000,000 | KRW 30,000,000 |
| KRW 50,000,000 | KRW 0 | KRW 50,000,000 |
However, there is an important distinction to understand.
The Amount Included in Total Borrowing Is Different from the Annual Principal and Interest Repayments Counted Toward DSR.
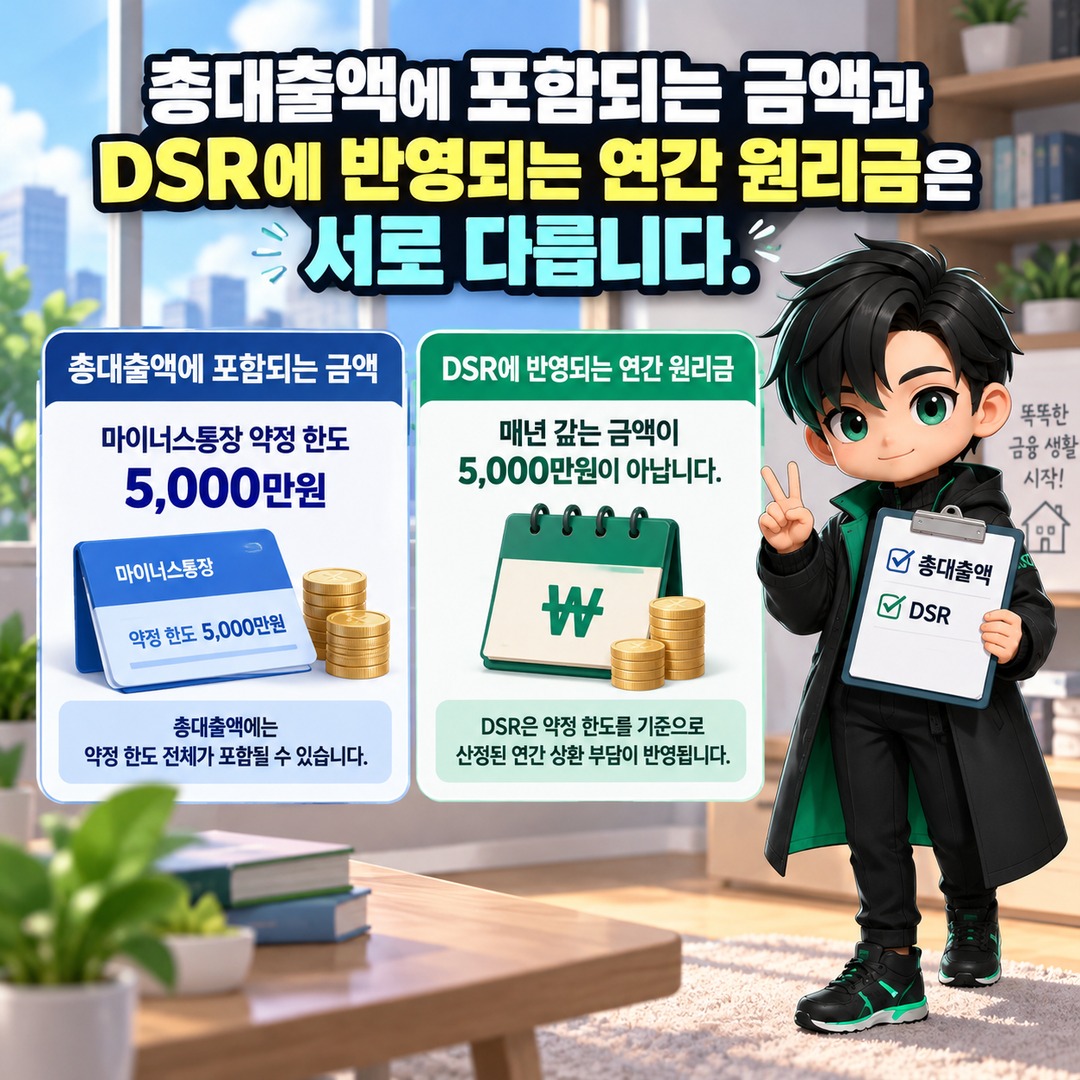
An overdraft limit of KRW 50,000,000 does not mean that the entire KRW 50,000,000 is treated as an amount that must be repaid every year.
For DSR calculations, the annual repayment amount is determined by applying factors such as the loan's assumed repayment term and interest burden.
Official reference: Financial Services Commission: Key Policy Questions and Answers on Borrower-Level DSR
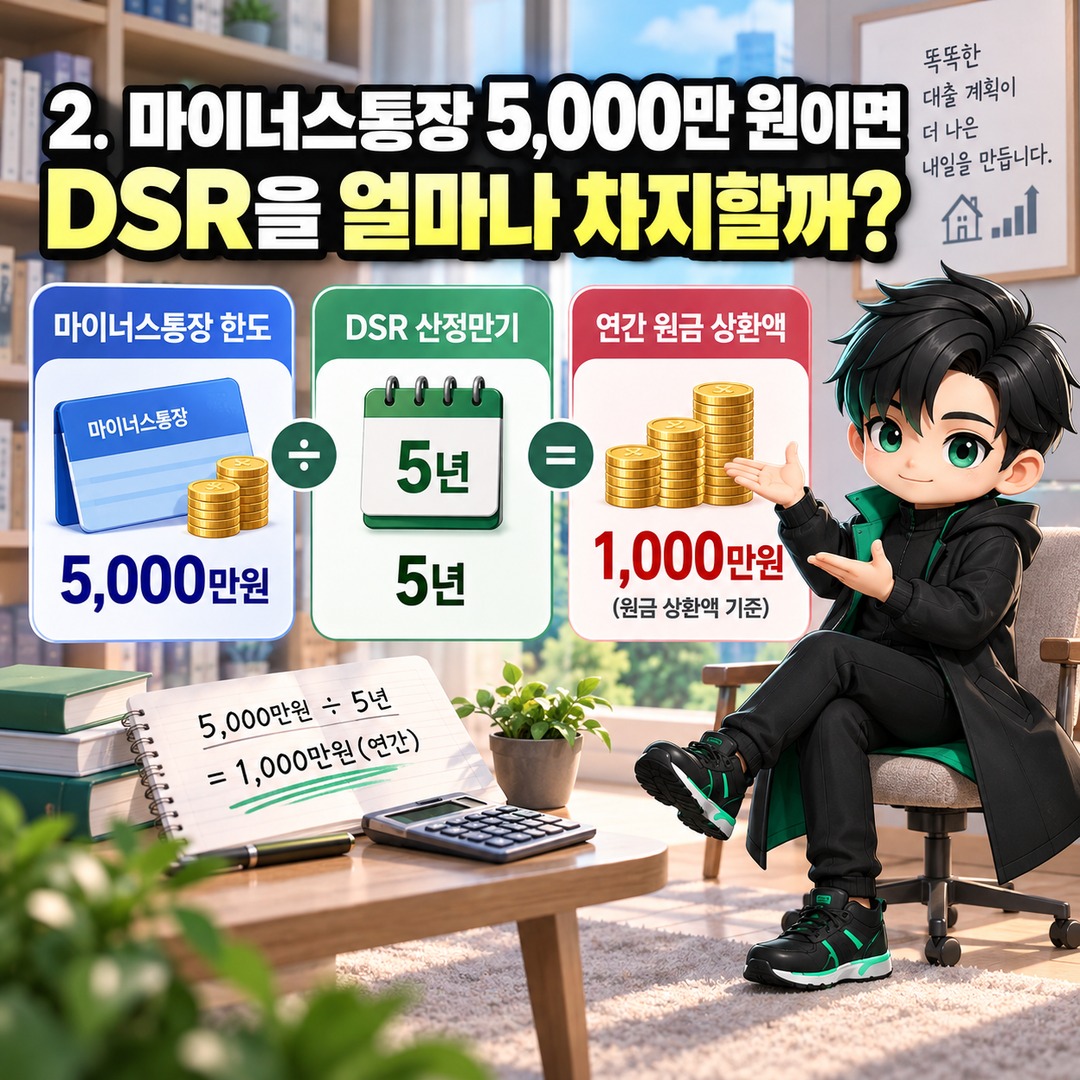
2. How Much DSR Does an Overdraft Limit of KRW 50,000,000 Use?
Suppose an overdraft facility has a limit of KRW 50,000,000 and an assumed DSR repayment term of 5 years. In this example, the annual principal repayment alone could be calculated as KRW 10,000,000.
The interest burden is then added.
The following assumptions are intended to illustrate the calculation method.
Overdraft credit limit: KRW 50,000,000
Actual outstanding balance: KRW 0
Assumed interest rate: 5% annually
Assumed DSR repayment term: 5 years
Recognized annual income: KRW 50,000,000
The annual principal amount is calculated as follows.
KRW 50,000,000 ÷ 5 years = KRW 10,000,000
Under a simplified assumption that the annual interest rate of 5% is applied to the entire credit limit, the annual interest amount is calculated as follows.
KRW 50,000,000 × 5% = KRW 2,500,000
Therefore, the calculated annual principal and interest repayment amount is KRW 12,500,000.
DSR is calculated as follows.
\\[
DSR=\frac{KRW 12,500,000}{KRW 50,000,000}\times100=25\\%
\\]
Author's calculation. Actual DSR calculations by financial institutions reflect product-specific interest calculation methods, applicable interest rates, assumed repayment terms, and supervisory regulations. Therefore, actual results may differ from the example above.
Assuming a banking-sector DSR limit of 40%, a borrower with annual income of KRW 50,000,000 would have an allowable annual principal and interest repayment amount of KRW 20,000,000.
However, if the existing overdraft facility is assessed as consuming KRW 12,500,000 annually, only KRW 7,500,000 per year would remain available for repayments on a new mortgage.
This Is Why an Outstanding Overdraft Balance of KRW 0 Does Not Automatically Eliminate Its Impact on Mortgage Assessment.
However, the 25% above is a hypothetical calculation, not a confirmed DSR figure or an actual approved borrowing limit applicable to every financial institution.
3. Will Reducing Your Overdraft Limit Increase Your Mortgage Limit?
If DSR is the factor restricting your mortgage borrowing capacity, reducing your overdraft credit limit may increase the amount you can borrow.
However, if you have already reached the loan-to-value ratio (LTV) limit or a region-specific mortgage cap, additional DSR capacity may not change your actual mortgage limit.
Let's apply the same simplified assumptions used earlier: an annual interest rate of 5% and an assumed repayment term of 5 years.
| Contracted credit limit | Calculated annual principal and interest repayments | DSR based on annual income of KRW 50,000,000 |
|---|---|---|
| KRW 50,000,000 | KRW 12,500,000 | 25% |
| KRW 30,000,000 | KRW 7,500,000 | 15% |
| KRW 10,000,000 | KRW 2,500,000 | 5% |
| KRW 0 (closed) | KRW 0 | 0% |
Author's calculation. This example assumes there are no other loans and considers only the overdraft facility.
Under these assumptions, reducing the overdraft limit from KRW 50,000,000 to KRW 10,000,000 lowers the DSR burden by 20% percentage points.
However, this does not mean your mortgage limit will increase by a fixed amount.
Your actual mortgage borrowing limit is determined by several factors together:
Recognized annual income and annual principal and interest repayments on existing loans
Mortgage interest rates and the application of stress DSR
Loan maturity and repayment structure
Property location and loan-to-value ratio (LTV)
Property-price-based lending caps and financial institution underwriting standards
In particular, stress DSR is a system that incorporates the possibility of rising interest rates into loan assessments. It does not mean that borrowers actually pay interest at a rate obtained by simply adding the stress rate to their contractual interest rate.
Therefore, the effect of reducing an overdraft limit should be evaluated separately in terms of how much additional DSR capacity becomes available and how much the actual mortgage limit changes.
4. What Is the Difference Between Reducing Your Overdraft Balance to KRW 0 and Closing the Facility?
Reducing your overdraft balance to KRW 0 means repaying all the money you have borrowed.
Closing an overdraft facility, on the other hand, means terminating the contracted credit limit itself.
These actions can produce different outcomes in a DSR assessment.
| Action | Outstanding balance | Contracted credit limit |
|---|---|---|
| Repay the entire outstanding balance | KRW 0 | Remains in place |
| Reduce the credit limit | Depends on the circumstances | Decreases |
| Complete closure of the credit agreement | KRW 0 | KRW 0 |
For example, suppose you have used KRW 10,000,000 of an overdraft limit of KRW 50,000,000. Even if you repay the entire outstanding amount, the facility may continue to be reflected in your DSR as a credit line if the contracted limit of KRW 50,000,000 remains active.
By contrast, once the credit agreement has been closed and the closure is reflected in the financial institution's assessment, the repayment burden associated with that credit line can be excluded.
However, closing an overdraft facility also eliminates the credit available to you in an emergency.
There is no guarantee that you will be able to reopen the facility later with the same credit limit. If your income, credit profile, or the financial institution's lending policies have changed, you may receive a lower limit or have your application rejected.
Therefore, rather than immediately closing an existing overdraft facility simply because it may negatively affect your mortgage assessment, it is better to compare your emergency funding needs with the expected improvement in borrowing capacity.
5. When Should You Reduce or Close Your Overdraft Facility Before Applying for a Mortgage?
When reducing or closing an overdraft facility, the important point is to complete the change before it needs to be reflected in the mortgage assessment.
However, it cannot be assumed that every bank applies the same mandatory waiting period after closure.
This is because financial institutions may have different assessment procedures and loan-information update schedules.
During the actual application process, it is advisable to follow these steps.
1. Check your current credit limit: Confirm your overdraft facility's outstanding balance and contracted credit limit separately.
2. Request a preliminary mortgage consultation: Ask the lender to compare your estimated DSR with the current credit limit maintained versus a reduced limit.
3. Apply for a limit reduction or closure: If an adjustment is necessary, confirm the procedure with the financial institution that provided the existing credit facility.
4. Confirm completion: Verify that the contractual change or closure has actually been completed, rather than merely submitted for processing.
5. Confirm that the change is reflected in the mortgage assessment: Ask the financial institution handling your new mortgage whether the updated loan information has been incorporated into its assessment.
In particular, if the final payment date for an apartment purchase has already been set, avoid planning your schedule based solely on the date you submitted the closure request.
It is important to confirm that the new lender has actually reflected the change.
6. What If Your Mortgage Limit Remains Unchanged After Closing Your Overdraft Facility?
Closing an overdraft facility does not necessarily increase your mortgage borrowing limit.
There are three common explanations worth checking.
When LTV, Rather Than DSR, Is Restricting Your Borrowing Limit
DSR evaluates repayment capacity relative to income, while LTV restricts borrowing based on the collateral value of the property.
If you have already reached the LTV limit, reducing an existing credit line may not allow you to borrow more.
When the Closure Has Not Yet Been Reflected in the Assessment
Even after an existing credit facility has been closed, its previous limit may still appear in the new lender's credit inquiry results or assessment records.
In this case, confirm that the original lender has completed the closure and ask the new lender whether reassessment is possible.
When Other Loans Are Still Outstanding
Other debts, such as automobile installment financing, card loans, and existing personal loans, may affect your repayment-capacity assessment.
However, not all installment transactions are included in DSR in the same way, so you should verify whether each product is included.
Closing one overdraft facility does not eliminate your entire debt burden.
7. Frequently Asked Questions
Q. Is an Overdraft Facility Included in DSR Even If I Have Never Used It?
Yes. As a general rule, credit lines are assessed based on their contracted limits rather than the amounts actually used. Even if your outstanding balance is KRW 0, an active contracted credit limit may affect your mortgage assessment.
Q. Can I Simply Reduce My Overdraft Credit Limit?
Yes. However, the remaining credit limit after the reduction may still be reflected in DSR. To determine whether reducing the limit or closing the facility entirely is more advantageous, compare your emergency funding needs with your estimated mortgage borrowing capacity.
Q. Will Closing My Overdraft Facility Improve My Credit Score?
Not necessarily. Credit scores depend on various factors, including repayment history, the duration of credit relationships, and current borrowing activity. Closing a credit facility alone does not guarantee a higher score.
Q. Can I Open Another Overdraft Facility After My Mortgage Has Been Approved?
It may be possible if you pass the assessment for a new personal loan, but your existing mortgage and other debts will be considered in the new loan assessment. Additional borrowing before or after mortgage disbursement may also affect approval conditions or agreements with your financial institution, so you should check first.
8. Conclusion: Check Your Contracted Credit Limit, Not Just Your Balance, Before Applying for a Mortgage
Even if you have not used your overdraft facility, an active contracted credit limit may work against you during a mortgage assessment.
In particular, borrowers with limited DSR capacity need to understand the difference between reducing an outstanding balance to KRW 0 and reducing or closing the contracted credit limit.
However, closing the facility is not always the best answer.
Even after eliminating an overdraft facility, your mortgage limit may remain unchanged because of LTV restrictions or regional lending caps. You also risk being unable to restore your previous credit limit after closure.
Before Applying for a Mortgage, the Most Practical Approach Is to Ask Your Financial Institution to Compare the Estimated Approved Loan Amounts Under Two Scenarios: Keeping Your Current Overdraft Limit and Reducing or Closing It.
※ This article is provided for reference to help readers understand market conditions and does not constitute an investment recommendation concerning any particular security or asset. Final decisions and responsibility for investments rest with the individual.