

Why National Pension Contributions Appear to Have Increased Twice in 2026: The January Contribution Rate and July Standard Monthly Income Are Different
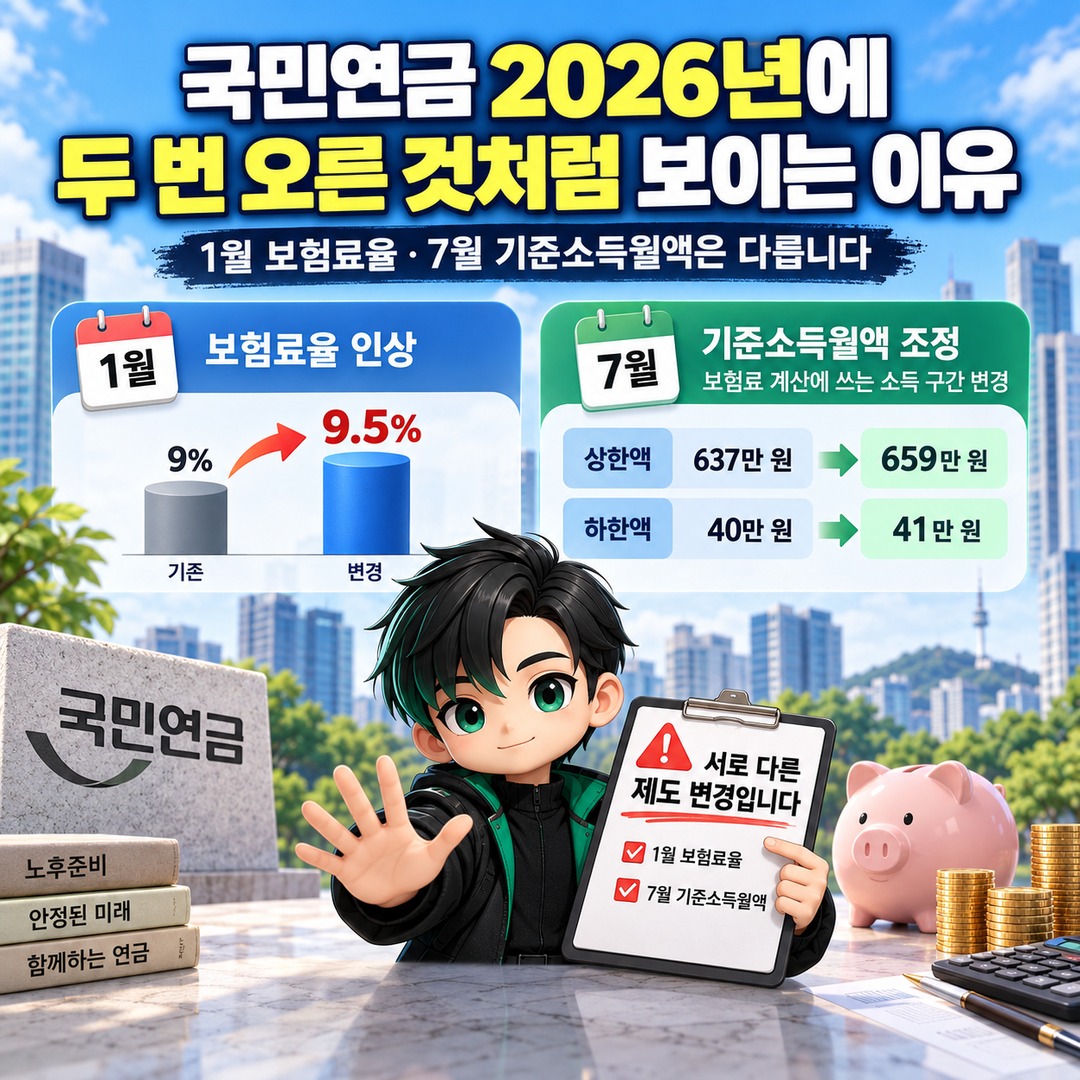
If your National Pension contributions increased in January and changed again in July of 2026, it does not necessarily mean there was a calculation error. The contribution rate rose from 9% to 9.5% in January, while the standard monthly income used to calculate contributions and its upper and lower limits were newly applied in July.
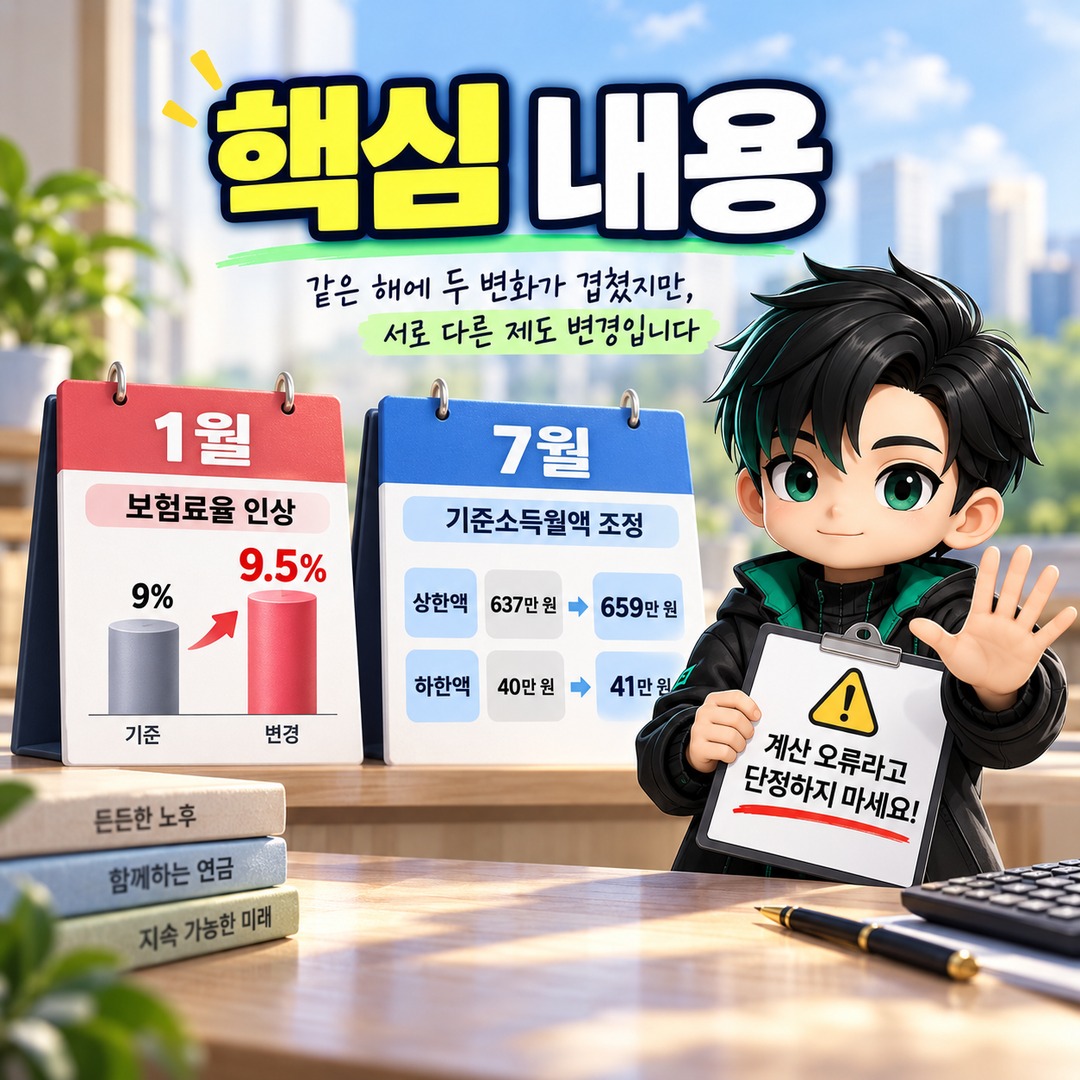
Although both changes occurred in the same year, they were separate policy changes. In particular, if your salary remained unchanged but your July payroll deduction changed, you should first check whether your standard monthly income changed, rather than assuming the contribution rate increased again.
The Changes in January and July Were Different
Starting 2026-01-01, the National Pension contribution rate increased from 9% to 9.5%. Because employees and employers each pay half of the contribution for workplace-based insured members, the employee contribution rate increased from 4.5% to 4.75%.
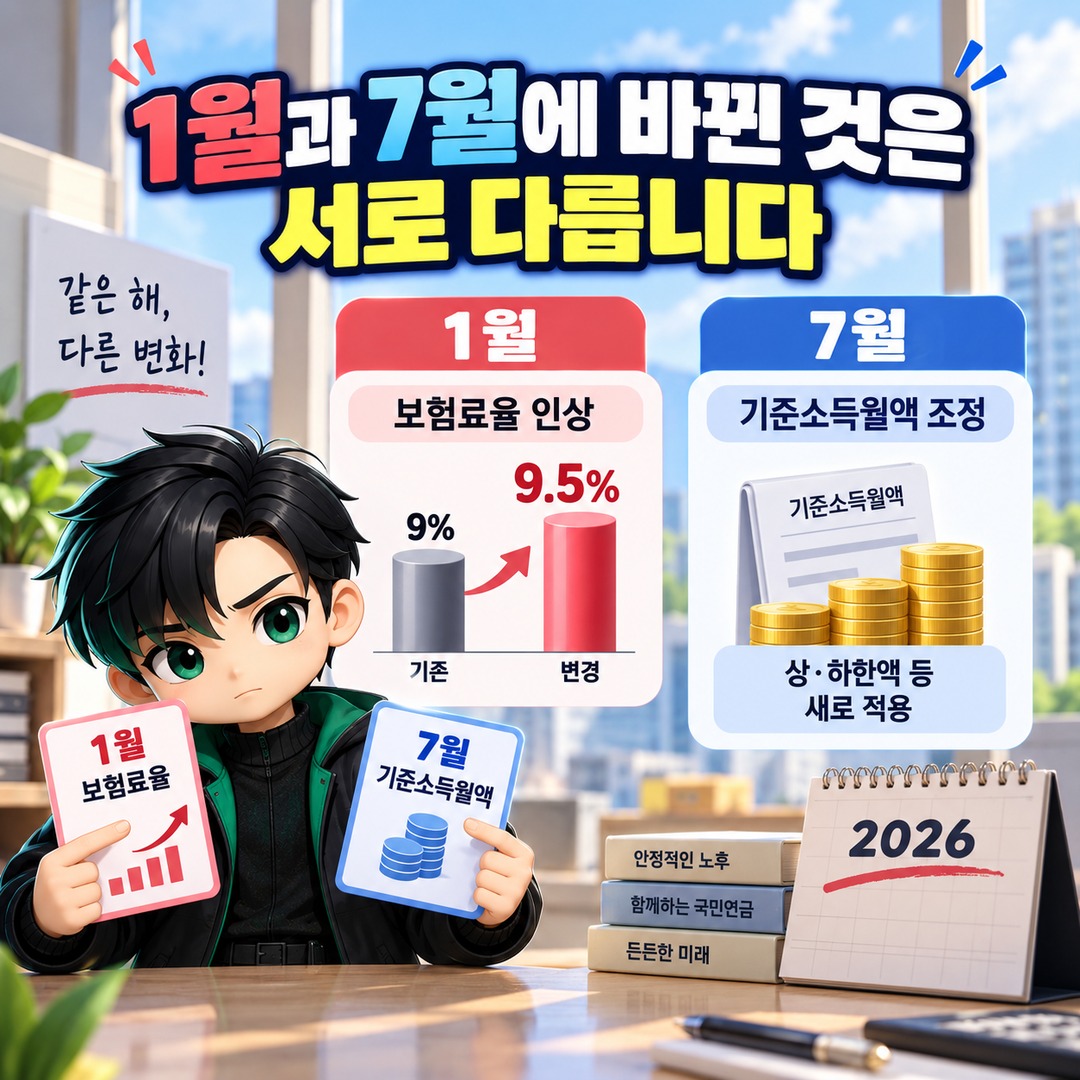
By contrast, the contribution rate did not increase again in 2026-07-01. It remained at 9.5%, while the regular determination of standard monthly income and adjustments to its upper and lower limits took effect.
| Category | January 2026 | July 2026 |
|---|---|---|
| Main change | Contribution rate | Standard monthly income and upper/lower limits |
| Total contribution rate | 9% → 9.5% | Remains at 9.5% |
| Employee contribution rate | 4.5% → 4.75% | Remains at 4.75% |
| Upper limit of standard monthly income | KRW 6,370,000 | KRW 6,590,000 |
| Lower limit of standard monthly income | KRW 400,000 | KRW 410,000 |
Therefore, in 2026, the two factors—'the January contribution rate increase' and 'the July change in the income calculation basis'—must be considered separately.
A Monthly Salary of KRW 3,000,000 Does Not Automatically Mean Another Increase in July
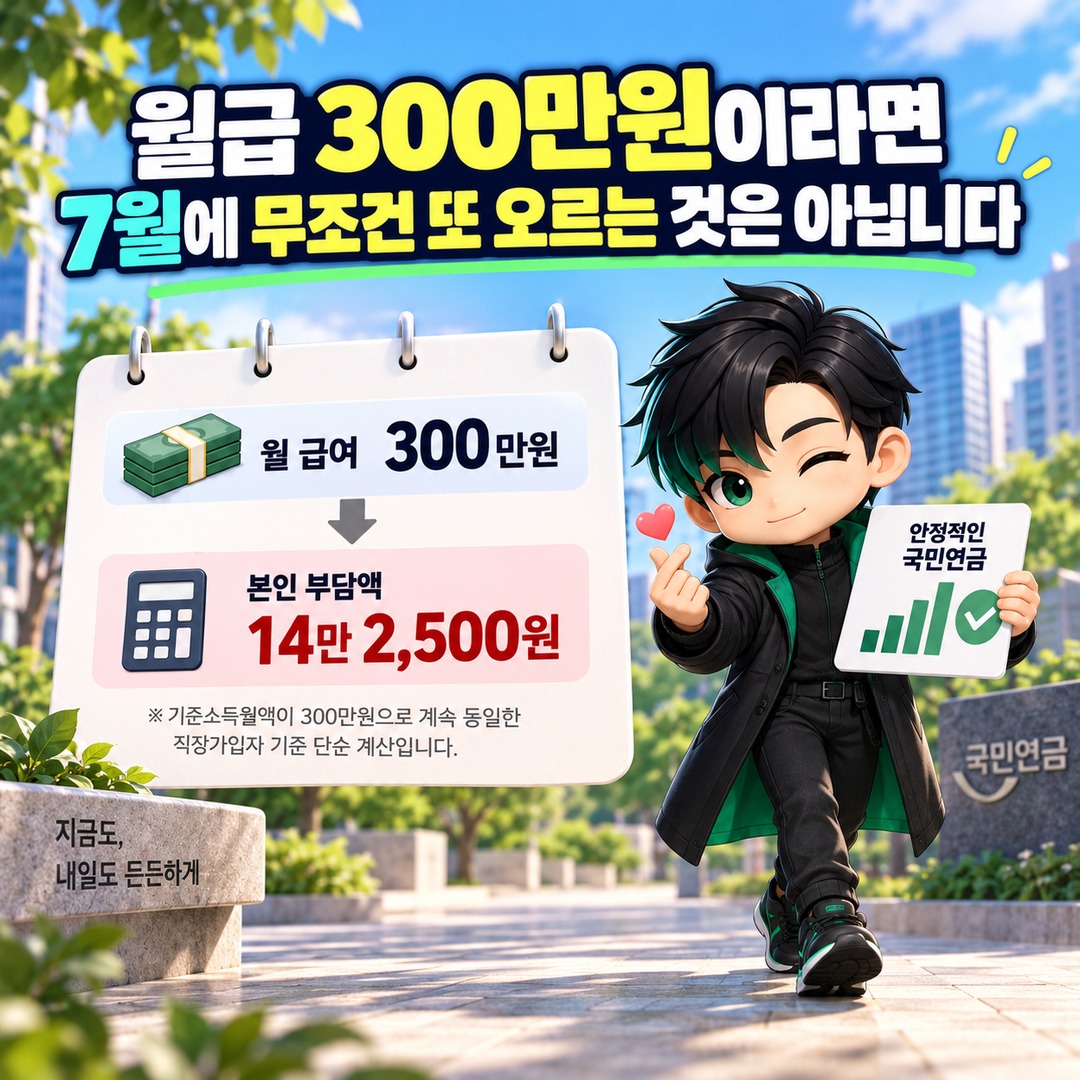
For a workplace-based insured member whose standard monthly income remains unchanged at KRW 3,000,000, a simple calculation puts the employee's monthly contribution in 2026 at KRW 142,500.
The calculation is as follows.
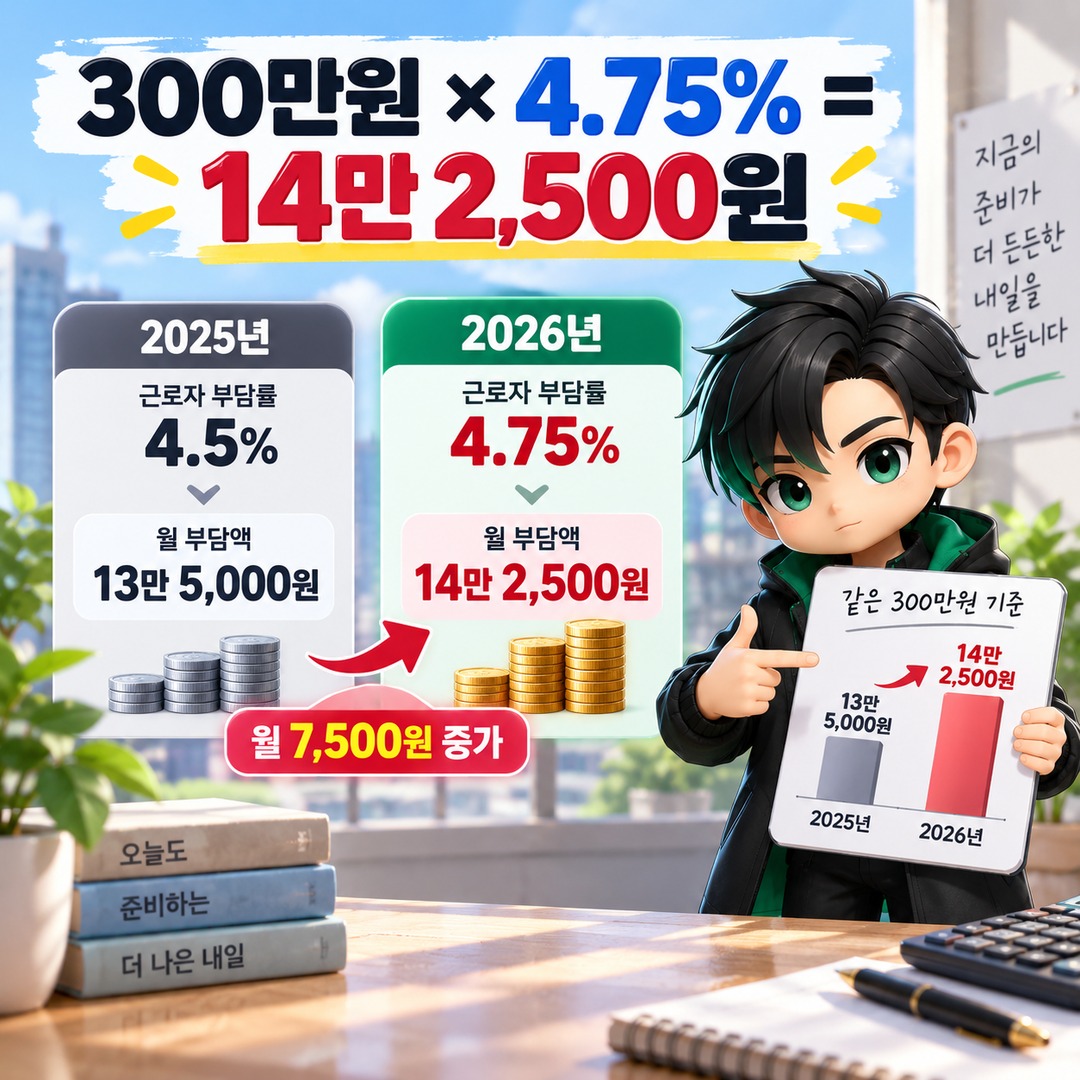
KRW 3,000,000 × 4.75% = KRW 142,500
Applying the 2025 employee contribution rate of 4.5% gives KRW 135,000. Therefore, using the same KRW 3,000,000 as the calculation basis, the contribution rate increase in 2026 raises the monthly contribution by KRW 7,500. South Korea's Ministry of Health and Welfare also explained the increase in employees' contributions resulting from the 2026 rate adjustment, using a workplace-based insured member earning an average income as an example.
However, if the standard monthly income remains KRW 3,000,000 in July, the contribution does not increase again simply because the upper limit rose from KRW 6,370,000 to KRW 6,590,000.
If your contribution changed after July, you should also check whether the standard monthly income determined by the National Pension Service itself changed. The National Pension Service regularly determines the standard monthly income of workplace-based insured members and applies it from July of the relevant year through June of the following year.
Higher-Income Employees May Be Affected by the July Increase in the Upper Limit
Starting July 2026, the upper limit of standard monthly income increased from KRW 6,370,000 to KRW 6,590,000. The new upper limit applies from 2026-07-01 through 2027-06-30.
For example, consider a simple comparison involving an employee whose reported income has consistently been at or above the upper limit.
During 1–June of 2026, contributions are calculated using a maximum standard monthly income of KRW 6,370,000.
KRW 6,370,000 × 4.75% = KRW 302,575
After July 2026, contributions are calculated using a maximum standard monthly income of KRW 6,590,000.
KRW 6,590,000 × 4.75% = KRW 313,025
According to the author's calculation, the difference is KRW 10,450 per month.
In this example, the employee's contribution increased not because the contribution rate rose in July, but because the maximum income subject to contributions increased by KRW 220,000. For the total contribution, the calculated monthly amount at the upper limit is KRW 626,050, based on KRW 6,590,000 × 9.5%.
What Should You Check If Your Salary Stayed the Same but Your July Deduction Changed?
Comparing only the gross monthly salary shown on your payslips may not reveal the reason. National Pension contributions are calculated based on standard monthly income × contribution rate, rather than necessarily using your actual monthly salary directly.
The steps to check are straightforward.
1. Compare the National Pension deductions on your June and July payslips.
2. Ask your company's payroll administrator to confirm the standard monthly income applied from July.
3. If the standard monthly income changed, check whether the adjustment resulted from the regular determination process.
4. If your standard monthly income is KRW 6,590,000 or higher, also check whether the new upper limit was applied.
5. If the National Pension Service's determination appears inconsistent with your company's records, verify your contribution history and standard monthly income with the National Pension Service.
The National Pension Service states that the standard monthly income determined through the 2026 regular determination process generally applies from July 2026 through June 2027.
The Contribution Rate Will Increase Again in January 2027
There is a reason not to focus only on the changes in 2026. Under the amendment to South Korea's National Pension Act in 2025, the contribution rate will rise gradually by 0.5% percentage points each year, starting at 9.5% in 2026 and reaching 13% in 2033.
In 2027, the total contribution rate will be 10%, with employees and employers each paying 5% for workplace-based insured members.
For example, assuming the standard monthly income remains unchanged at KRW 3,000,000, the employee's contribution will change as follows.
2025: KRW 3,000,000 × 4.5% = KRW 135,000
2026: KRW 3,000,000 × 4.75% = KRW 142,500
2027: KRW 3,000,000 × 5% = KRW 150,000
In other words, even if standard monthly income does not change at all, an employee's contribution can increase gradually due solely to increases in the contribution rate.
Separately, the upper and lower limits of standard monthly income may also be adjusted each year in July. Therefore, when checking National Pension deductions in the future, the most accurate approach is to treat the January contribution rate and the July standard monthly income as two separate factors.
How to Identify Why Your National Pension Contribution Increased
If your payroll deduction increased starting January 2026, first check the contribution rate increase from 9% to 9.5%.
If the amount changed again in July 2026, check whether the regular determination of standard monthly income or changes to its upper and lower limits affected your contribution, rather than assuming the contribution rate increased again.
In particular, even when your salary appears unchanged, the standard monthly income used for National Pension calculations may not always match your actual salary. Instead of relying solely on the deduction shown on your payslip, you should also verify the standard monthly income registered with the National Pension Service to accurately identify the reason for the difference.