

Sole Proprietors' VAT Preliminary Notice: If the Amount Is Below KRW 500,000, Is Payment Required in October? Preliminary Notice vs. Preliminary Return
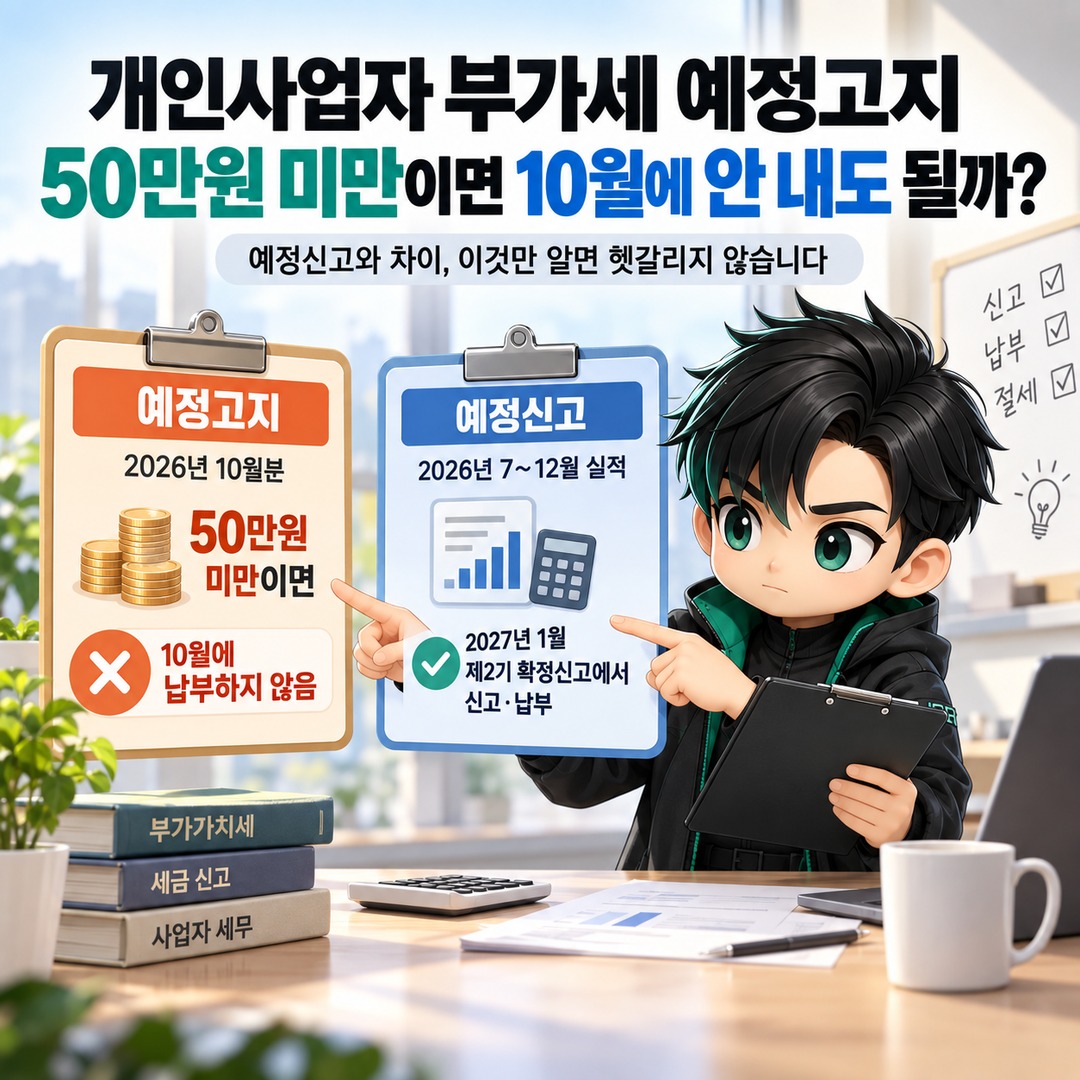
If the October 2026 VAT preliminary notice amount for an individual business owner subject to general taxation is below KRW 500,000, the business owner is excluded from the preliminary notice requirement and does not have to pay that preliminary notice amount in October. However, this does not mean the tax itself is eliminated. Business results for 7–December of 2026 will be reported and settled in the final VAT return for the 2 tax period, filed in January 2027.
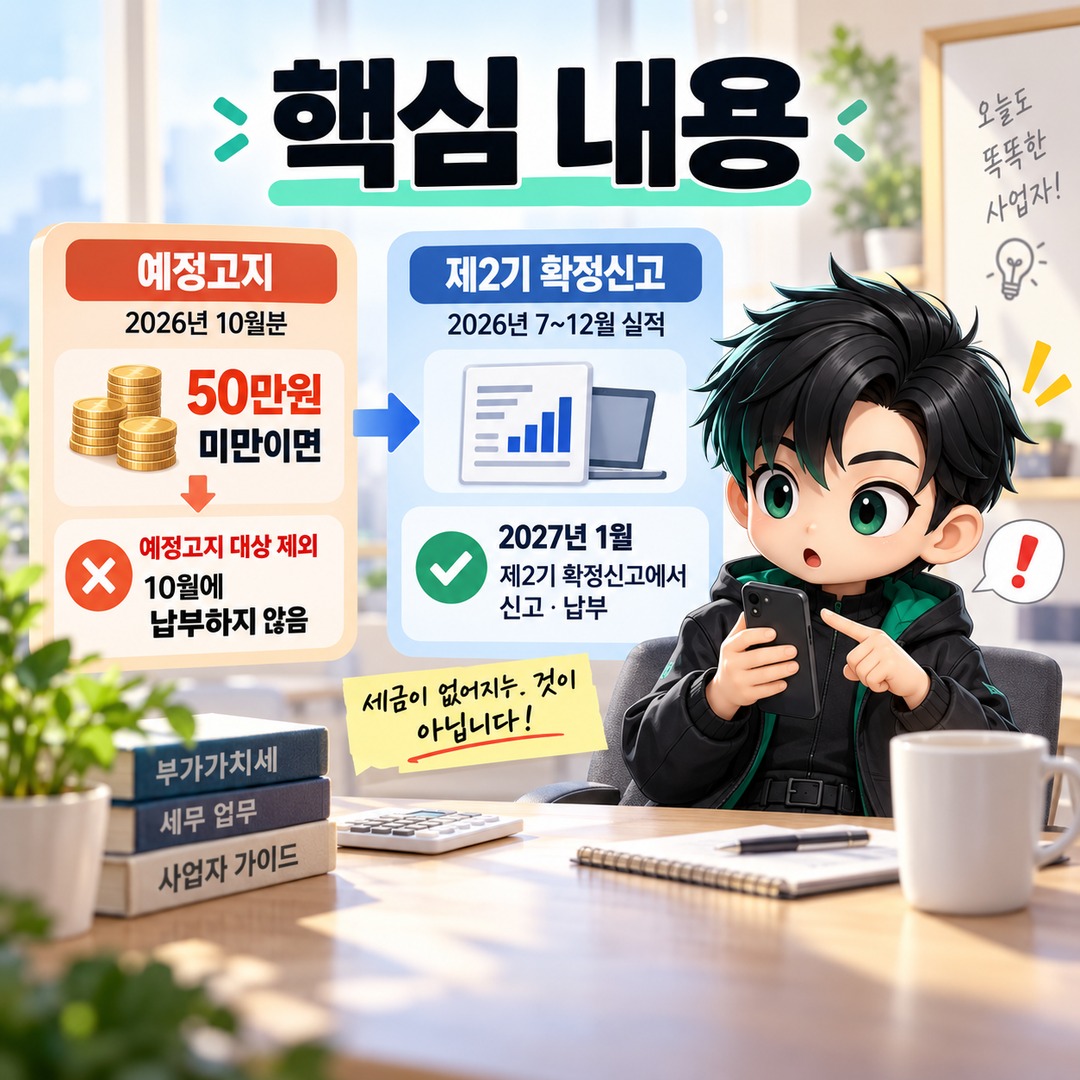
One of the most common sources of confusion is the distinction between these two systems. Exemption from a preliminary notice because the amount is below KRW 500,000 and filing a preliminary return due to poor business performance or other qualifying circumstances are two different procedures.
What Amount Is Compared Against the KRW 500,000 Threshold?
The KRW 500,000 threshold does not refer to sales revenue or the actual VAT for 7–September. Instead, the determination is based on the amount the tax office would otherwise collect through a preliminary notice.
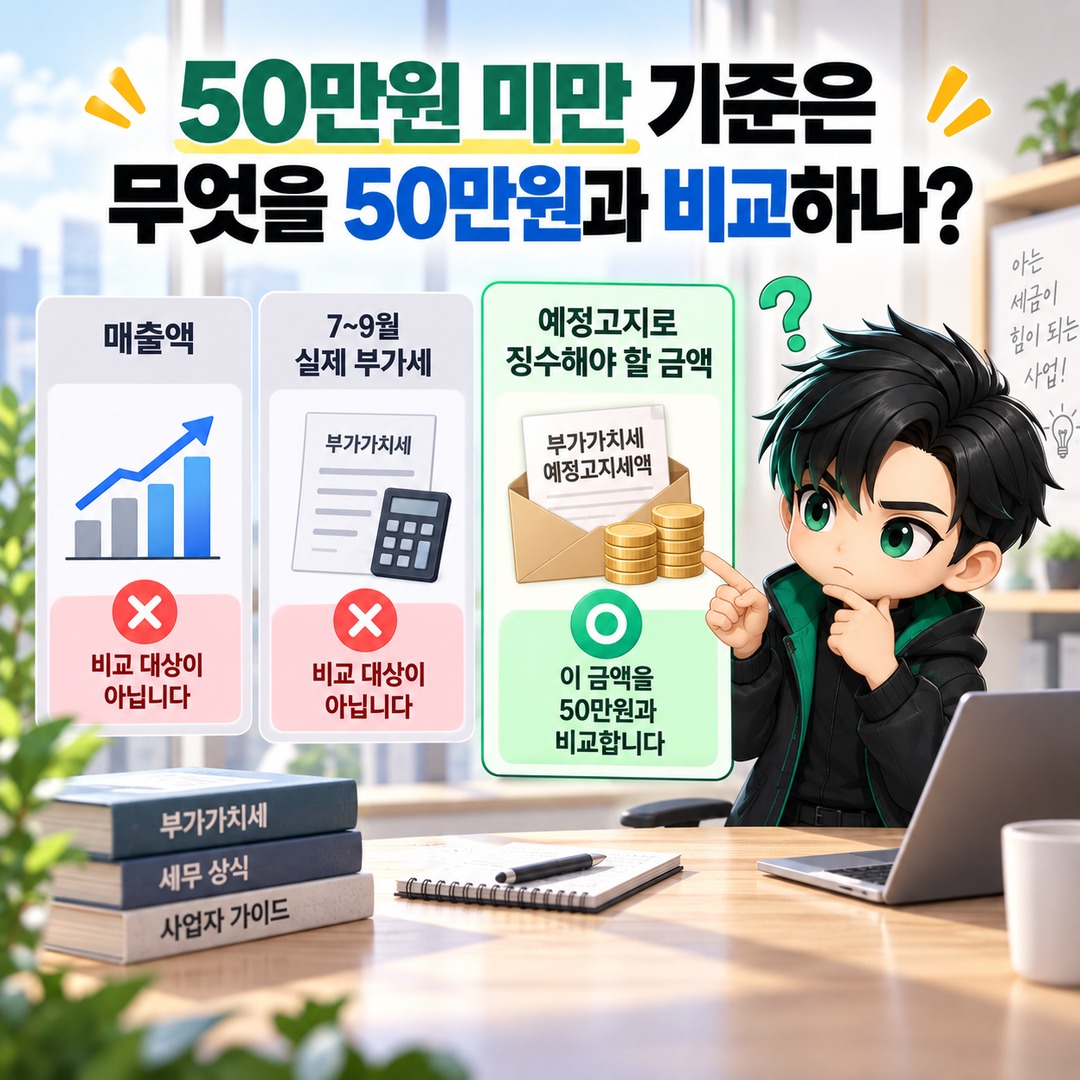
As a general rule, the preliminary notice amount for an individual business owner subject to general taxation is calculated based on 50% of the VAT paid for the immediately preceding tax period. Amounts smaller than KRW 1,000 are rounded down.
For example, assuming the VAT paid for the preceding tax period was KRW 900,000 and there are no other adjustments, 50% would be KRW 450,000. Because KRW 450,000 is below KRW 500,000, it qualifies for exclusion from the preliminary notice requirement.
Conversely, if the preliminary notice amount calculated using the same method is exactly KRW 500,000, it does not qualify for this exclusion because it is not 'below KRW 500,000.'
Therefore, rather than saying, 'If VAT is below KRW 500,000, you do not have to pay it in October,' it is more accurate to understand the rule as follows: 'If the preliminary notice amount to be collected is below KRW 500,000, no preliminary notice is issued.'
Not Receiving a Preliminary Notice Does Not Mean KRW 500,000 in Tax Has Been Waived
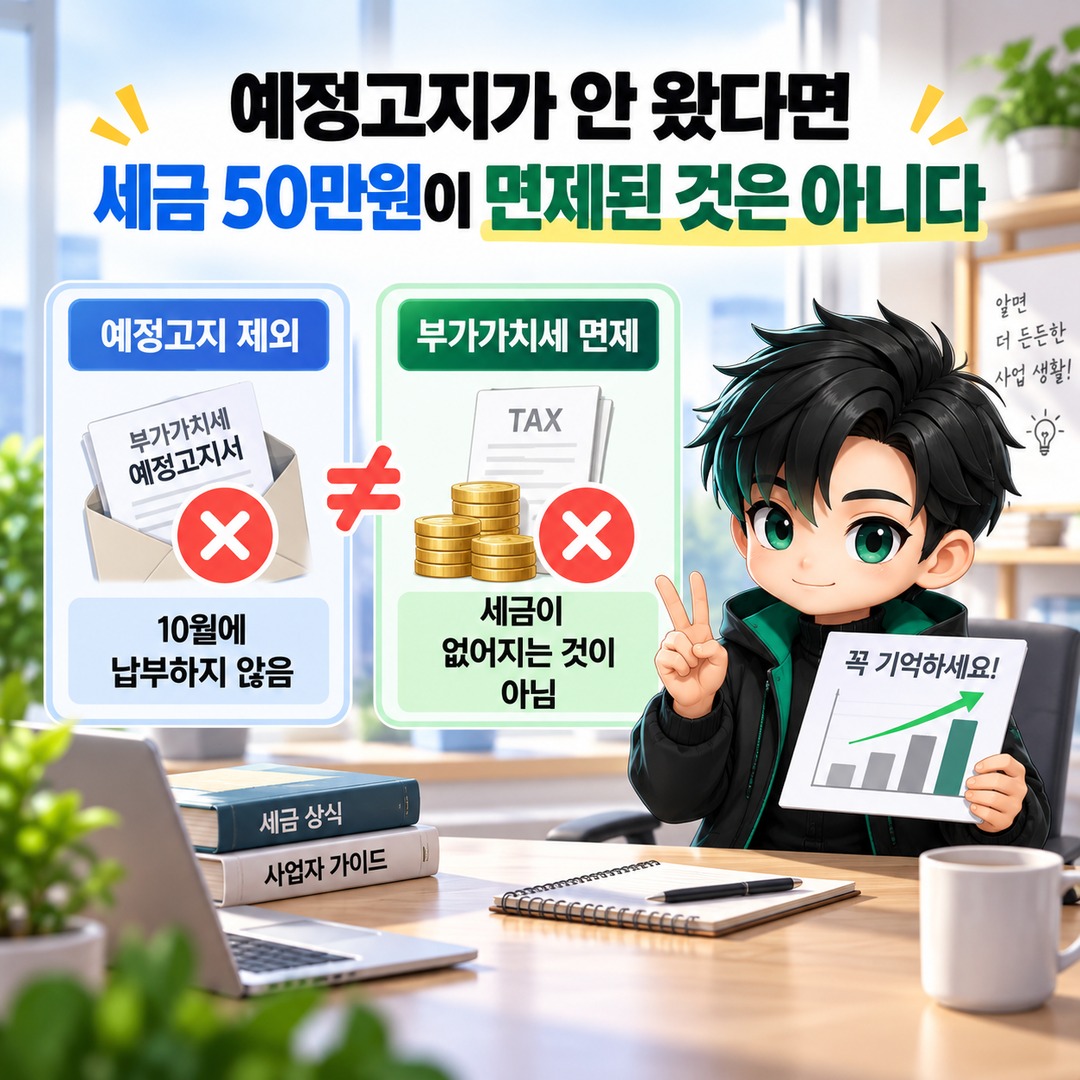
Exclusion from the preliminary notice requirement is different from a VAT exemption.
Individual business owners subject to general taxation generally settle their business results for the entire 2 tax period, from July 1 through December 31, through the final VAT return filed in January of the following year. The preliminary notice in October is a mechanism for paying a specified amount in advance during that period, based on the VAT paid for the preceding tax period.
Therefore, if a preliminary notice is not issued in October because the amount falls below KRW 500,000, this does not mean the amount that was not paid in October is permanently waived.
The VAT calculated from actual sales, purchases, and other relevant transactions during 7–December will be reflected in the subsequent final return.
In other words,
Exclusion From the October Preliminary Notice = No Interim Tax Notice This Time
It does not mean:
Exclusion From the October Preliminary Notice = VAT Itself Is Eliminated
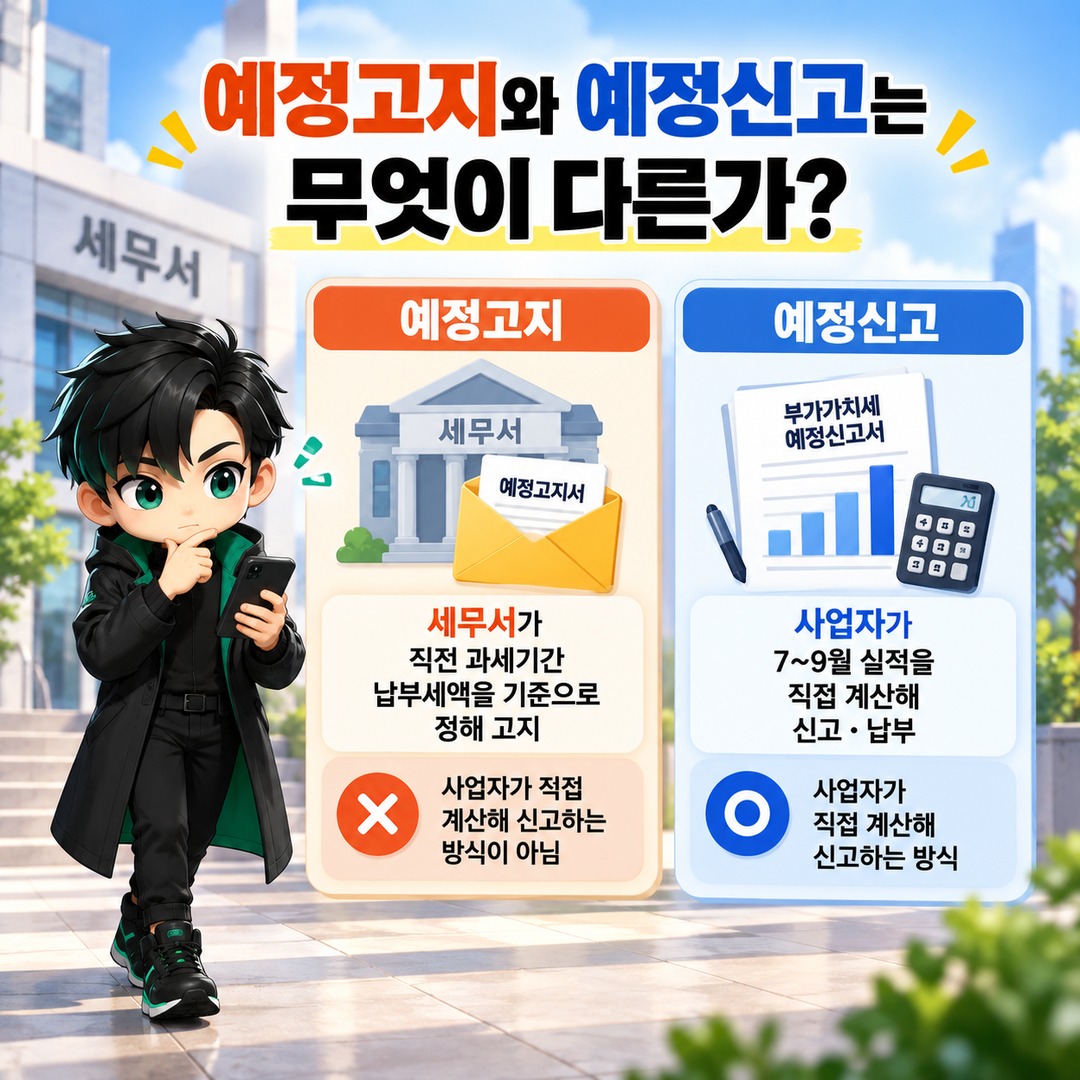
What Is the Difference Between a Preliminary Notice and a Preliminary Return?
A preliminary notice does not require the business owner to calculate and report actual business results for 7–September. In principle, the tax office determines the preliminary notice amount for individual business owners subject to general taxation based on the VAT paid for the preceding tax period and issues a payment notice.
A preliminary return works differently. The business owner files a return based on actual business results during the preliminary reporting period, from July 1 through September 30.
Individual business owners subject to general taxation generally have no obligation to file a preliminary return in October. However, if certain conditions are met, they may file a preliminary return instead of paying the amount stated in the preliminary notice.
The statutory reference date for filing and paying the preliminary VAT return for the 2 tax period of 2026 is October 25. Because October 25 falls on a Sunday in 2026, the actual deadline is Monday, October 26.
Sole Proprietors May Also File a Preliminary Return if Sales Have Fallen Significantly
Being subject to a preliminary notice does not necessarily mean a business owner must pay only the amount stated in that notice under all circumstances.
A preliminary return may be filed if, due to a business suspension, poor business performance, or similar circumstances, the value of supplies or VAT payable for 7–September falls below 1 out of 3 of the corresponding amount for the preceding tax period.
A preliminary return may also be filed when the business owner seeks an early VAT refund.
When a preliminary return is filed under these qualifying conditions, the original preliminary notice determination is treated as though it had never been made. Therefore, a business owner cannot simply reduce the amount stated in the notice and pay less merely because sales have declined slightly. The first step is to confirm whether the requirements for filing a preliminary return are satisfied.
Distinguishing the Below-KRW 500,000 Exclusion From a Preliminary Return Due to Poor Business Performance
The differences become clearer when the two systems are compared side by side.
When the preliminary notice amount is below KRW 500,000, the tax office does not collect that amount through a preliminary notice because it falls within the statutory exclusion threshold. Individual business owners subject to general taxation generally report and settle the entire tax period's business results in the subsequent final VAT return.
By contrast, a preliminary return due to poor business performance or similar circumstances involves a business owner who would ordinarily be subject to a preliminary notice filing a return based on actual results for 7–September. This applies when the value of supplies or VAT payable falls below the statutory threshold of 1 out of 3, or when the business owner seeks an early refund.
Therefore, the two systems should not be treated as identical simply because both may result in a business owner not paying an amount in October or handling the tax differently from the amount originally stated in a notice.
What Should Business Owners Check in October 2026?
For individual business owners subject to general taxation, the first step is to check whether a preliminary notice has been issued and, if so, the amount stated in it.
If no preliminary notice was issued because the amount was below KRW 500,000, that exclusion alone does not create a separate obligation to file a preliminary return in October. The business owner will subsequently settle the results for 7–December through the final VAT return for the 2 tax period.
The situation is different if a preliminary notice has been issued but business performance has deteriorated significantly during 7–September. In that case, the business owner should compare the value of supplies and VAT payable for 7–September against the corresponding amounts for the preceding tax period to determine whether the requirements for filing a preliminary return are met.
If those requirements are satisfied, the return should be handled in accordance with the filing and payment deadline of October 26 for the preliminary VAT return for the 2 tax period of 2026.
The applicable procedures may differ depending on the business owner's VAT classification, whether that classification has changed, the extent of the business downturn, and whether an early refund is involved. Therefore, the most accurate approach is to verify the actual notice status and filing obligations for the specific business through Hometax, South Korea's electronic tax administration service, or the tax office with jurisdiction over the business.
※ This article is provided for reference purposes to help readers understand market trends and does not constitute an investment recommendation concerning any particular security or asset. Readers are responsible for their own final investment decisions and the associated risks.