

115 Days Until Crypto Taxation in 2027: Where Do the Abolition and 2029 and 2030 Deferral Bills Stand?
이 포스팅은 쿠팡 파트너스 활동의 일환으로, 이에 따른 일정액의 수수료를 제공받습니다.
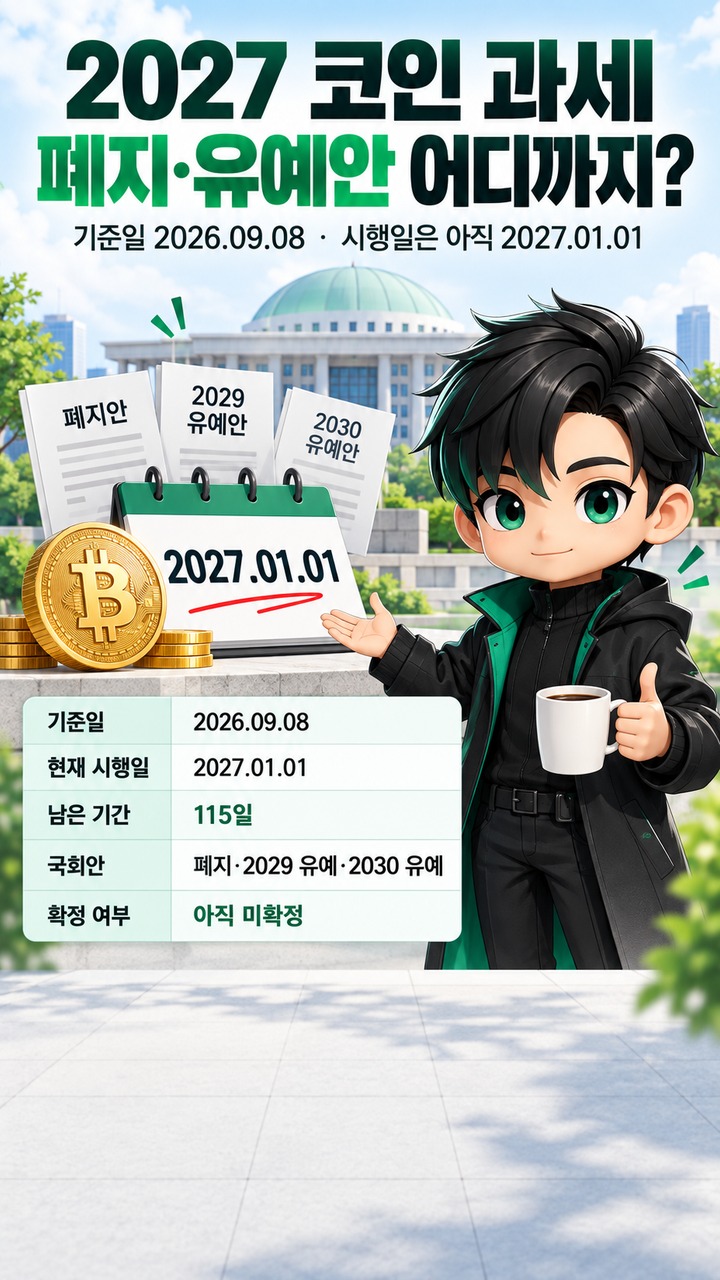
As of 2026-09-08, the effective date for taxation of virtual asset income remains 2027-01-01. A bill to abolish the tax, a proposal to defer it by another 2 years until 2029, and a proposal to defer it by another 3 years until 2030 have all been submitted to the National Assembly, but none has been finalized.
There are 115 days remaining until 2027-01-01. It is still too early to conclude that 'crypto taxation has been postponed again' or that 'abolition has been decided.'
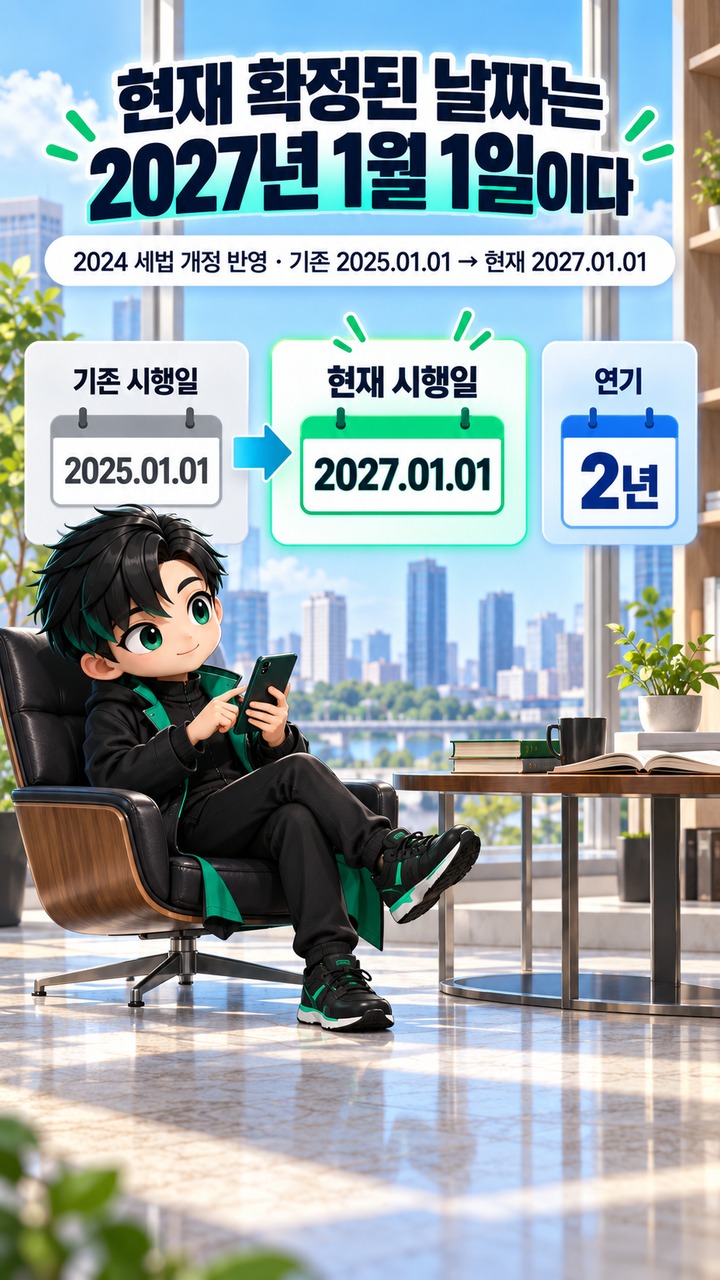
The Currently Confirmed Effective Date Is 2027-01-01
The existing virtual asset taxation system is designed to separately tax income generated from the transfer or lending of virtual assets as other income. Under the tax law revision in 2024, the start date for taxation was postponed by 2 years, from 2025-01-01 to 2027-01-01, and this change has already been incorporated into law.
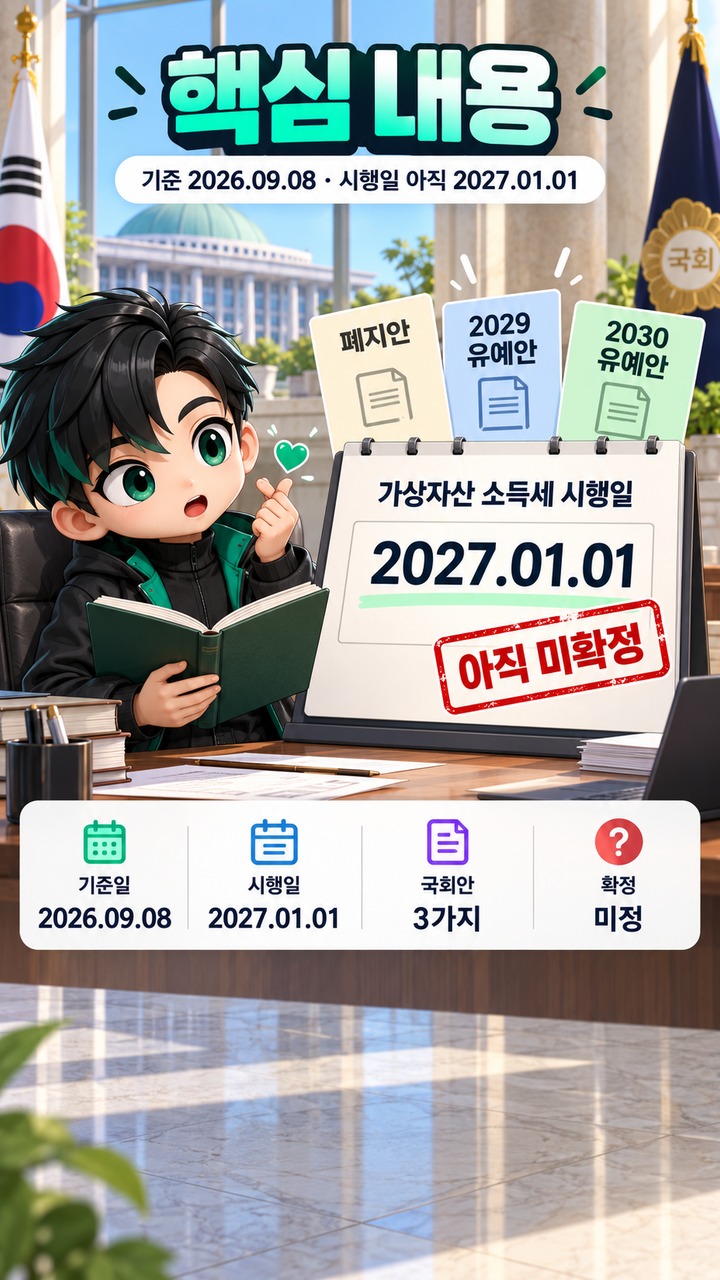
This can easily be confused with the '2-year deferral' currently being discussed in the National Assembly.
The 2-year deferral finalized in 2024 was 2025 → 2027. By contrast, the new 2-year deferral bill submitted on August 2026 proposes 2027 → 2029. Although both are described as a '2-year deferral,' the former is a previously enacted amendment, while the latter is a new bill still under review by the National Assembly.
The distinction becomes clearer when the changes to the implementation schedule are viewed chronologically. Taxation of virtual asset income was originally designed to take effect in 2022, but implementation was successively postponed to 2023 and 2025. Following the tax law revision in 2024, it was postponed again to 2027.
Therefore, when assessing the current tax schedule, the starting point should not be that 'a deferral is under discussion,' but rather that the effective date currently written into law is 2027-01-01.
The Abolition Bill Has Been Introduced in the Standing Committee and Referred to a Subcommittee
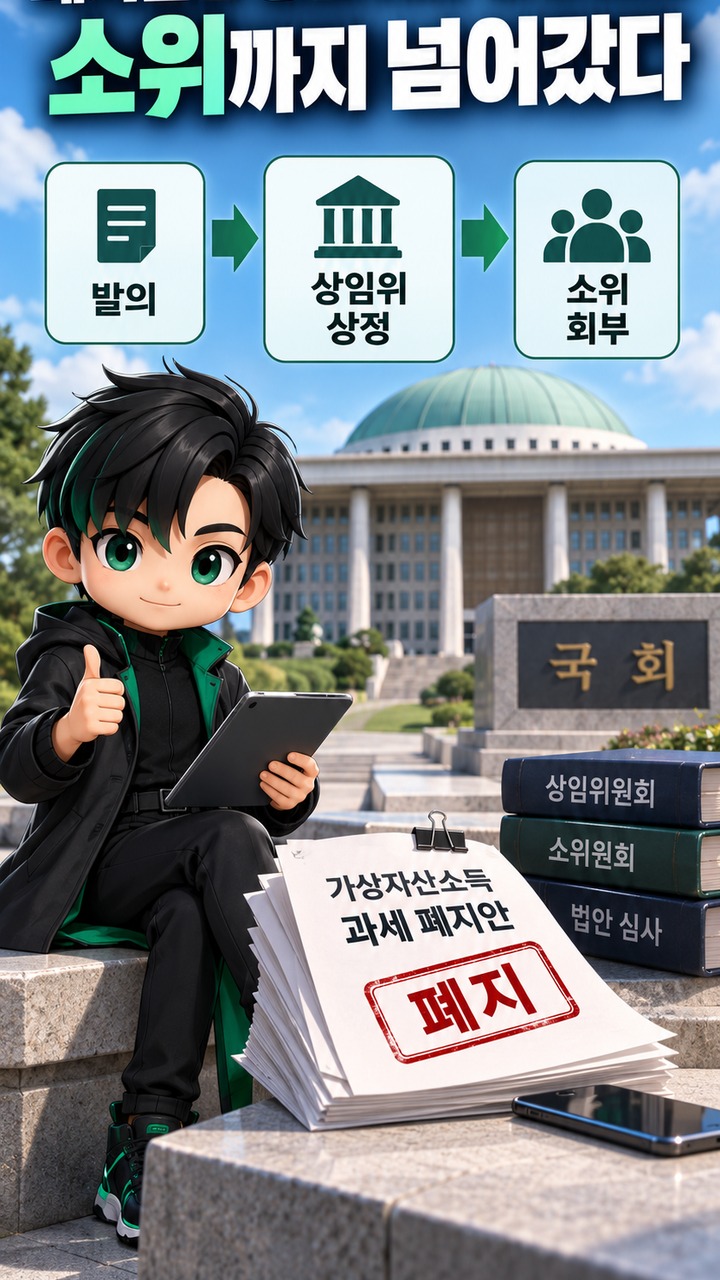
The most significant proposal is not to delay taxation but to eliminate the provisions governing taxation of virtual asset income altogether.
A partial amendment to the Income Tax Act submitted on 2026-03-19 by lawmaker Song Eon-seok and 12 others seeks to delete the relevant provisions that classify income from the transfer or lending of virtual assets as taxable other income.
The bill was referred to the Finance, Economy and Planning Committee on March 20. At its plenary meeting on July 29, the bill was introduced, its proposal was explained, a review report was presented, alternative proposals were discussed, and it was referred to a subcommittee.
In other words, the proposal has advanced beyond the stage of merely discussing abolition, but abolition has not been finalized. Standing committee review and subsequent legislative procedures remain.
When searching for information, a headline such as 'Crypto Tax Abolition Bill Proposed' can easily create the impression that the tax has already been eliminated. However, introducing a bill and enacting it into law are entirely different stages.
A New 2-Year Deferral Bill Has Also Been Submitted to Postpone Taxation Until 2029
There is also a bill that would retain virtual asset taxation but postpone the current 2027 implementation date by another 2 years to 2029-01-01.
The partial amendment to the Income Tax Act submitted on 2026-08-28 by lawmaker Kim Sang-hoon and 12 others would change the effective date for virtual asset income taxation from the current 2027-01-01 to 2029-01-01.
The bill was referred to the Finance, Economy and Planning Committee on August 31. As of the review conducted on 2026-09-08, publicly available legislative progress records did not indicate any subsequent introduction for deliberation or decision.
If this proposal passes, it would not abolish the taxation system. Instead, it would simply move the implementation date back by 2 years. For now, however, it remains a bill submitted to the National Assembly and referred to the relevant committee.
Particular caution is needed when encountering claims that a '2-year deferral has been confirmed.' The 2-year postponement from 2025 to 2027 has already been enacted, but the new proposal to postpone implementation from 2027 to 2029 has not.
The 3-Year Deferral Bill Proposing Implementation in 2030 Is at the Committee Referral Stage
Another proposal seeks an additional 3-year deferral by changing 2027-01-01 to 2030-01-01.
Lawmaker Jeong Seong-guk and 11 others introduced a partial amendment to the Income Tax Act on 2026-08-10. It proposes postponing virtual asset income taxation, currently scheduled under existing law to begin in 2027, by 3 years so that it would take effect in 2030.
The bill was referred to the Finance, Economy and Planning Committee on August 11. As of September 8, publicly available legislative progress records showed no introduction for deliberation or plenary session decision.
Therefore, it is also inaccurate at this stage to say that 'taxation has been postponed until 2030.' More precisely, a bill proposing implementation in 2030 is pending in the National Assembly.
The proposals currently before the National Assembly fall into three broad directions.
| Category | Proposal | Status as of 2026-09-08 |
|---|---|---|
| Current law | Implementation on 2027-01-01 | Current legal baseline |
| Abolition bill | Delete provisions taxing virtual asset income | Introduced for deliberation and referred to a subcommittee |
| Additional 2-year deferral bill | Implementation on 2029-01-01 | Referred to the relevant committee |
| Additional 3-year deferral bill | Implementation on 2030-01-01 | Referred to the relevant committee |
The most important part of this table is not the dates but the final column. 2029 and 2030 are not yet legally established implementation dates. They are dates proposed in the respective bills.
How Would the Tax Be Calculated if Implementation in 2027 Remains Unchanged?
The existing system classifies income generated from the transfer or lending of virtual assets as other income. The annual basic deduction for residents is KRW 2,500,000, and the income tax rate is 20%. Including local income tax, the combined tax burden follows a 22% structure.
The taxable amount is not simply the total proceeds received from selling cryptocurrency. Virtual asset income is calculated by accounting for necessary expenses, including acquisition costs, against proceeds from transfers or lending. Gains and losses within the same tax period are then offset against each other before the basic deduction is applied.
For example, suppose annual taxable virtual asset income is KRW 10,000,000. After subtracting the basic deduction of KRW 2,500,000, the amount used as the calculation base would be KRW 7,500,000.
The author's calculation is as follows.
KRW 7,500,000 × 20% = Income tax of KRW 1,500,000
If local income tax equivalent to 10% of the income tax is then applied in a simplified calculation, an additional KRW 150,000 is added, bringing the total to KRW 1,650,000. This is a simplified example applying 22% including local income tax. In actual tax filings, taxable income may vary depending on individual transaction records, acquisition costs, and whether necessary expenses are recognized.
More important than the calculation method itself is confirming the implementation date first. If the National Assembly amends the law again before the end of the year, the start date for taxation could change.
Why Should Investors Monitor Legislative Developments Starting in September 2026?
There are 115 days remaining until 2027-01-01.
According to the author's calculation, the difference between 2026-09-08 and 2027-01-01 is 115 days. Although this is roughly four months on the calendar, the actual remaining period is shorter than 4 months.
What virtual asset investors need to monitor now is not a prematurely finalized tax calculation, but whether the National Assembly actually passes legislation changing the current implementation date.
Distinguishing among three legislative terms can help reduce confusion.
'Bill introduction' means that a lawmaker has submitted a bill to the National Assembly.
'Referral to the relevant committee' means that the appropriate standing committee has been assigned to review the bill.
'Referral to a subcommittee' likewise means that the review process is underway, not that the bill has become law.
For the start date of virtual asset taxation to actually change to 2029 or 2030, the relevant amendments to the Income Tax Act must complete the National Assembly's legislative process and be finalized.
Which Date Should Investors Use as Their Current Reference Point?
As of 2026-09-08, 2027-01-01 remains the appropriate reference date.
The abolition bill has been introduced in the standing committee and referred to a subcommittee. The 2-year deferral bill proposing implementation in 2029 and the 3-year deferral bill proposing implementation in 2030 have also been submitted to the National Assembly. However, none of these three bills has changed the current law.
Therefore, it would be premature to state definitively that 'crypto taxation has been abolished,' '2029 has been confirmed,' or '2030 has been confirmed.'
The key figures to watch are not cryptocurrency prices but which of 2027, 2029, and 2030 ultimately remains in the enacted legislation. While legislative review continues, it is more accurate to check standing committee approval, passage by the National Assembly's plenary session, and promulgation of the law, in that order, rather than relying solely on news of bill introductions.
※ This article is provided for informational purposes to help readers understand market developments and does not constitute a recommendation to invest in any particular security or asset. All final investment decisions and responsibility rest with the individual investor.
Related Articles
이 포스팅은 쿠팡 파트너스 활동의 일환으로, 이에 따른 일정액의 수수료를 제공받습니다.