

2026 Mortgage Loan Limit on an Annual Salary of KRW 50,000,000: How Much Does an Existing Personal Loan Change It? Stress DSR Calculation Guide
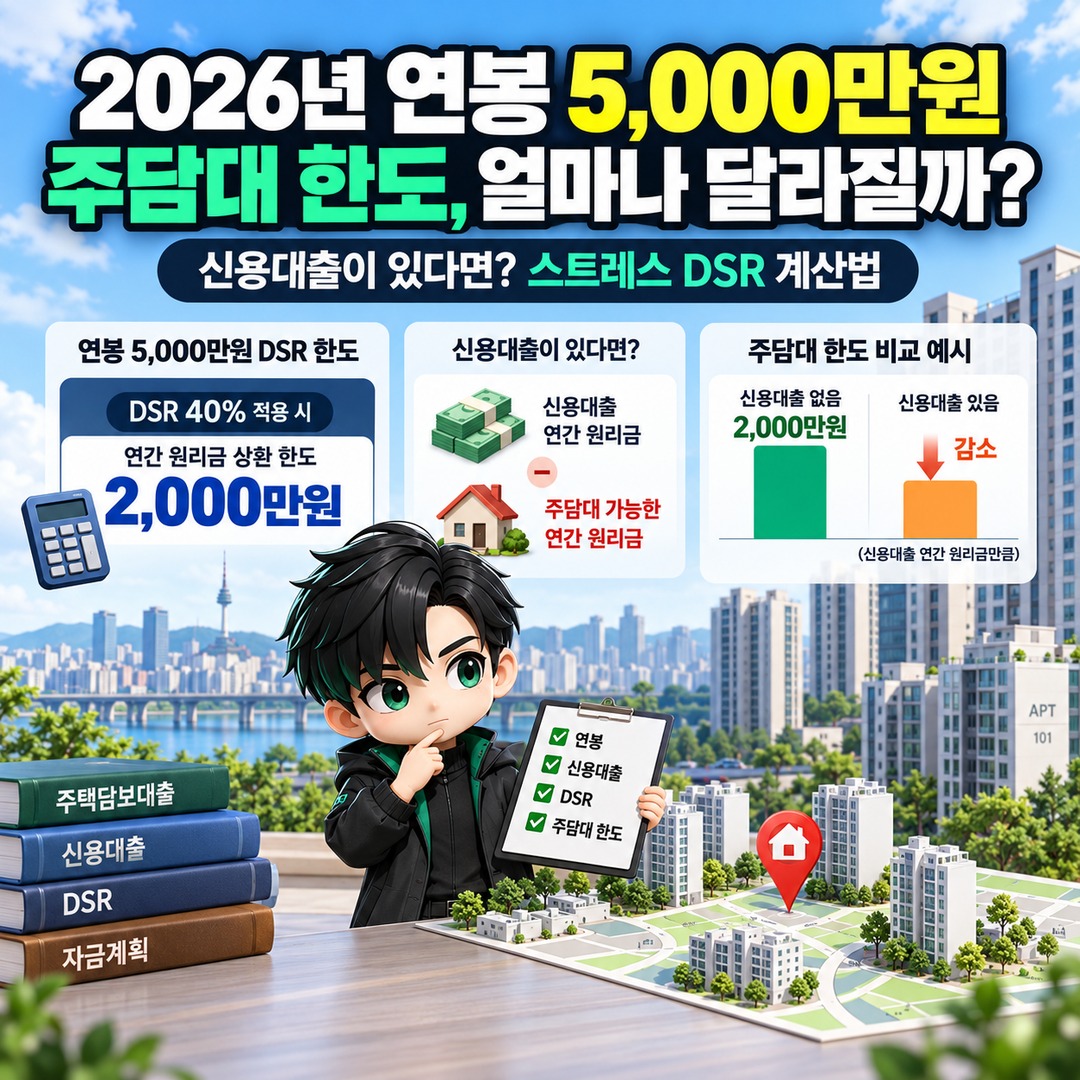
If a salaried employee earning KRW 50,000,000 annually has an existing personal loan, their mortgage borrowing limit is affected by the annual principal and interest payments on that debt. Under the banking sector's DSR limit of 40%, the annual debt repayment allowance is KRW 20,000,000. However, the actual mortgage amount available varies depending on the outstanding personal loan balance and repayment structure.
As of 2026-10-16, anyone preparing to purchase a home should check not only their outstanding personal loan balance but also the property's location, the mortgage interest rate type, and how the stress interest rate is applied.
How Much Can Someone Earning KRW 50,000,000 Annually Repay on a Mortgage?
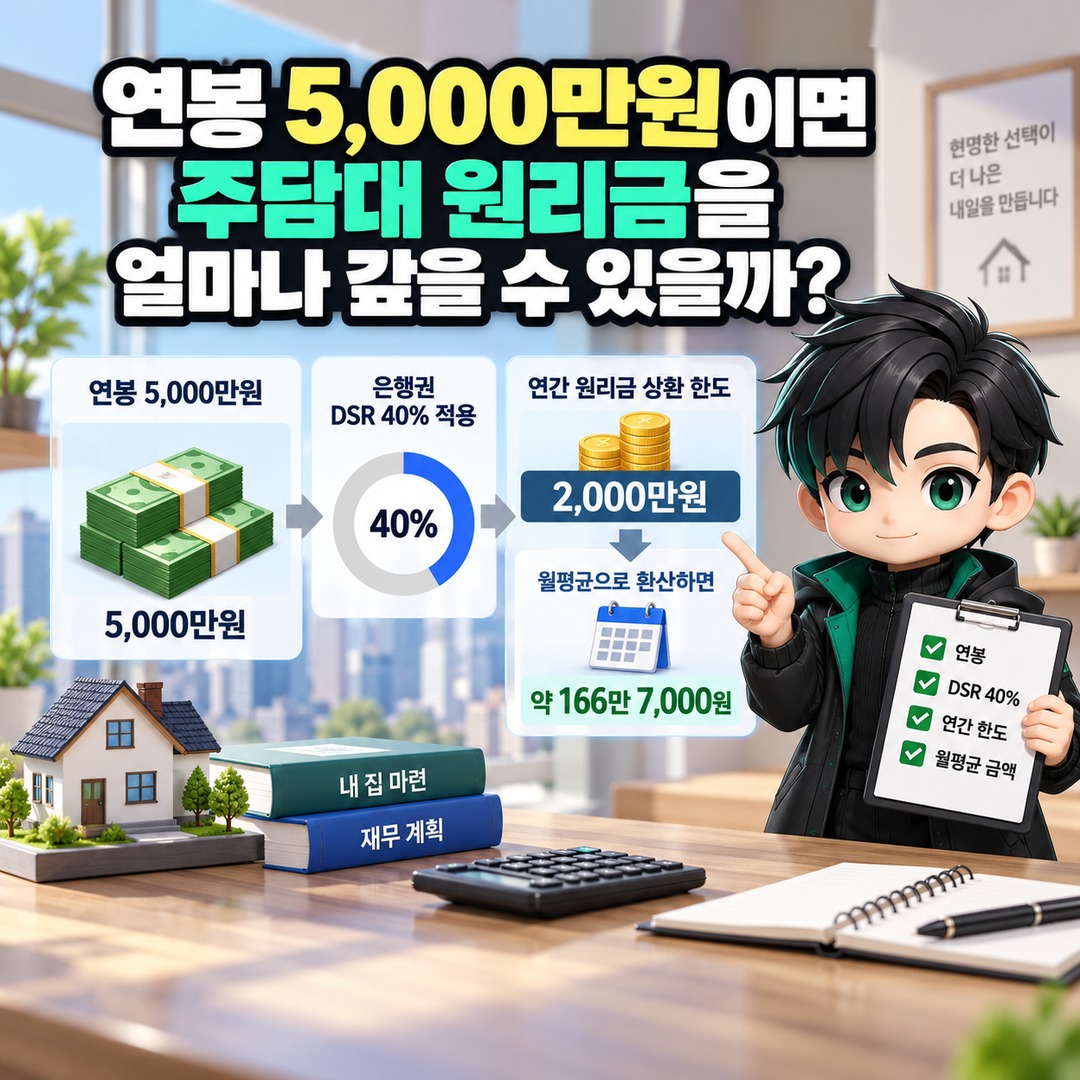
Under the banking sector's DSR limit of 40%, a borrower earning KRW 50,000,000 annually can make annual principal and interest payments of up to KRW 20,000,000. This translates to approximately KRW 1,667,000 per month on average.
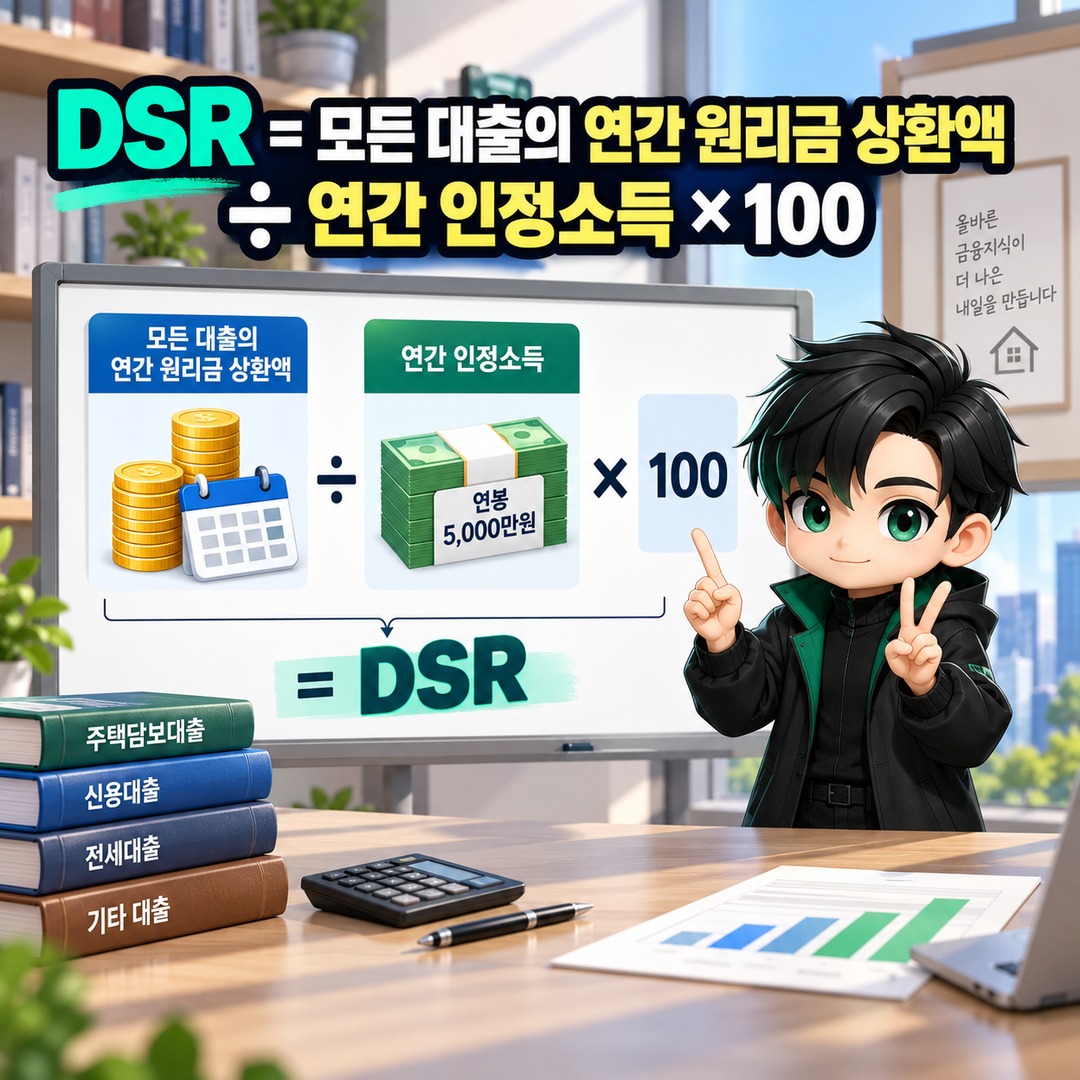
DSR stands for Debt Service Ratio. It measures the proportion of annual income used to repay the principal and interest on all loans.
The calculation is as follows.
DSR = Annual Principal and Interest Payments on All Loans ÷ Recognized Annual Income × 100
Assuming the bank recognizes the full annual salary of KRW 50,000,000 and applies a DSR limit of 40%, the results are as follows.
| Category | Calculation Result |
|---|---|
| Recognized annual income | KRW 50,000,000 |
| Applicable DSR ratio | 40% |
| Annual principal and interest repayment limit | KRW 20,000,000 |
| Average monthly repayment limit | Approximately KRW 1,667,000 |
The important point is that the monthly allowance of KRW 1,667,000 is not reserved exclusively for mortgage payments.
If the borrower has existing personal loans, automobile installment financing, or other debts included in the DSR calculation, the principal and interest payments on those obligations must be accounted for first.
In addition, an annual salary of KRW 50,000,000 does not necessarily mean the bank will recognize KRW 50,000,000 as income for DSR purposes. Income documentation and the bank's underwriting criteria must be checked.
Why Does an Existing Personal Loan Reduce the Mortgage Limit?
An existing personal loan reduces the annual repayment capacity available for a new mortgage.
For example, if a borrower has an annual DSR repayment allowance of KRW 20,000,000 but already pays KRW 6,000,000 annually toward the principal and interest on an existing personal loan, the annual repayment amount available for a new mortgage is KRW 14,000,000.
The author's calculations provide the following comparison.
| Annual Principal and Interest Payments on Existing Loans | Remaining Annual Repayment Capacity for a Mortgage |
|---|---|
| KRW 0 | KRW 20,000,000 |
| KRW 3,000,000 | KRW 17,000,000 |
| KRW 6,000,000 | KRW 14,000,000 |
| KRW 9,000,000 | KRW 11,000,000 |
This table presents a simplified calculation assuming a banking sector DSR limit of 40% and recognized income of KRW 50,000,000. The principal and interest amounts used in actual DSR calculations vary depending on the loan type, recognized repayment term, and repayment method.
Therefore, having an outstanding personal loan balance of KRW 30,000,000 does not mean the mortgage borrowing limit will decrease by exactly KRW 30,000,000.
When determining a mortgage limit, the annual principal and interest payments included in the DSR calculation matter more than the outstanding loan balance itself.
How Is Stress DSR Different From Regular DSR?
Stress DSR is a method that adds a specified stress interest rate to the rate used for loan assessment to account for the risk of interest rates rising during the repayment period.
Introduced by the Financial Services Commission, this system incorporates the potential repayment burden from future interest rate increases into mortgage limit calculations in advance.
While a regular DSR calculation evaluates the principal and interest repayment burden of existing and new loans, stress DSR assesses repayment capacity using principal and interest amounts calculated with an additional stress interest rate applied to eligible loans.
For example, suppose the actual annual interest rate on a new mortgage is 4.0% and the applicable stress interest rate is 1.5% percentage points. The annual interest rate used for the DSR calculation would then be 5.5%.
However, these figures are hypothetical and are intended to illustrate the calculation method. Actual stress interest rates vary depending on the region and the interest rate structure of the loan product.
The Stress Interest Rate Is Not Added Directly to the Actual Loan Rate as Interest Charged to the Customer.
It is used to determine the borrowing limit during underwriting and must be distinguished from the actual contractual interest rate.
Are Personal Loans of KRW 100,000,000 or Less Exempt From Stress DSR?
Under the criteria applied to date, personal loans with a combined outstanding balance of KRW 100,000,000 or less have been excluded from the requirement to apply an additional stress interest rate to the personal loans themselves. However, this does not mean that the principal and interest payments on existing personal loans are excluded from the regular DSR calculation.
The Financial Services Commission established that, under the 3-stage stress DSR framework implemented from 2025-07-01, the stress interest rate applies when the total outstanding personal loan balance exceeds KRW 100,000,000.
Two distinctions are important here.
Regular DSR: The assessed principal and interest payments on existing personal loans are included in mortgage underwriting.
Stress DSR: Whether an additional stress interest rate applies to the personal loan itself is determined under separate criteria.
Having personal loans of KRW 100,000,000 or less does not automatically entitle a borrower to the same mortgage limit as someone with no existing debt.
Will Stress DSR Be Calculated the Same Way in the Seoul Metropolitan Area and Other Regions in 2026?
Stress DSR requirements may vary depending on the property's location, so the same interest rate should not be applied uniformly across all regions.
In its December 2025 announcement, the Financial Services Commission outlined a policy of maintaining the 2-stage stress DSR framework for mortgages on properties in non-regulated areas outside the Seoul metropolitan region during the first half of 2026. The applicable rules differed between the Seoul metropolitan area and regulated regions, and non-regulated areas outside the metropolitan region.
In addition, following the 2025-10-15 measures, criteria were introduced applying a minimum stress interest rate of 3.0% to mortgages in the Seoul metropolitan area and regulated regions.
However, the rules announced for the first half of 2026 should not be applied unchanged to new loans in October. The applicable interest rates for the second half of the year, regional regulations, and product-specific application ratios must be checked separately.
Even borrowers with identical annual salaries and outstanding personal loan balances may receive different mortgage limit calculations depending on the property's location and the loan product.
How Can You Calculate Your Mortgage Limit Step by Step?
To calculate a mortgage borrowing limit, first determine the annual principal and interest payments attributable to existing loans. Then calculate the maximum new mortgage principal based on the remaining repayment capacity.
Follow these steps.
1. Confirm the annual income recognized by the bank.
2. Multiply that income by the applicable DSR ratio to determine the annual repayment limit.
3. Subtract the principal and interest payments on existing debts, including personal loans, as assessed for DSR purposes.
4. Account for the mortgage's actual interest rate, stress interest rate, repayment period, and repayment method.
5. Compare the calculated DSR-based limit with limits imposed by LTV and other lending regulations.
For a mortgage with equal monthly principal and interest payments, the loan principal can be calculated backward from the monthly repayment amount.
The basic formula used to calculate the monthly payment is as follows.
\[
M=P\frac{r(1+r)^n}{(1+r)^n-1}
\]
Here, M represents the monthly repayment amount, P is the loan principal, r is the monthly interest rate, and n is the total number of monthly repayments.
For loans subject to stress DSR, the calculation uses the interest rate adjusted by the additional rate applied during underwriting rather than only the actual contractual interest rate.
For example, if the mortgage's actual annual interest rate is 4.0% and the applicable stress interest rate is 1.5% percentage points, divide the assessment interest rate of 5.5% by 12 months to obtain the monthly interest rate.
However, this calculation alone cannot establish the final approved borrowing limit. Financial institutions also assess the recognized repayment term for each loan, existing debts, collateral value, and separate lending restrictions.
Will Repaying a Personal Loan First Increase Your Mortgage Limit?
If repaying a personal loan reduces the principal and interest payments included in the DSR calculation for existing debts, the repayment capacity available for a new mortgage may increase.
However, the effect of partially repaying a personal loan depends on the loan agreement and the method used to calculate DSR.
A reduction in the outstanding personal loan balance and the resulting reduction in annual principal and interest payments recognized for DSR purposes must be evaluated separately.
If you are preparing to purchase a home, rather than automatically repaying your personal loan first, it is more accurate to ask the bank to calculate the available mortgage amount under two scenarios: keeping the existing loan and partially repaying it.
In particular, using available cash to repay a personal loan reduces the funds available for purchasing a home. You should compare the benefit of a potentially higher mortgage limit with the reduction in cash you can actually use.
Why DSR Calculation Results Differ From Actual Bank Lending Limits
The amount calculated using DSR represents a borrowing limit based on repayment capacity. The actual approved mortgage amount may be lower because of other regulations and underwriting requirements.
For example, LTV, or Loan-to-Value ratio, limits the loan amount relative to the value of the property offered as collateral.
Even if a borrower can afford higher repayments under DSR rules, that does not mean they can borrow beyond the limits imposed by collateral value and regional lending restrictions.
The purpose of the home purchase, the number of properties already owned, the property's location, the type of loan product, and each bank's lending conditions must also be checked.
Therefore, simply entering the outstanding personal loan balance is not enough to accurately determine the mortgage borrowing limit for a salaried employee earning KRW 50,000,000 annually.
The Information Needed for an Actual Calculation Includes the Outstanding Personal Loan Balance and Interest Rate, the Repayment Term Recognized for DSR Purposes, the Mortgage Interest Rate Type, the Property's Location, the Property Price, and the Repayment Period.
With this information, you can ask the bank to compare the borrowing limits available when keeping the existing personal loan versus repaying it, allowing you to make a more realistic assessment of the funds available for purchasing a home.
※ This article is provided for reference to help readers understand market trends and does not constitute an investment recommendation for any particular security or asset. Final decisions and responsibility for investments rest with the individual.