

October 2026 VAT Advance Notice: Payment Due by November 2, Who Must Pay and How It Differs from the October 26 Filing Deadline
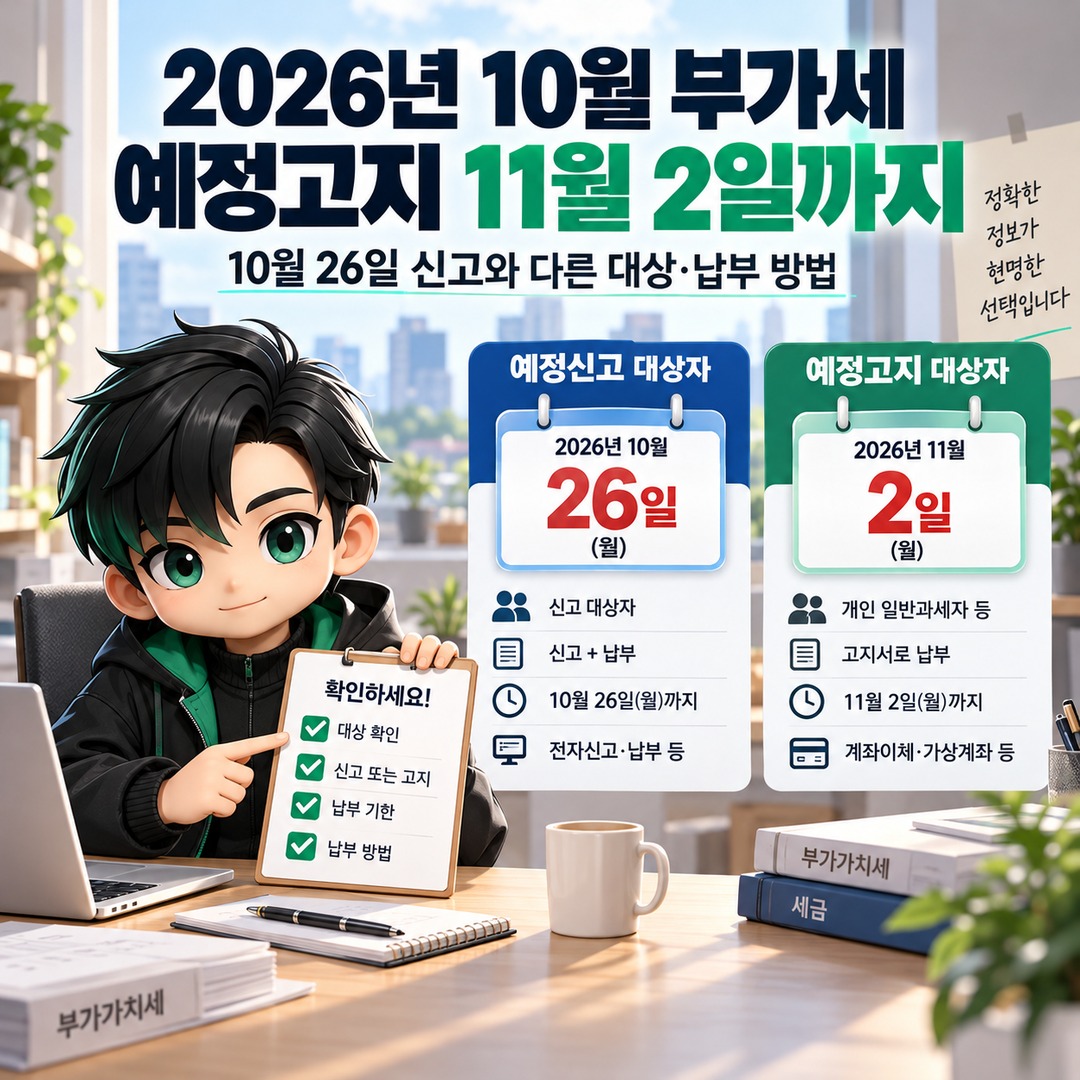
The payment deadline for the October 2026 VAT advance notice is Monday, November 2. In contrast, businesses required to file a preliminary VAT return must complete both filing and payment by Monday, October 26. Although both dates concern the same tax, the businesses affected and the required procedures differ.
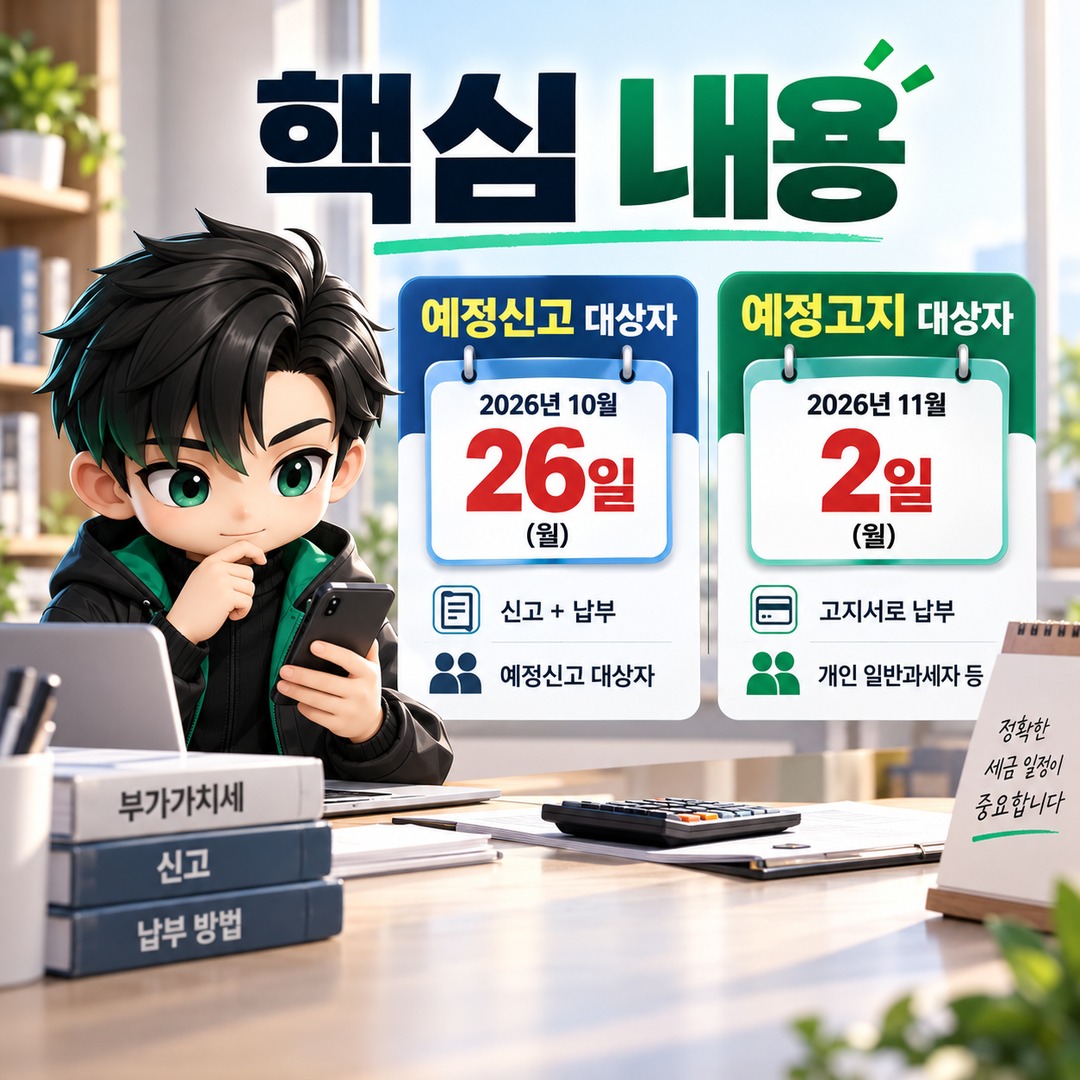
According to the schedule announced by the National Tax Service (NTS) on 2026-10-05, individual general VAT taxpayers and small corporations meeting certain requirements generally pay the amount stated in their advance tax notice instead of filing a preliminary return.
However, businesses experiencing a substantial decline in business performance or qualifying for an early refund may choose to file a preliminary return. It is therefore important to check your business classification first.
November 2 vs. October 26: Which Businesses Does Each Deadline Apply To?
The key distinction between the two dates is whether a business must file its own VAT return or simply pay the amount assessed by the NTS.
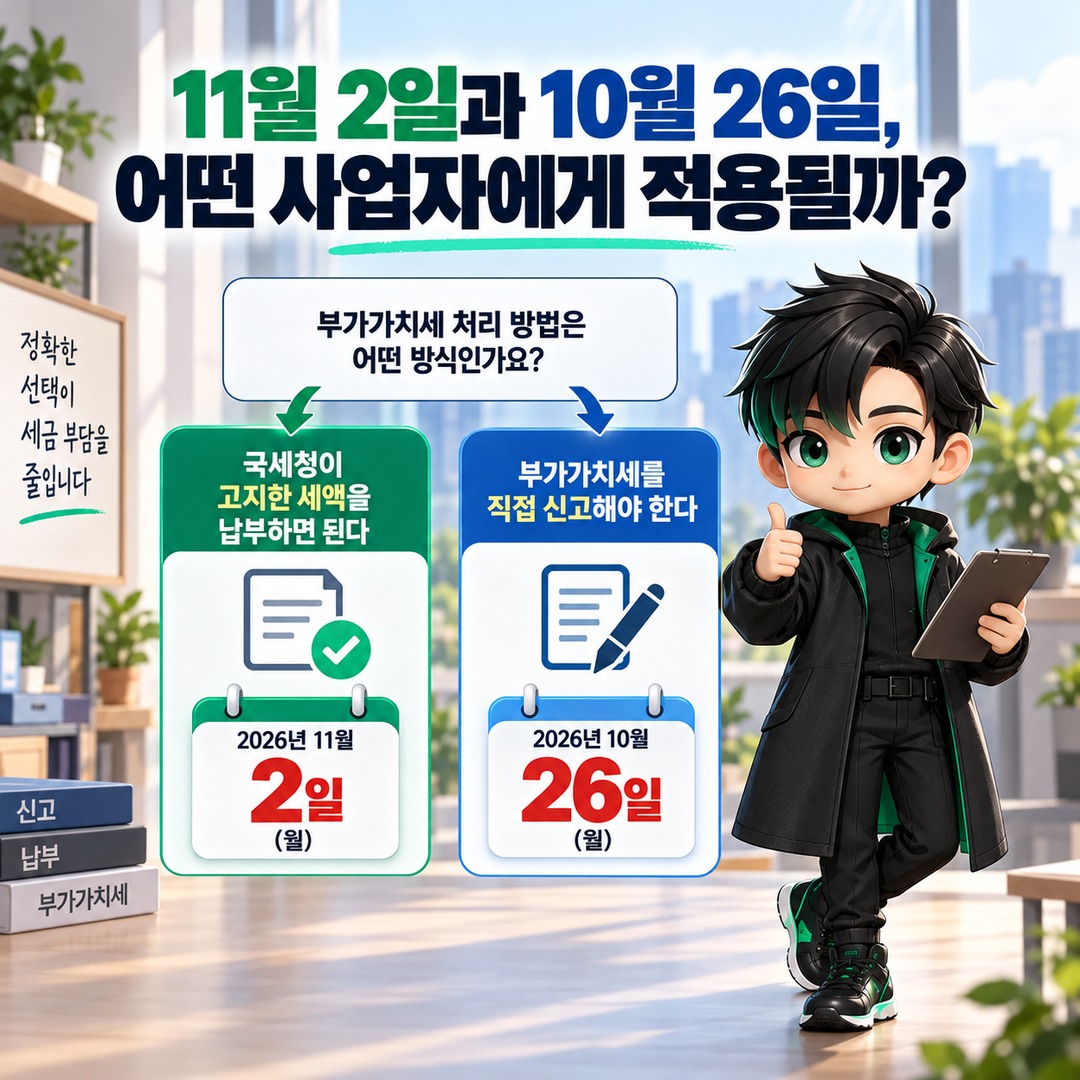
| Category | Preliminary VAT Filing and Payment | Advance VAT Notice Payment |
|---|---|---|
| Deadline | October 26 (Mon) | November 2 (Mon) |
| Applicable businesses | Businesses required to file preliminary VAT returns | Individual general VAT taxpayers and small corporations |
| Procedure | Submit a tax return and pay the tax due | Pay the amount stated in the tax notice |
| Applicable period | 2026, 7~September | Assessed based on tax paid during the previous taxable period |
The preliminary VAT return for the 2 period of 2026 covers business activity from July 1 through September 30.
The advance notice system does not require businesses to calculate and report sales and purchases for this period themselves. Instead, the NTS issues an advance tax assessment based on the VAT paid during the previous taxable period.
Therefore, being an individual business owner does not automatically mean you must submit a tax return by October 26. The first step is to determine whether you are subject to an advance tax notice or must file a separate preliminary return.
Why Is the Advance VAT Notice Payment Deadline Set for November 2?
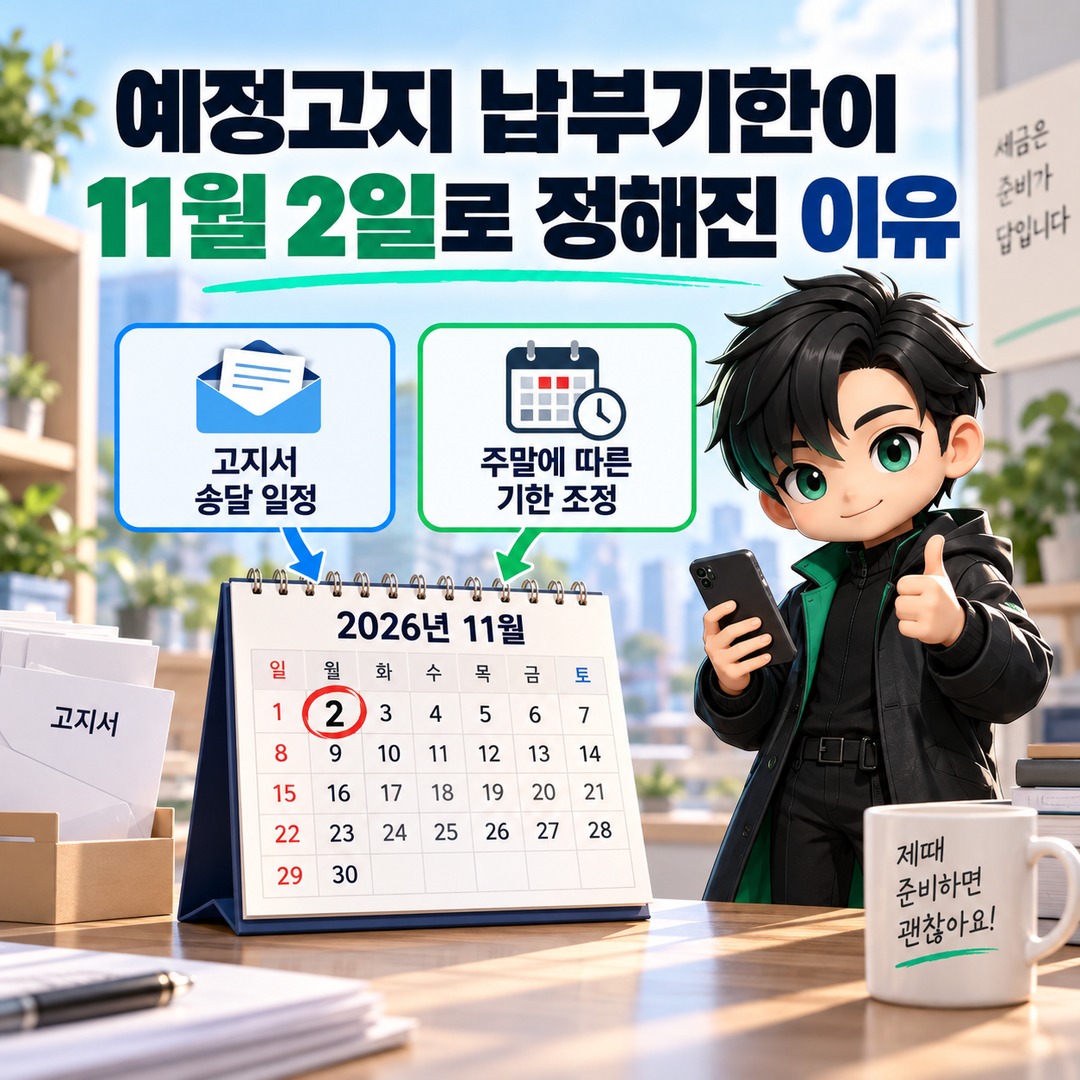
The advance notice payment deadline for 2026 reflects adjustments related to the delivery schedule for tax notices and the weekend.
The NTS extended the payment deadline to the end of October, taking into account possible delays in delivering advance tax notices because of the concentration of holidays, including National Foundation Day and Hangeul Day, in early October.
However, 2026-10-31 falls on a Saturday.
When a tax payment deadline falls on a Saturday or public holiday, regulations extend the deadline to the next day recognized as a valid statutory deadline.
As a result, the actual advance notice payment deadline became Monday, November 2.
An important distinction is that the preliminary VAT filing deadline was not also extended to November 2.
Unless they qualify for a separate extension, businesses required to file preliminary returns must prepare for the October 26 deadline.
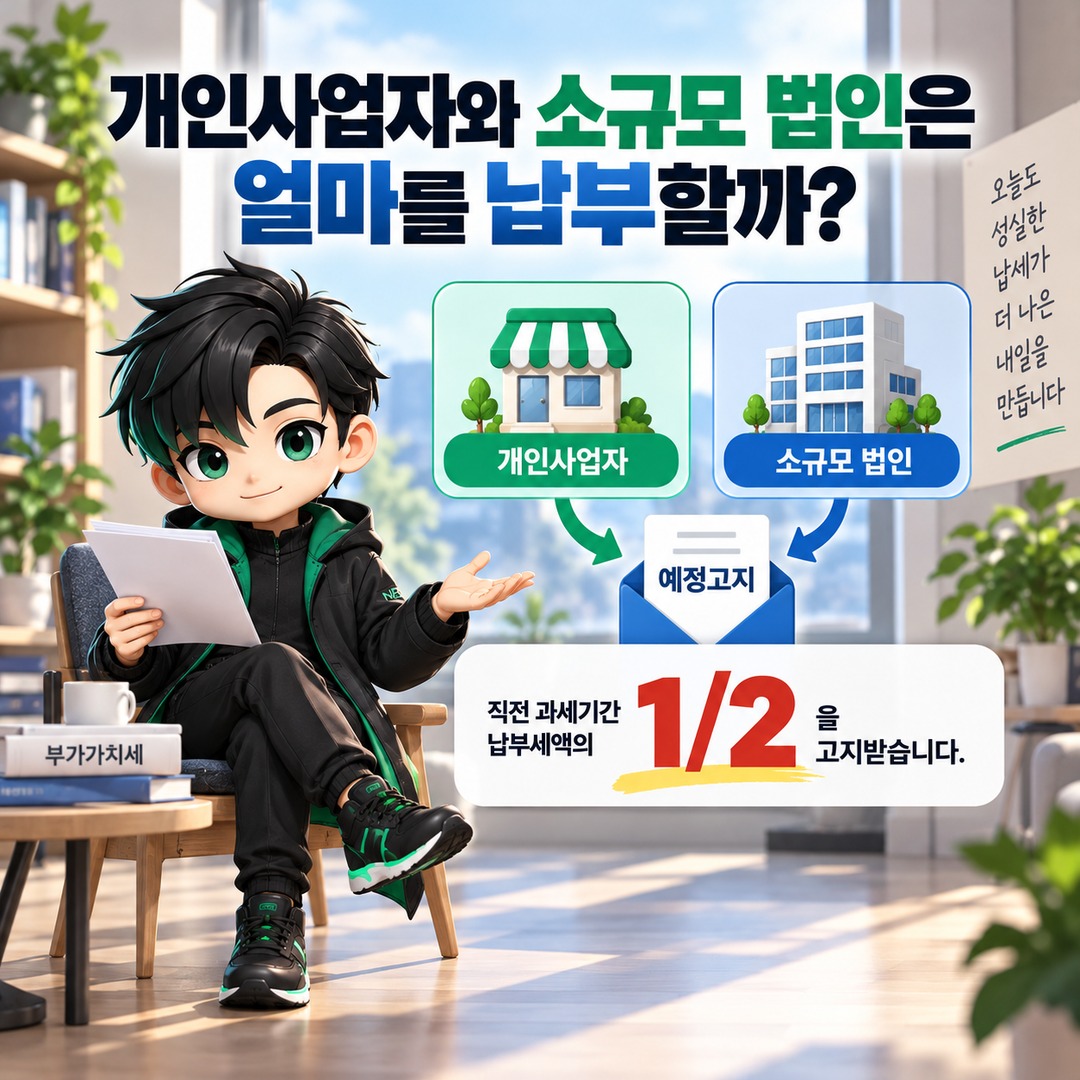
How Much Must Individual Business Owners and Small Corporations Pay?
Businesses subject to an advance tax notice are generally assessed half of the VAT paid during the previous taxable period.
For the October 2026 advance notice, the calculation is based on the tax paid for the period from 2026-01-01 through June 30.
The system applies to individual general VAT taxpayers and small corporations whose total value of supplies during the previous taxable period was less than 1 hundred million 5 ten million won.
For example, if the VAT paid during the previous taxable period was KRW 2,000,000, half that amount, KRW 1,000,000, would serve as the basis for calculating the advance assessment. The actual amount payable must be verified on the NTS tax notice.
Because small-corporation eligibility is determined using the value of supplies, which reflects sales volume, individual businesses and corporations should not be assessed using identical criteria.
Can You File a Preliminary VAT Return If Sales Have Fallen Significantly?
Even businesses that have received an advance tax notice may file a preliminary VAT return if they meet certain conditions.
The NTS has explained that businesses may file a preliminary return if their sales or VAT payable for the period from July 2026 through September fall below 1/3 of the corresponding amount for the previous taxable period, or if circumstances qualifying them for an early refund arise.
When a preliminary return is filed, the previously assessed advance tax amount is canceled.
Therefore, businesses experiencing a substantial decline in sales should review the eligibility requirements for preliminary filing rather than simply checking the amount shown on their tax notice.
If you choose to file a preliminary return, the deadline is October 26, not November 2.
Where Can You Check Your Advance VAT Assessment and Payment Obligation?
Businesses subject to an advance tax notice can check the amount payable on the notice issued by the NTS.
If you have not received the notice or need to verify the amount again, you can use Hometax or the NTS automated telephone service at 1544-9944.
The following sequence is useful when checking your obligations.
1. Confirm whether your business is classified as an individual general VAT taxpayer or a corporation.
2. Check whether an advance VAT assessment has been issued.
3. Verify the assessed amount and payment deadline.
4. Determine whether your business has experienced a decline in performance or qualifies for an early refund.
5. If you are subject to an advance tax notice, pay by the stated deadline. If you need to choose preliminary filing, complete the process by the filing deadline.
In particular, receiving an advance tax notice does not necessarily mean you are ineligible to choose preliminary filing.
Are Some Businesses Eligible for a Separate Payment Deadline Extension?
Additional tax relief measures have also been introduced for certain affected businesses in October 2026.
The NTS announced support extending the VAT payment deadline by 2 months for businesses affected by heavy rainfall and businesses affected by circumstances related to Homeplus.
This assistance should be distinguished from the general payment deadline that applies to businesses overall.
Affected businesses must individually verify whether they qualify for the support and which payment deadline actually applies to them.
What to Check First When Preparing for VAT Obligations in October
The most important factor in the October 2026 VAT schedule is not the date itself, but whether your business is required to file a return or pay an advance assessment.
If you are required to file a preliminary return, you must complete filing and payment by October 26. If you are subject to an advance tax notice, the general rule is to pay the assessed amount by November 2.
However, some businesses subject to advance notices may choose preliminary filing because of declining business performance or eligibility for an early refund. Separate payment deadlines may also apply to certain affected businesses.
Because this schedule reflects the information available as of 2026-10-08, the most reliable approach is to check your business-specific assessment details and payment deadline through the NTS Hometax system before making a payment.
※ This article is provided for reference to help readers understand market trends and does not constitute an investment recommendation for any particular stock or asset. All final investment decisions and associated responsibilities rest with the individual investor.