

2026-10-26 Small Business Direct Loans: Differences in Eligibility and Required Documents for the Special Restart Fund and Temporary Management Hardship Fund
Applications for direct loans under the Special Restart Fund and Temporary Management Hardship Fund are scheduled to open at 10 a.m. on Monday, 2026-10-26. For the Temporary Management Hardship Fund, applicants should first check the revenue, business operating period, and financial hardship requirements. For the Special Restart Fund, they should review their business restart history, debt restructuring status, and participation in business recovery programs. The two funds have different eligibility criteria and documentation requirements.
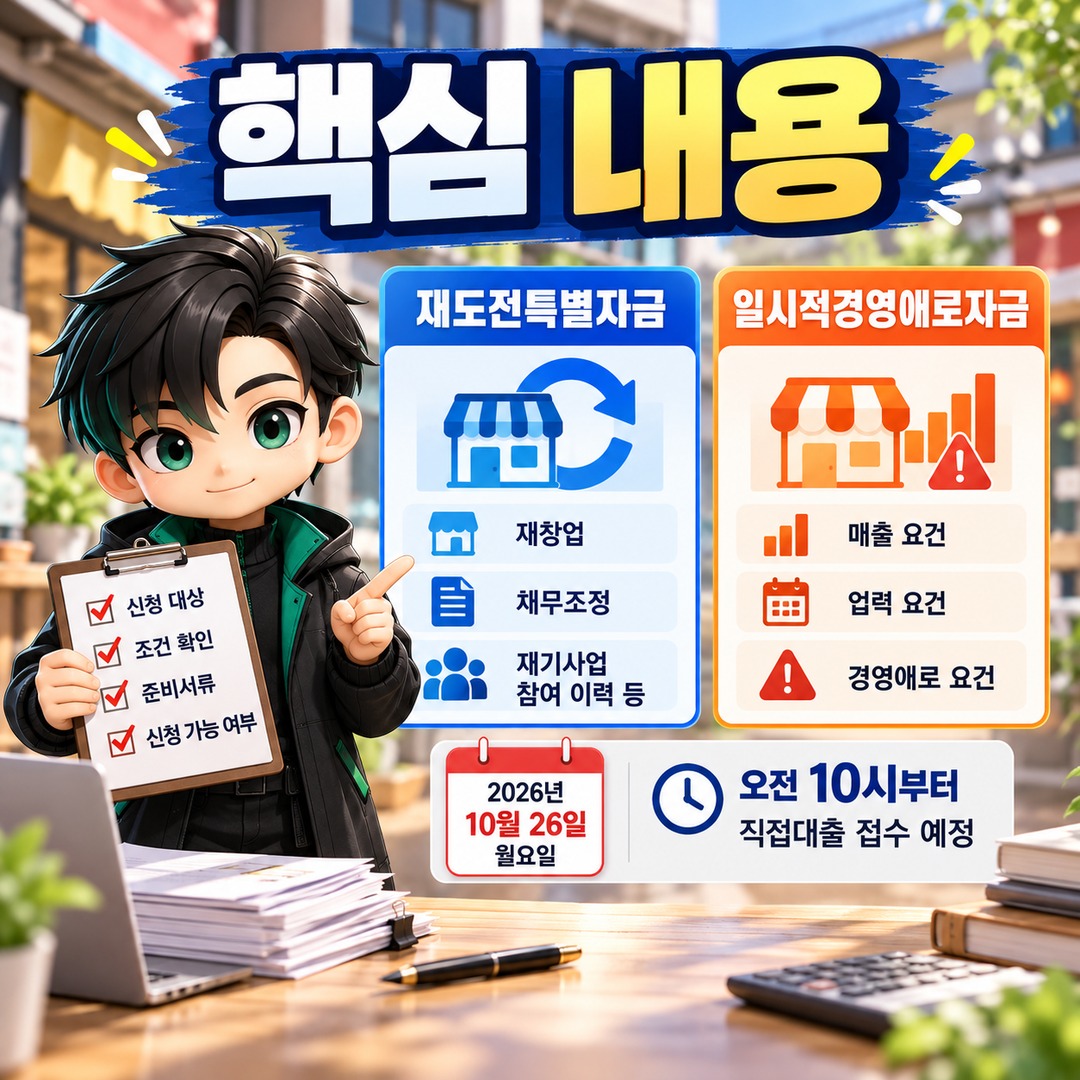
According to the guidance confirmed as of October 24, applications for both funds will remain open until their respective budgets are exhausted. However, applicants should check the Korea SMEs and Startups Agency for Market Promotion's fund-specific guidance again on the application date to confirm whether applications are being accepted and which supporting documents are required.
October 26 Direct Loans: How Do the Eligibility Requirements Differ Between the Two Funds?
The Special Restart Fund is intended for small business owners preparing to restart or recover their businesses, while the Temporary Management Hardship Fund targets small business owners experiencing operational difficulties who meet specified revenue and business operating period requirements.
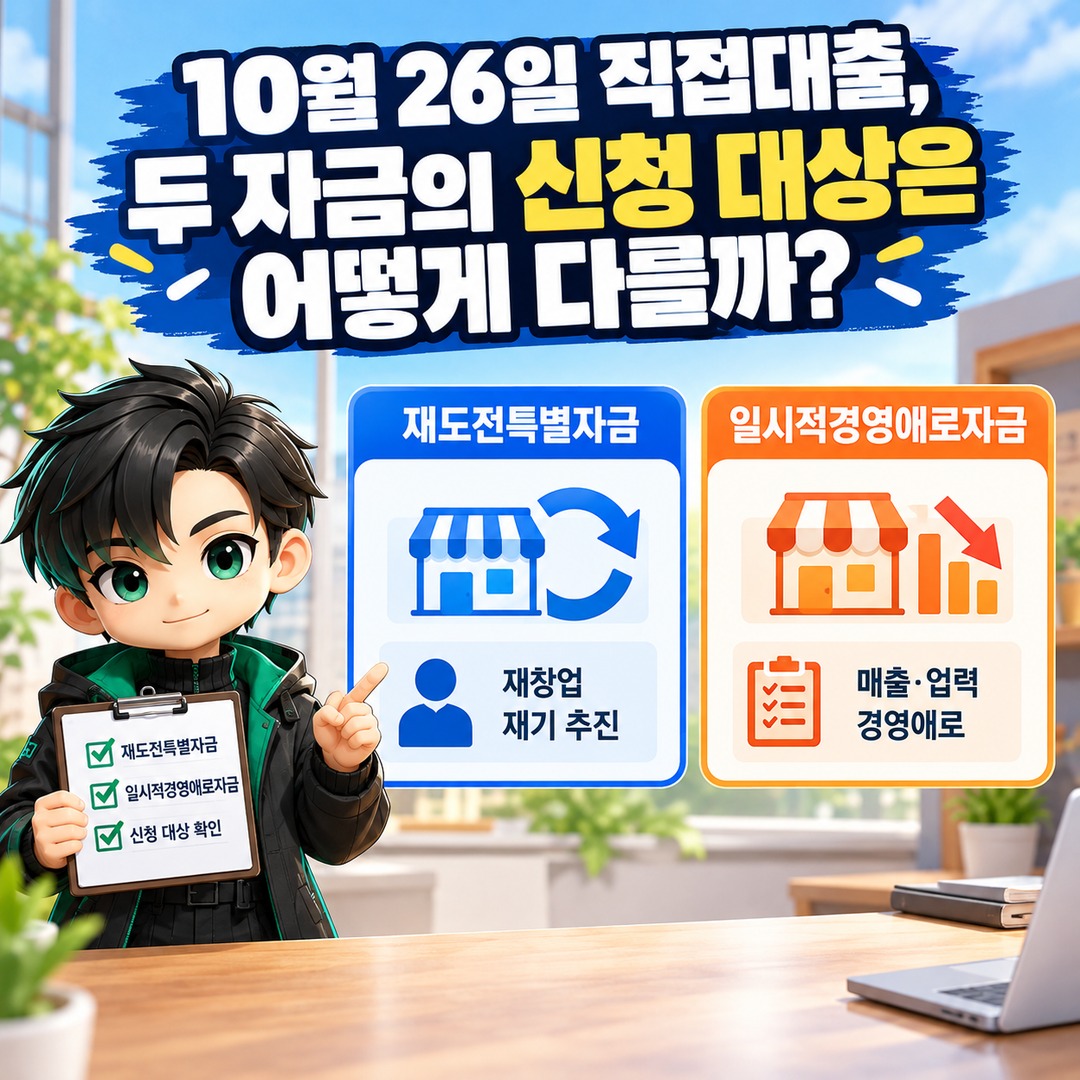
Both funds are offered as direct loans, with applications reviewed directly by the Small Enterprise and Market Service (SEMAS).
| Category | Special Restart Fund | Temporary Management Hardship Fund |
|---|---|---|
| Primary applicants | Small business owners restarting or recovering their businesses | Small business owners experiencing temporary management difficulties |
| Detailed categories | General, Hope, and Leap types | Revenue, business operating period, and management hardship requirements |
| Loan limit | Up to 7 thousand to KRW 200,000,000, depending on the category | Up to 7 thousand won |
| Loan term | 5 years, including a 2-year grace period | 5 years, including a 2-year grace period |
| Scheduled application opening | October 26 at 10 a.m. | October 26 at 10 a.m. |
The loan limit represents the maximum amount an applicant may request, not the amount that will necessarily be disbursed. After an application is submitted, eligibility checks and loan screening determine whether financing will be approved and how much can actually be borrowed.
How Much Must Revenue Decline to Qualify for the Temporary Management Hardship Fund?
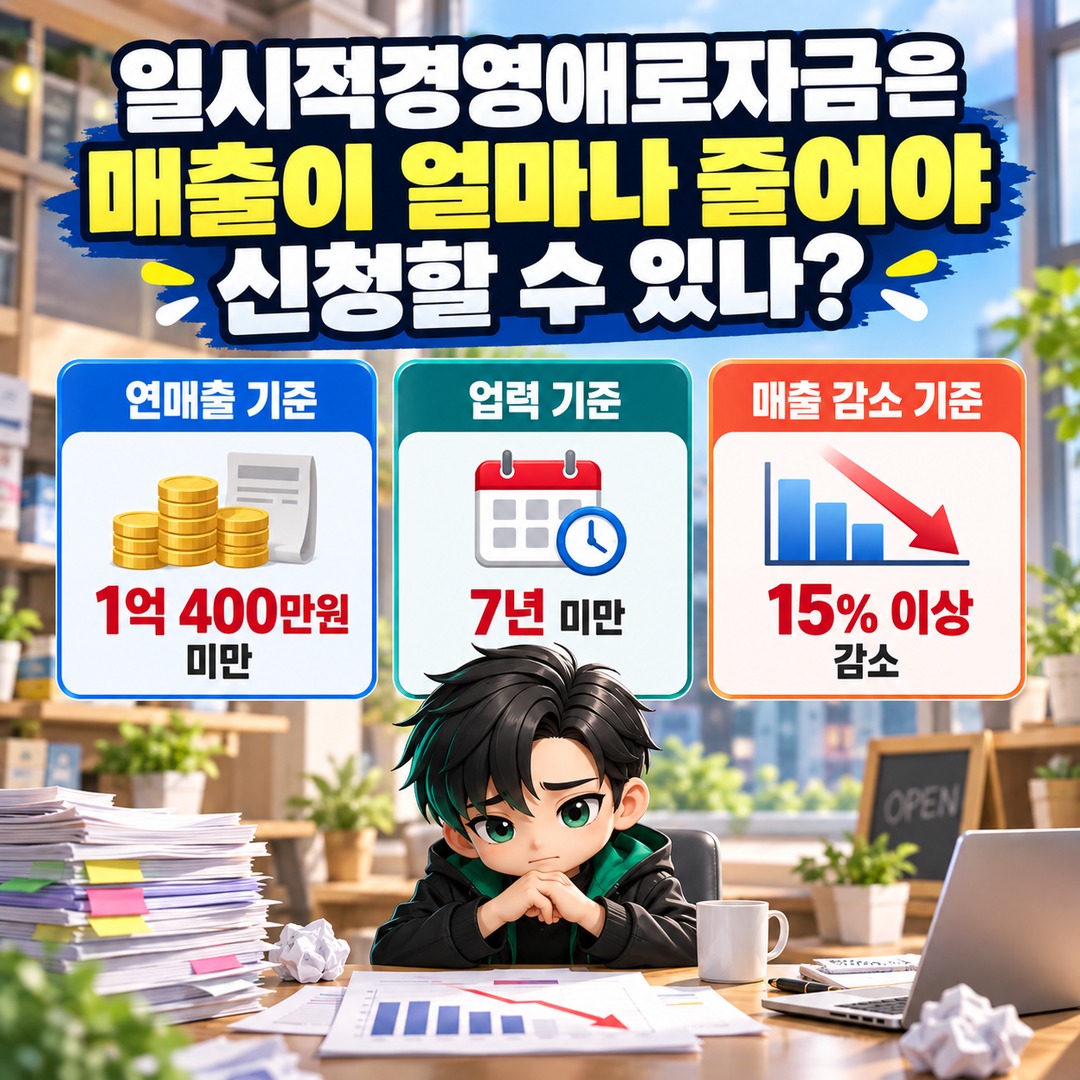
The main requirements specified in the October direct loan guidance are annual revenue below KRW 104,000,000, a business operating period of less than 7 years, and a revenue decline of at least 15%.
Revenue declines are assessed by comparing the most recent period with an earlier corresponding period. The guidance provides for comparisons by year, half-year, quarter, or month.
For example, if revenue in the earlier comparison period was KRW 50,000,000 and revenue in the most recent period was KRW 42,000,000, the decrease would be KRW 8,000,000.
The revenue decline rate is calculated as follows:
(KRW 50,000,000 - KRW 42,000,000) ÷ KRW 50,000,000 × 100 = 16%
In this example, the revenue decline rate is 16%, meeting the 15% decline threshold. However, meeting the revenue decline threshold alone does not establish loan eligibility.
Applicants must also satisfy the annual revenue and business operating period requirements. They must confirm which comparison periods and supporting evidence are officially accepted.
In particular, the annual revenue requirement is stated as 'less than' KRW 104,000,000, not 'less than or equal to' that amount. A business with annual revenue of exactly KRW 104,000,000 does not meet this requirement.
Similarly, because the business operating period must be less than 7 years, applicants should verify their business registration date and actual operating history.
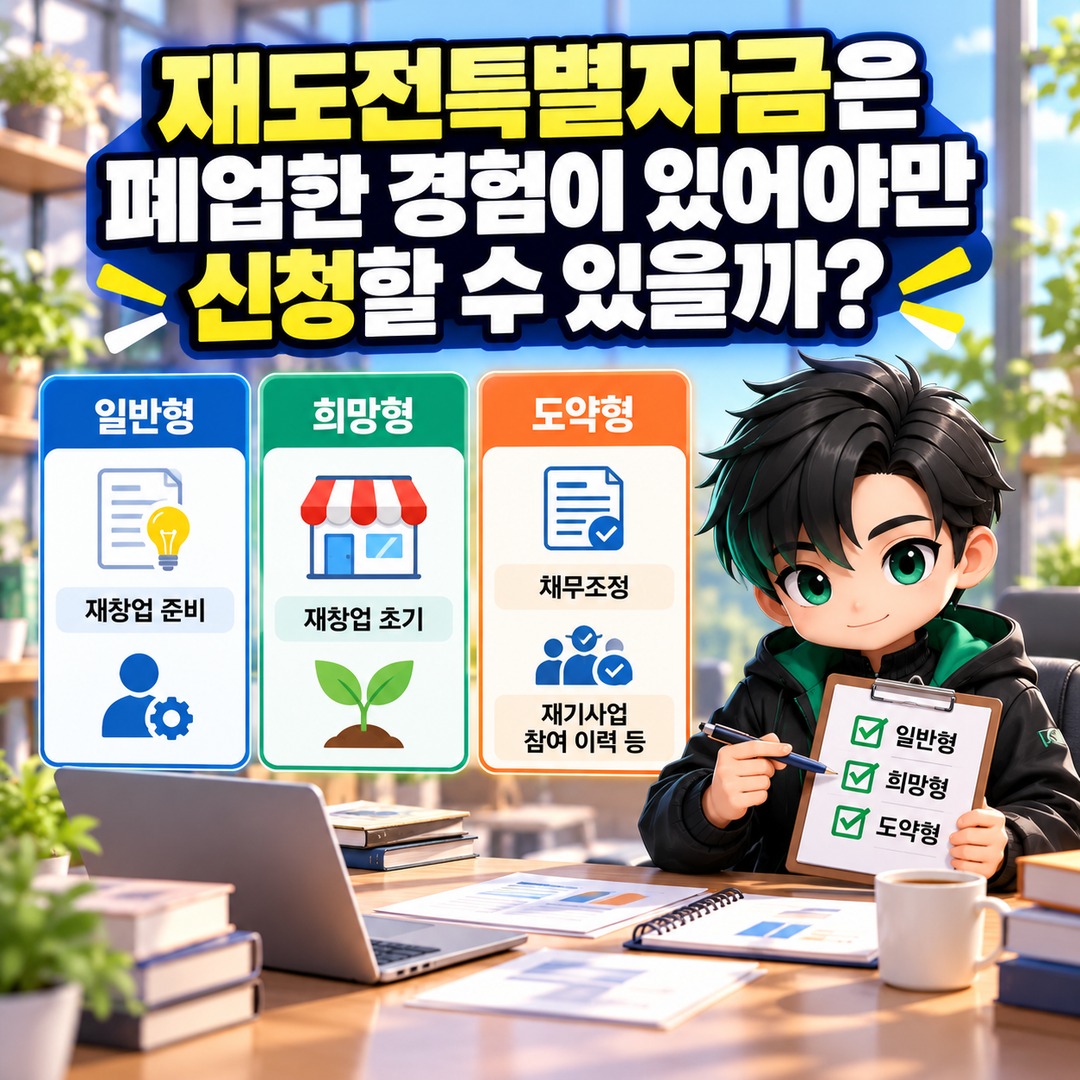
Is a Previous Business Closure Required to Apply for the Special Restart Fund?
The Special Restart Fund is divided into General, Hope, and Leap types. Depending on the type, eligibility requirements may relate to preparations for restarting a business, the early stages of a business restart, debt restructuring, or participation in business recovery programs.
The General type includes applicants preparing to restart a business, those in the early stages of restarting, and certain applicants involved in debt restructuring. Therefore, rather than determining eligibility solely on the basis of a previous business closure, applicants should identify which specific category applies to them.
The Hope type is intended for small business owners who completed a business recovery program under the 2025 Hope Return Package or who were selected for a business recovery commercialization support program in 2026 and completed the required agreement.
The Leap type targets small business owners who have operated a restarted business for a specified period and meet business growth and responsible loan repayment requirements. The stated minimum operating period following a business restart is 2 years.
Because loan limits and detailed eligibility requirements differ by type, business owners considering the Special Restart Fund should first identify their business restart history and previous participation in relevant support programs.
Which Documents Should Applicants Prepare Before Applying?
It is useful to separate the required documentation into general business identification materials and evidence establishing eligibility for the specific fund.
However, the guidance reviewed for the October 26 application round does not establish a complete, definitive list of all required documents. The materials below are items to check before applying, not a list of documents that every applicant must submit.
Applicants preparing for the Temporary Management Hardship Fund should review their business registration information, opening date, records establishing annual revenue, and documents demonstrating a decline in revenue.
In particular, calculating the revenue decline rate requires evidence of revenue for both comparison periods. Applicants should follow the detailed guidance for the relevant application round to determine which value-added tax sales records or tax documents are accepted.
Applicants preparing for the Special Restart Fund should first identify their application type and then determine which documents can substantiate the relevant eligibility history.
For those preparing to restart a business, training records are a key consideration. For applicants in the early stages of restarting, business operating history is important. For debt restructuring applicants, relevant debt restructuring records are a primary consideration.
Hope-type applicants should verify whether they completed a business recovery program under the Hope Return Package or entered into the required agreement for a business recovery commercialization support program.
Leap-type applicants may need documents relating to the operating period of their restarted business, business growth requirements, and their record of responsible repayment of policy loans.
The actual application process also includes consent procedures for the provision of personal information and corporate credit information, as well as the entry of business details. SEMAS states that information relating to revenue, taxes, debt, and credit may be reviewed during loan screening.
Where Can Applications Be Submitted Online?
The online application portal for both funds is the Small Business Policy Funds website operated by the Small Enterprise and Market Service (SEMAS).
The guidance also describes an in-person application option through the relevant regional SEMAS center.
To apply online, applicants should first confirm that applications are open for their chosen fund and then proceed to the direct loan application process.
The application process may include selecting a fund, entering applicant and business information, completing a self-assessment, providing consent, and submitting documents.
The policy fund application website's user guidance also describes certain steps subject to time limits while completing an application. Preparing basic information in advance may therefore be helpful.
In addition, submitting a direct loan application does not mean the loan will be disbursed immediately. Approval depends on eligibility and the outcome of the loan screening process.
Are Temporary Management Hardship Fund Agency Loans and Direct Loans Opening on 26 the Same Application Round?
Even when the same fund name appears, agency-mediated loans and direct loans must be distinguished by their application channels and detailed eligibility conditions.
In the 4 quarter of 2026, the announced schedule indicated that applications for agency-mediated loans under the Temporary Management Hardship Fund would open on October 6, while direct loan applications would open on October 26.
Therefore, business owners who previously reviewed the agency-mediated loan announcement must separately verify the annual revenue, business operating period, and management hardship requirements for the October 26 direct loan application round.
Applicants should not assume that the documents or conditions used in a previous application round automatically apply to the current direct loan program.
What Should Applicants Check First Before Applications Open on October 26?
Small business owners planning to apply for the Temporary Management Hardship Fund should first check the annual revenue and business operating period requirements, then calculate their revenue decline rate using the relevant comparison periods.
Those considering the Special Restart Fund should first determine whether they qualify under the General, Hope, or Leap type.
Applicants for both funds should also review industry-specific restrictions on policy fund support. Certain industries, including finance, insurance, and some real estate businesses, are excluded from small business policy fund support, although exceptions may apply depending on the industry.
Finally, the scheduled opening of applications at 10 a.m. on October 26 is separate from whether a loan will ultimately be approved. Applicants should check the application status, detailed eligibility requirements, and document submission instructions on the Small Business Policy Funds website on the application date before proceeding.