

2026 Year-End Tax Settlement: Can Dual-Income Couples Combine Credit Card Spending Under One Spouse? Family Card and Income Deduction Rules Explained
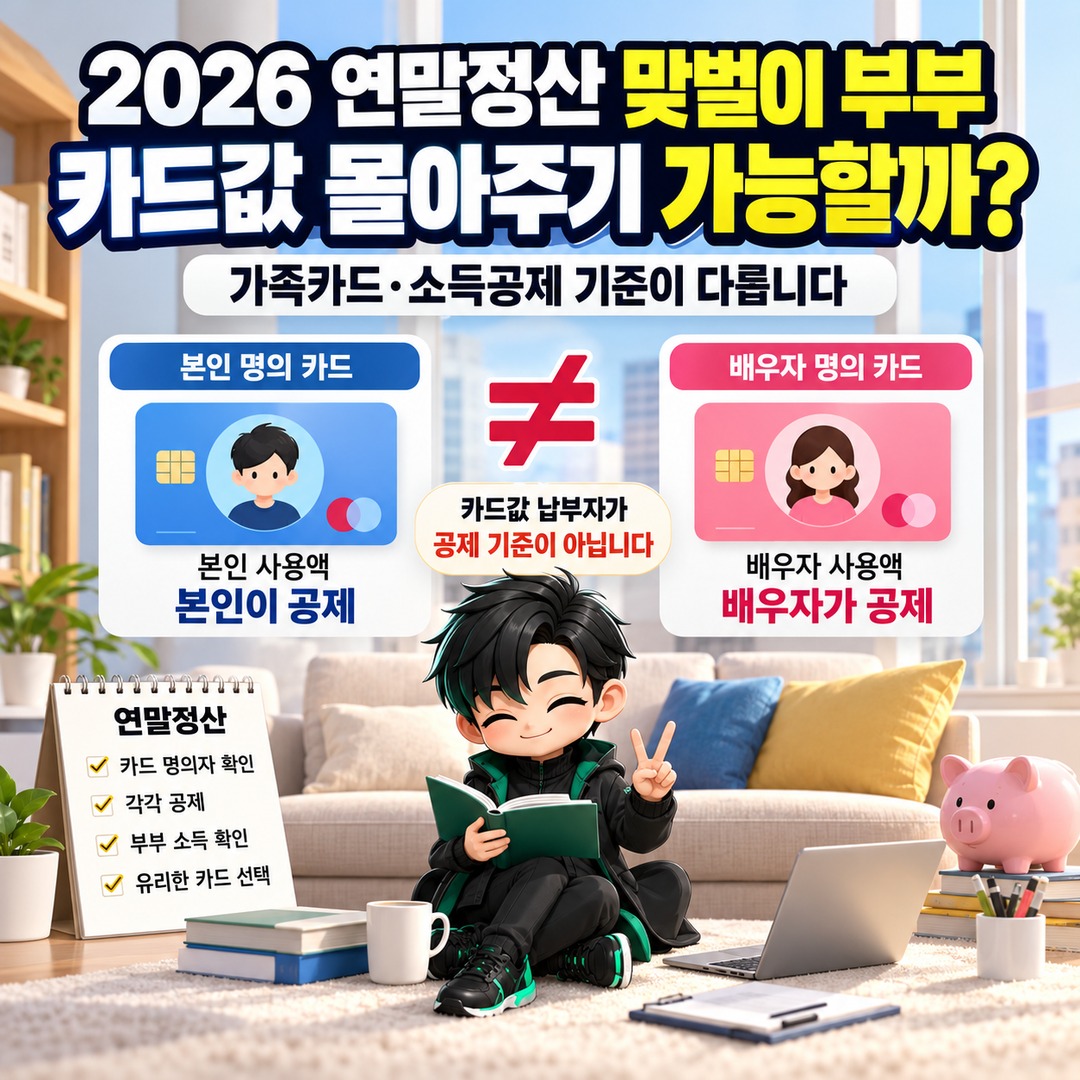
For the 2026 tax year, dual-income couples cannot freely allocate their credit card spending to whichever spouse they prefer. Even when a family card is used, deductions are generally attributed to the actual cardholder named on the card. The bank account used to pay the credit card bill does not determine who can claim the deduction.
However, when choosing which cards to use for future purchases, couples can compare their gross salaries and card spending to determine the more advantageous option.
In particular, the credit card income deduction applies only to eligible spending exceeding 25% of gross salary. Therefore, concentrating all spending under the lower-earning spouse is not necessarily the best strategy.
*Information verified as of 2026-10-19 / Year-end tax settlement for employment income attributable to 2026*
1. Can Dual-Income Couples Combine Their Card Spending Under One Spouse?
If both spouses earn employment income and neither qualifies as an eligible dependent for income deduction purposes, one spouse cannot include the other's credit card spending in their own year-end tax settlement.
This remains true even if the couple shares household expenses or one spouse pays all the credit card bills.
For example, suppose the husband uses a card issued in his name to pay KRW 10,000,000 in household expenses, while the wife pays the bill from her bank account.
In principle, the card spending is attributed to the husband. The wife cannot include it in her credit card income deduction simply because she paid the bill.
The National Tax Service (NTS) also explains in its year-end tax settlement guidance that family card deductions are based on the card user, not the person paying the bill.
However, a separate assessment is necessary if a spouse meets the income eligibility requirements. The term 'dual-income couple' does not automatically mean that identical rules apply to every household.
2. Which Spouse Can Claim a Family Card Deduction?
For family cards, it is important to distinguish between the person responsible for the card bill and the person whose name appears on the card as its user.
For example, suppose a husband obtains a credit card in his own name and has an additional family card issued in his wife's name.
| Spending situation | Spouse entitled to the card income deduction |
|---|---|
| Husband uses his own card | Husband |
| Wife uses a family card issued in her name | Wife |
| Wife pays the husband's credit card bill | Husband |
| Husband pays the bill for the wife's family card | Wife |
The table describes a typical dual-income household in which both spouses have income and cannot combine each other's card spending for deduction purposes.
The key point is that spending on family cards is not automatically included in the year-end tax settlement of the primary cardholder.
When reviewing year-end tax settlement records, check spending by individual card user before looking at which bank account was charged.
3. The 25% Gross Salary Threshold: Which Spouse Crosses It First Matters
The credit card income deduction is calculated based on eligible spending exceeding 25% of gross salary.
For spouses with different gross salaries, the spending threshold at which deductions begin will also differ.
For example, suppose the husband's gross annual salary is KRW 60,000,000 and the wife's is KRW 40,000,000.
| Category | Husband | Wife |
|---|---|---|
| Annual gross salary | KRW 60,000,000 | KRW 40,000,000 |
| 25% of gross salary | KRW 15,000,000 | KRW 10,000,000 |
| Assumed annual card spending | KRW 12,000,000 | KRW 12,000,000 |
| Spending exceeding the 25% threshold | KRW 0 | KRW 2,000,000 |
*Author's calculation: Gross salary × 25%, assuming all eligible spending consists of ordinary credit card purchases.*
Even though the husband spends KRW 12,000,000 on his card, that amount is below 25% of his gross salary. Therefore, he receives no credit card income deduction in this example.
By contrast, the wife's KRW 2,000,000 in spending above KRW 10,000,000 qualifies for the deduction calculation.
Applying the ordinary credit card deduction rate of 15% gives the following result:
KRW 2,000,000 × 15% = KRW 300,000 income deduction
The KRW 300,000 is not the amount of tax refunded. It is the amount deducted from income subject to taxation.
The actual tax savings depend on the individual's taxable income, applicable tax rate, and other deductions.
This is also a simplified example involving only ordinary credit card spending. Actual year-end tax settlements apply different deduction rates and limits depending on spending categories.
4. Is Concentrating Card Spending Under the Lower-Earning Spouse Always Better?
Not necessarily.
A spouse with a lower gross salary generally has a lower 25% threshold. However, if that spouse has already reached the applicable credit card income deduction limit, additional spending may provide little or no further benefit.
Conversely, although a higher-earning spouse has a higher deduction threshold, the tax savings from the same income deduction may be greater depending on the applicable tax rate.
Therefore, couples should compare three factors:
Deduction threshold: Has each spouse exceeded 25% of their respective gross salary?
Deduction limit: Has either spouse already reached the applicable income deduction limit?
Actual tax savings: How much would the tax liability decrease if the income deduction increased?
One particularly important point is that card spending already incurred cannot be transferred to the other spouse at year-end.
Couples can use this information to choose payment methods for the remainder of the year, but they cannot arbitrarily change which spouse is entitled to deductions for past purchases.
Additionally, making unnecessary purchases solely to increase credit card deductions may result in additional spending that exceeds the tax savings.
5. Can Card Spending Be Combined If One Spouse Has Very Little Income?
If a spouse's annual income amount is KRW 1,000,000 or less, or their gross salary is KRW 5,000,000 or less when they have only employment income, it may be possible to consider including that spouse's credit card spending in the other spouse's deduction.
The important factor is not simply whether the spouse earns a low monthly salary, but whether they satisfy the income requirements established by law.
For example, if a spouse worked for only part of the year, their total annual gross salary must be checked. If they have business income or other income in addition to employment income, the income eligibility requirements must be assessed separately.
Furthermore, although the age requirement for dependents does not apply to the credit card income deduction, the income requirement must still be verified.
Including Card Spending by a Dual-Income Spouse Who Does Not Meet the Income Requirements May Result in an Excessive Deduction.
In its guidance on excessive year-end tax deductions, the National Tax Service warns taxpayers not to claim credit card spending by family members whose income exceeds the applicable threshold.
6. How to Check Both Spouses' Card Spending on Hometax
When preparing for the 2026 year-end tax settlement, the starting point is for each spouse to check spending on cards issued in their own name.
Follow these steps:
1. Visit <Link url="https://www.hometax.go.kr" title="National Tax Service Hometax"/> and sign in to your own account.
2. Find the function for checking credit card and other eligible spending amounts in the year-end tax settlement menu.
3. Separate spending on credit cards, debit cards, and cash receipts issued in your name.
4. Have your spouse check the same information using their own account.
5. Calculate 25% of each spouse's gross salary and compare it with their current eligible spending.
6. Check whether family card transactions are recorded under the correct individual card users.
The year-end tax settlement preview and simplified tax settlement services may have different availability dates and coverage. As of 2026-10-19, check the latest Hometax announcements to confirm whether the relevant services are available and how their menus are organized.
Also, not every card transaction displayed on Hometax necessarily qualifies for an income deduction.
For example, taxes, certain utility charges, insurance premiums, and new vehicle purchases may be excluded. Separate rules allow 10% of the purchase price of a used vehicle to be included in eligible spending when certain conditions are met.
Therefore, a difference between the amount shown in a card issuer's transaction records and the amount eligible for year-end tax deductions does not automatically indicate an error.
7. Three Things Couples Should Check Before Year-End
If you are planning card spending for the remainder of 2026, start by reviewing the following items.
First, Check Each Spouse's Gross Salary.
The 25% threshold must be calculated using gross salary after excluding tax-exempt employment income and similar items, rather than the annual salary stated in an employment contract.
Second, Separate Card Spending Already Incurred.
Credit cards, debit cards, and cash receipts have different deduction rates for ordinary spending.
According to the National Tax Service's 2026 guidance, ordinary credit card spending qualifies for a deduction rate of 15%, while debit card and cash receipt spending qualifies for 30%. However, special rules for spending at traditional markets and other designated locations must be checked separately.
Third, Compare Which Spouse Should Make Remaining Purchases.
Even if one spouse has already crossed the deduction threshold, the applicable deduction limit and actual tax savings must also be considered.
Calculating each spouse's potential deduction is more accurate than simply concentrating all card spending under one person.
8. Frequently Asked Questions
Q. If the Husband Pays With a Card in His Name and the Wife Transfers Him the Money, Can the Wife Claim the Deduction?
In principle, no. Card spending is attributed based on the named cardholder. The fact that the other spouse transfers money for household expenses or pays the card bill does not change who is entitled to the deduction.
Q. Can Both Spouses in a Dual-Income Household Claim Deductions for Their Child's Card Spending?
Both spouses cannot claim duplicate deductions for the same child's card spending. Generally, the employee who claims the basic dependent deduction for a child meeting the relevant income and other eligibility requirements also claims the child's credit card spending deduction.
Q. Since Debit Cards Have a Higher Deduction Rate, Are They Always Better?
No. The 25% gross salary threshold, deduction limits, and benefits offered by credit cards must all be compared. Even if debit cards have a higher deduction rate, the actual tax savings may be smaller than the difference in card benefits.
Conclusion: Check Card Ownership and Gross Salary Before Focusing on Who Pays the Bill
One of the most common misunderstandings in year-end tax settlements for dual-income couples is assuming that the person who pays household expenses is automatically the person entitled to claim the corresponding card spending deduction.
However, these are two different considerations.
Card Spending Already Incurred Is Generally Attributed to the Named Cardholder, While Future Spending Decisions Should Be Based on Each Spouse's 25% Gross Salary Threshold and Deduction Limits.
In particular, when preparing for the 2026 year-end tax settlement, it is more useful to check each spouse's potential deduction now than to attempt to combine spending at the end of the year.
※ This article is provided for reference to help readers understand market trends and does not constitute an investment recommendation for any particular security or asset. Final investment decisions and responsibility rest with the individual.