

2026 Credit-Vulnerable Small Business Loan: Why a Credit Score of 839 or Below Does Not Guarantee Approval
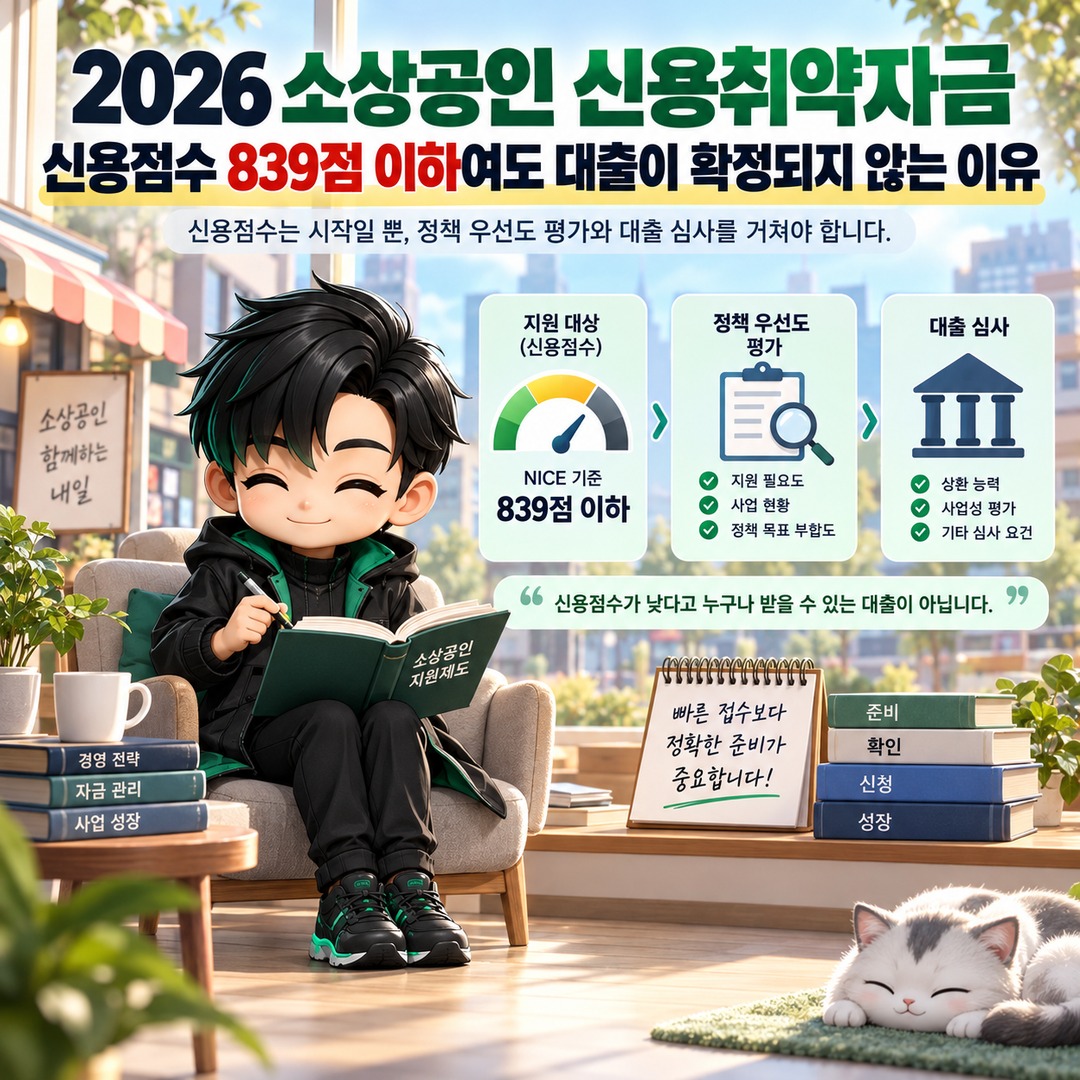
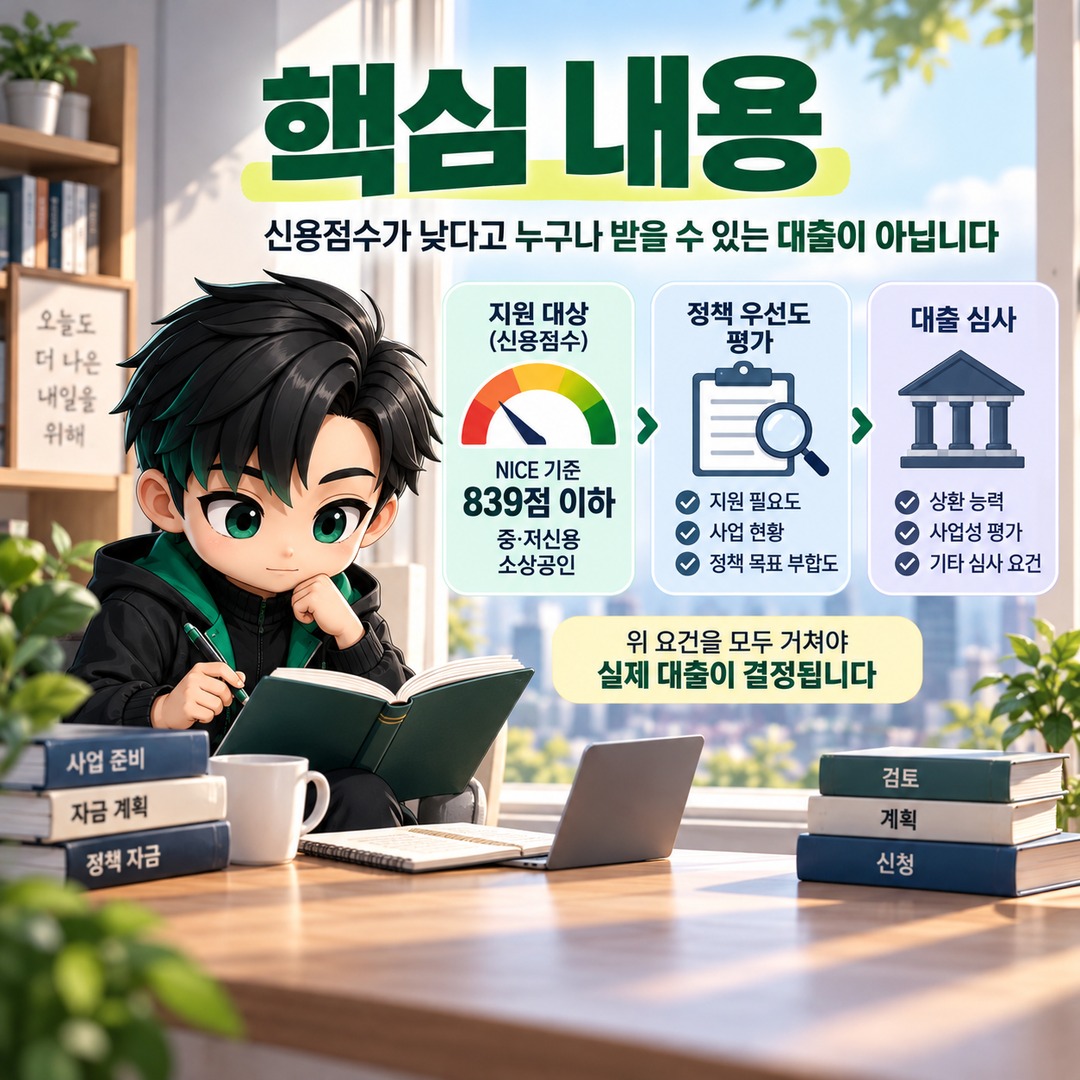
The 2026 Credit-Vulnerable Small Business Loan program does not guarantee financing to everyone with a low credit score. Small business owners with low or moderate credit ratings and a NICE credit score of 839 or below fall within the target group, but they must undergo a policy-priority assessment and loan screening before receiving financing.
In particular, the previous first-come, first-served application system has changed in 2026. Rather than simply completing an application quickly, factors such as creditworthiness, previous policy-loan assistance, business location, and years in operation now play important roles in the assessment.
Let's examine the application requirements and how the actual selection process works as of 2026-10-12.
Can Everyone With a Credit Score of 839 or Below Apply?
The Credit-Vulnerable Small Business Loan is a government-backed policy financing program designed to support small business owners with low or moderate credit ratings who have difficulty obtaining financing from private financial institutions.
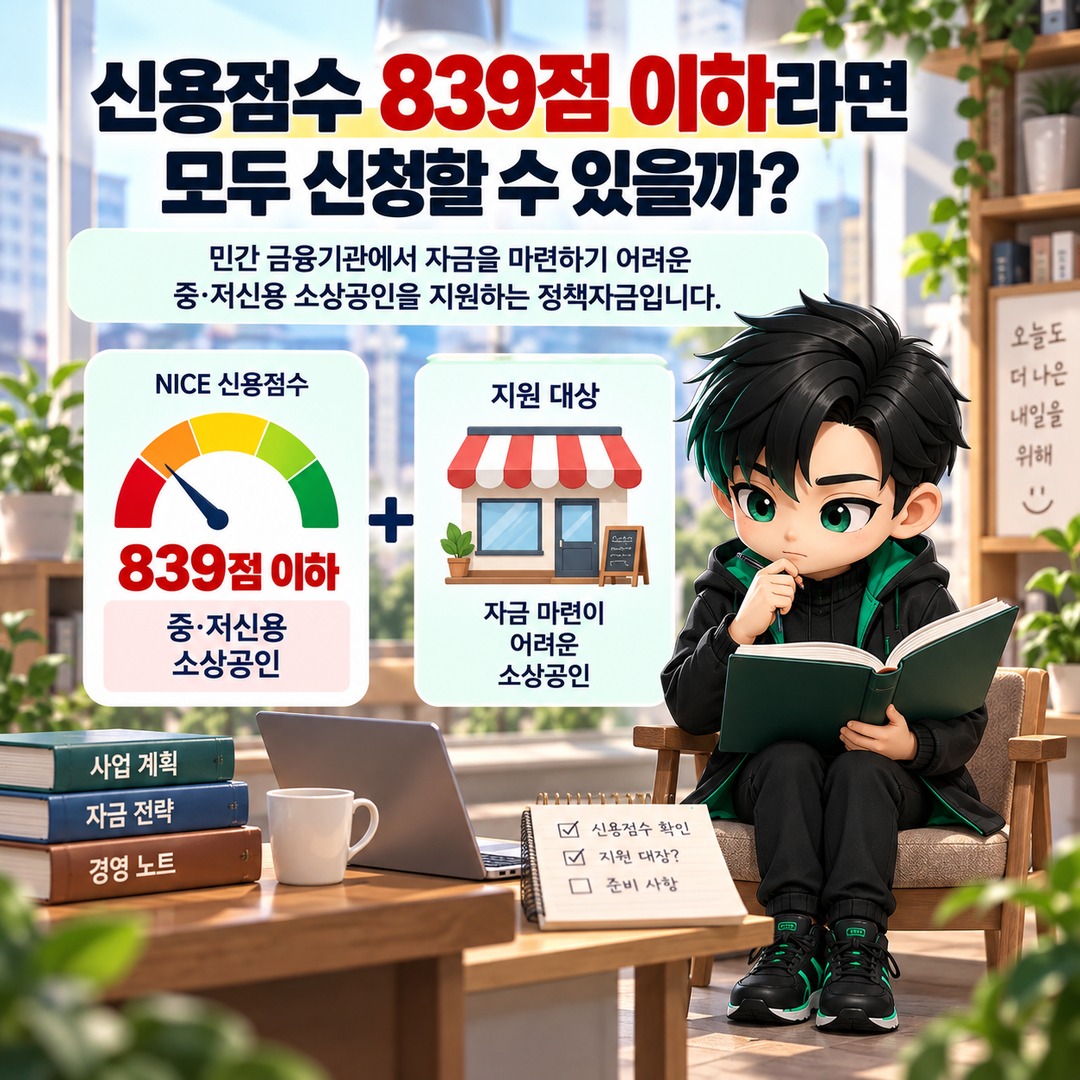
Under the criteria announced by South Korea's Ministry of SMEs and Startups on May 2026, the credit score requirement is 839 or below according to NICE credit information (NCB).
The important distinction is that meeting the credit score requirement and actually receiving a loan are two separate matters.
For example, a small business owner with a NICE credit score of 780 falls within the announced credit score range. However, that score alone does not establish that the applicant meets all eligibility requirements or will receive loan approval.
Conversely, a NICE credit score of 850 falls outside the announced threshold of 839 or below.
When checking your credit score, do not substitute a score from another credit rating agency. Make sure to check the NICE standard specified in the official announcement.
What Has Changed in the Selection Process Since 2026?
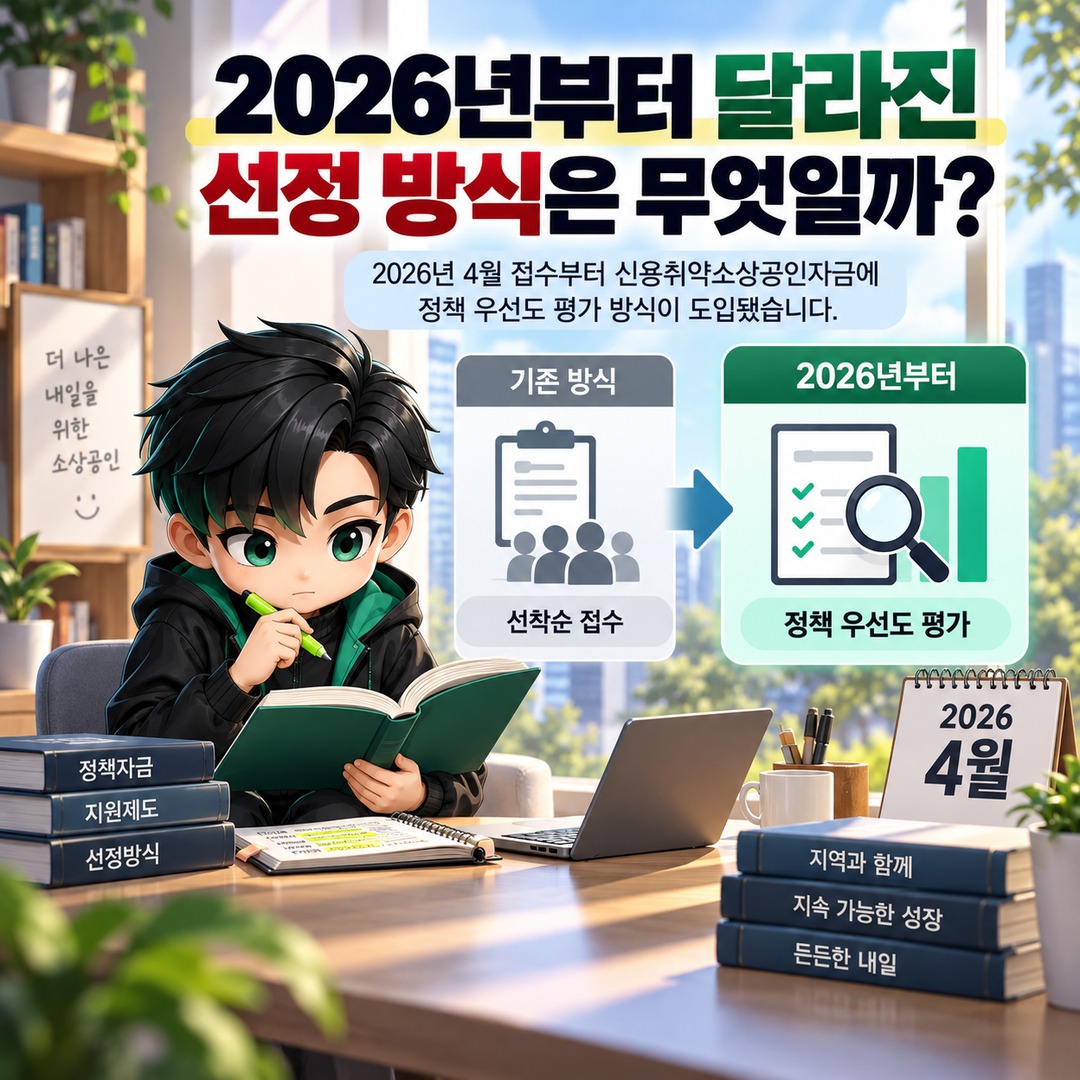
A policy-priority assessment system was introduced for the Credit-Vulnerable Small Business Loan program starting with the April 2026 application round.
Previously, applications closed once the number received reached the target volume. Under the revised system, applications are accepted during a designated period and then evaluated based on multiple factors.
The main assessment factors are as follows.
| Assessment Factor | What Is Evaluated |
|---|---|
| Creditworthiness | Applicant's credit score |
| Previous policy-loan assistance | Whether the applicant has previously received government policy financing |
| Business location | Whether the business is located outside the Seoul metropolitan area or in a population-declining region |
| Years in operation | How long the business has been operating |
Therefore, a low credit score alone is not enough to predict the selection outcome.
The location of the business, its operating history, and previous financial assistance are also considered alongside the credit score.
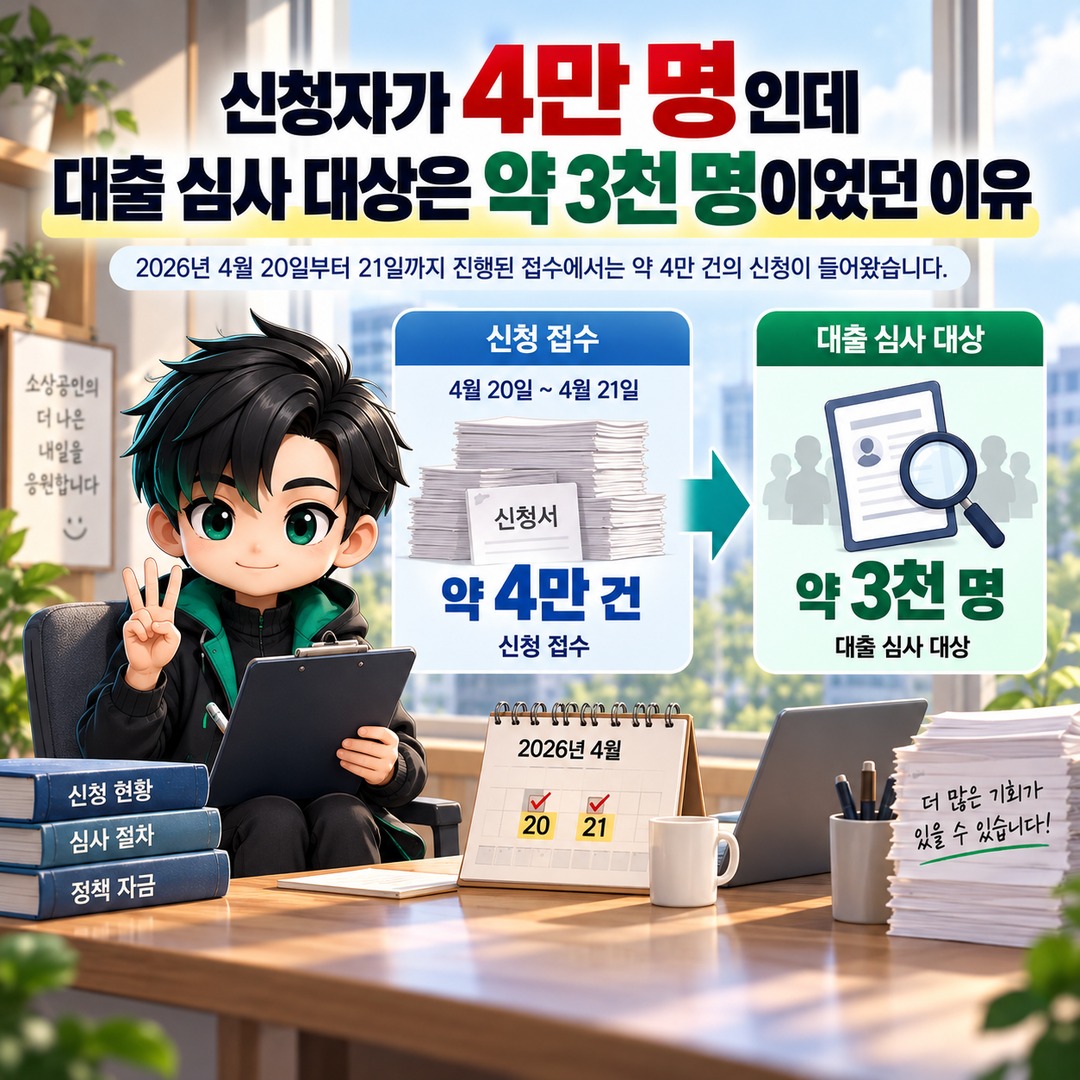
Why Were Only About 3 Thousand Applications Selected for Loan Screening Out of 4 Ten-Thousand Applicants?
Approximately 4 ten-thousand applications were submitted during the application period from 2026-04-20 through 21.
According to results released by the Ministry of SMEs and Startups on May 21, approximately 3 thousand applications were selected for loan screening.
The approximate figures can be summarized as follows.
Applications received: Approximately 4 ten-thousand
Applications selected for loan screening: Approximately 3 thousand
Share of applications selected for screening: Approximately 7.5%
7.5% is calculated using the published approximate figures and therefore does not represent an exact selection rate.
Furthermore, this figure is not the percentage of applicants who actually received loans. It represents the proportion selected for loan screening after the policy-priority assessment.
It is important to distinguish between application submission, selection for loan screening, and final loan disbursement, as these are separate stages.
Does Having an Even Lower Credit Score Improve Your Chances of Selection?
The April 2026 policy-priority assessment results showed that the share of support going to small business owners with low credit scores increased compared with the previous system.
According to the Ministry of SMEs and Startups, the share of support going to applicants with NICE credit scores of 744 or below increased by approximately 67% percentage points compared with the 1–March period, when the program operated on a first-come, first-served basis.
Differences were also observed in business location and years in operation.
| Category | April Assessment Results |
|---|---|
| Businesses located outside the Seoul metropolitan area or in population-declining regions | 77.1% of selected applicants |
| Small business owners operating for less than 3 years | 78.6% of selected applicants |
| Small business owners with no previous policy-loan assistance | 93.1% of selected applicants |
These results illustrate which groups were selected more frequently under the policy-priority assessment system.
However, they do not mean that applicants with lower credit scores are automatically selected or that meeting any one of the listed conditions guarantees a loan.
Whether an individual applicant is selected depends on the actual assessment and screening results.
What Is the Interest Rate on a Loan With a Maximum Limit of 3 Thousand Ten-Thousand Won?
The maximum loan amount under the Credit-Vulnerable Small Business Loan program announced by the Ministry of SMEs and Startups on May 2026 is 3 thousand ten-thousand won.
At the time of the announcement, the annual interest rate was 5.04%, based on the 2 quarter of 2026.
However, the maximum loan limit is not an amount automatically provided to every applicant. The actual amount available may vary depending on the screening results.
The reference period is also important when considering the interest rate.
The annual rate of 5.04% was the announced figure applicable to the 2 quarter of 2026. It should not automatically be assumed to apply to applications submitted in October 2026.
Before applying, applicants should separately verify the interest rate and loan conditions for the current application round.
How Can You Check Application Availability as of 2026-10-12?
Whether applications are currently being accepted as of 2026-10-12 must be verified through the official announcement for the relevant application round.
The April 2026 application period from 20 through 21, and the previously announced June application period scheduled from 15 through 16, cannot be used as the application schedule for October.
If you are preparing to apply, it is advisable to check the following in order.
1. Check whether applications for the Credit-Vulnerable Small Business Loan are currently open through the official small business policy financing application system.
2. Review the NICE credit score threshold and applicant eligibility requirements stated in the latest announcement.
3. Check the business location, years in operation, and previous policy-loan assistance records needed for the policy-priority assessment.
4. Verify the application period, required documents, applicable interest rate, and loan limit for the current round.
5. After submitting an application, check the policy-priority assessment results and the progress of loan screening separately.
It is particularly important not to mistake the dates and interest rates listed in previous application announcements for current application conditions.
What If You Have a Low Credit Score but Previously Received a Policy Loan?
Previous policy-loan assistance is one of the factors considered in the 2026 policy-priority assessment.
The government also announced that 93.1% of applicants selected in April 2026 were small business owners who had not previously received policy-loan assistance.
However, this figure does not mean that all small business owners who previously used policy financing are ineligible to apply.
Any actual application restrictions and screening conditions related to previous borrowing must be checked in the detailed announcement for the relevant application round.
The Credit-Vulnerable Small Business Loan program does not simply distribute funds in ascending order of credit scores.
A NICE Credit Score of 839 or Below Is Only the Starting Point; Policy-Priority Assessment and Loan Screening Are Separate Processes That Determine Whether Financing Is Provided
If you are considering applying in October 2026, it is advisable to check application availability and the detailed requirements in the latest official announcement before relying on previous interest rates or application schedules.