

Missed the 2026 Regular Earned Income Tax Credit Application? You Can Still Apply Until December 1, but Late Applications Are Reduced by 5%
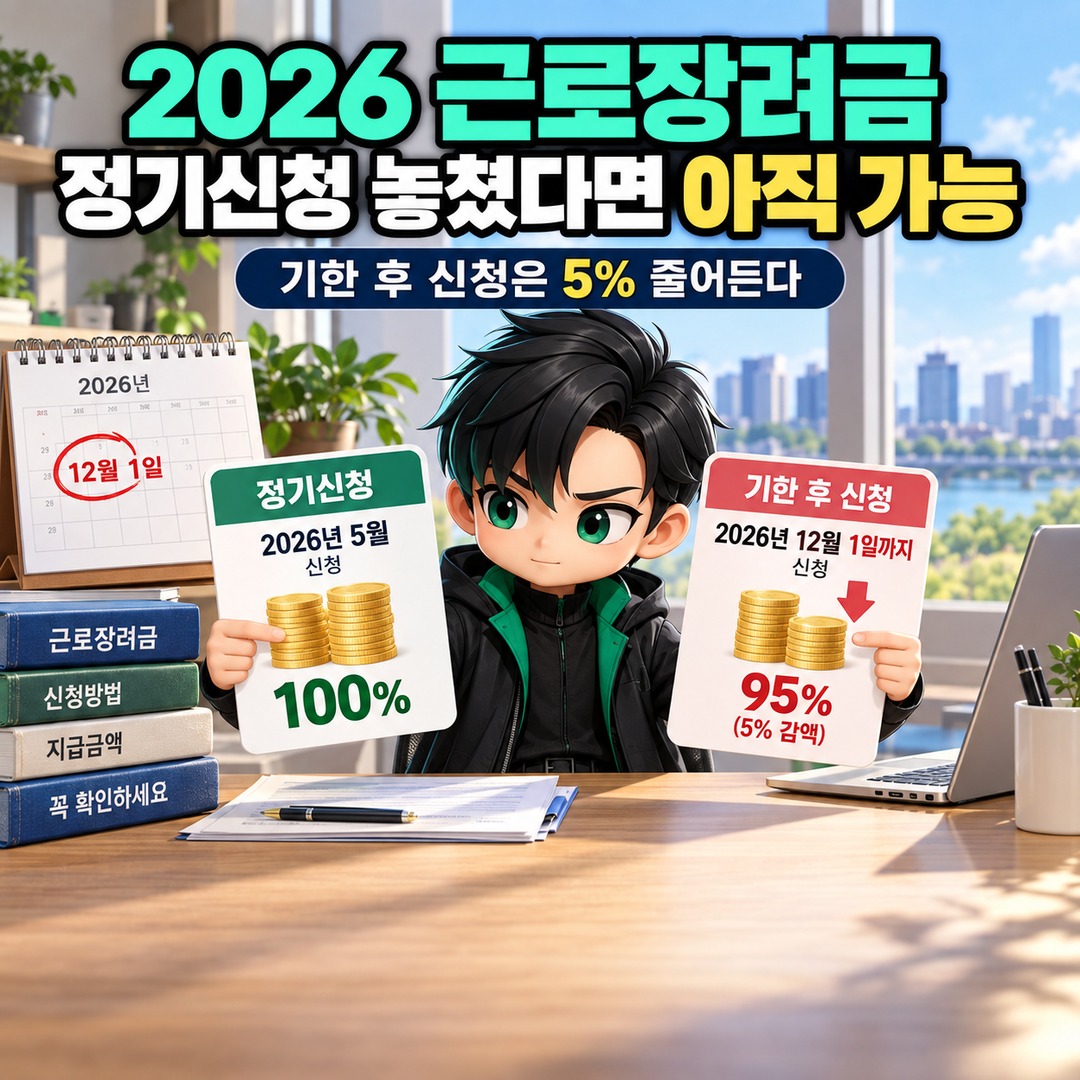
Missing the May 2026 regular application period does not mean you have lost your chance. For the earned income tax credit attributable to 2025, late applications can be submitted until 2026-12-01, and applicants receive 95% of the credit calculated after review. In other words, the payment is reduced by 5% compared with a regular application.
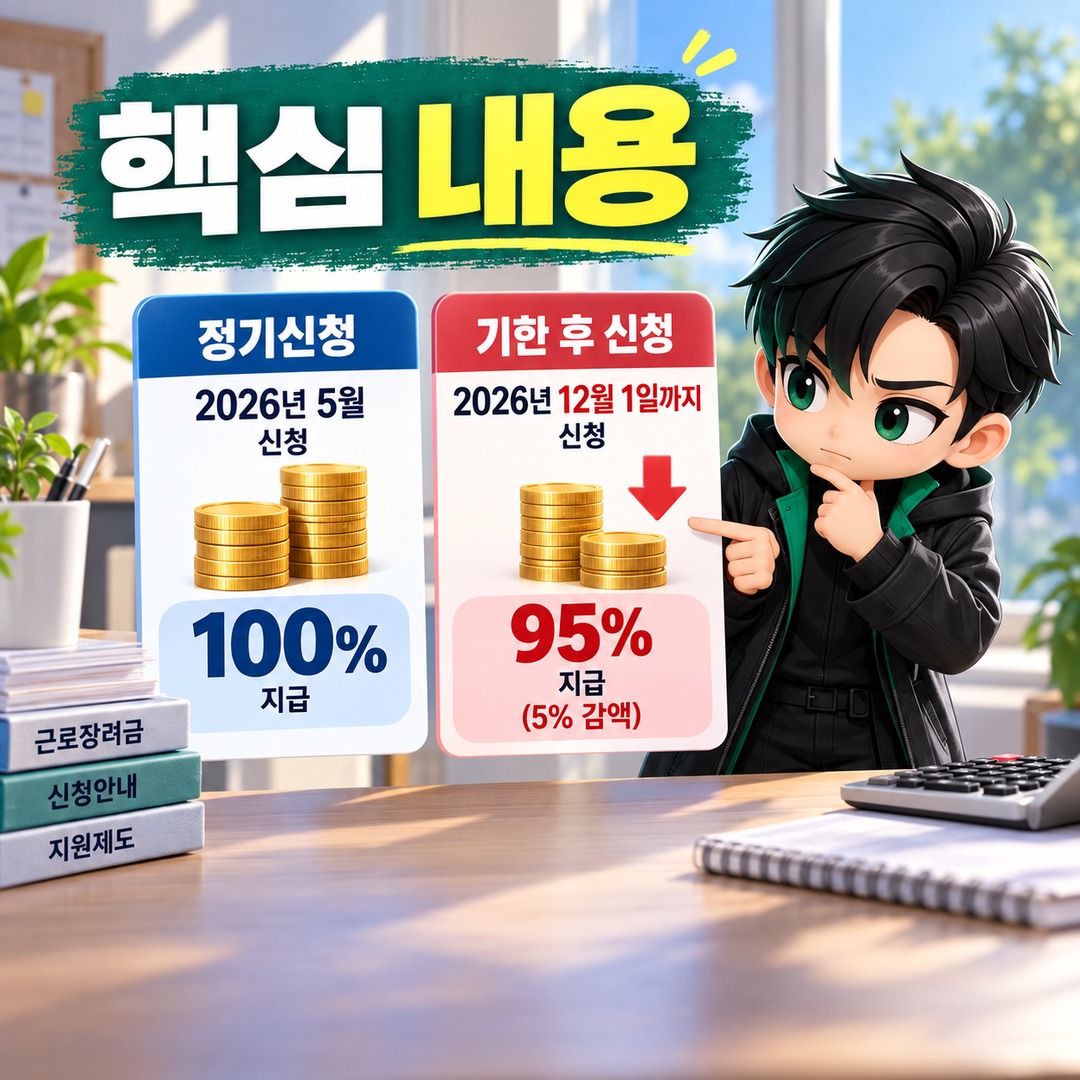
As of 2026-10-05, the important deadline is December 1, not November 30. Some online sources list November 30, but the current official guidance from the National Tax Service (NTS) explicitly states that applications are accepted until December 1.
You Can Still Apply Now Even If You Missed the May Regular Application Period
The regular application period for the earned income and child tax credits attributable to 2025 ran from 2026-05-01 to June 1.
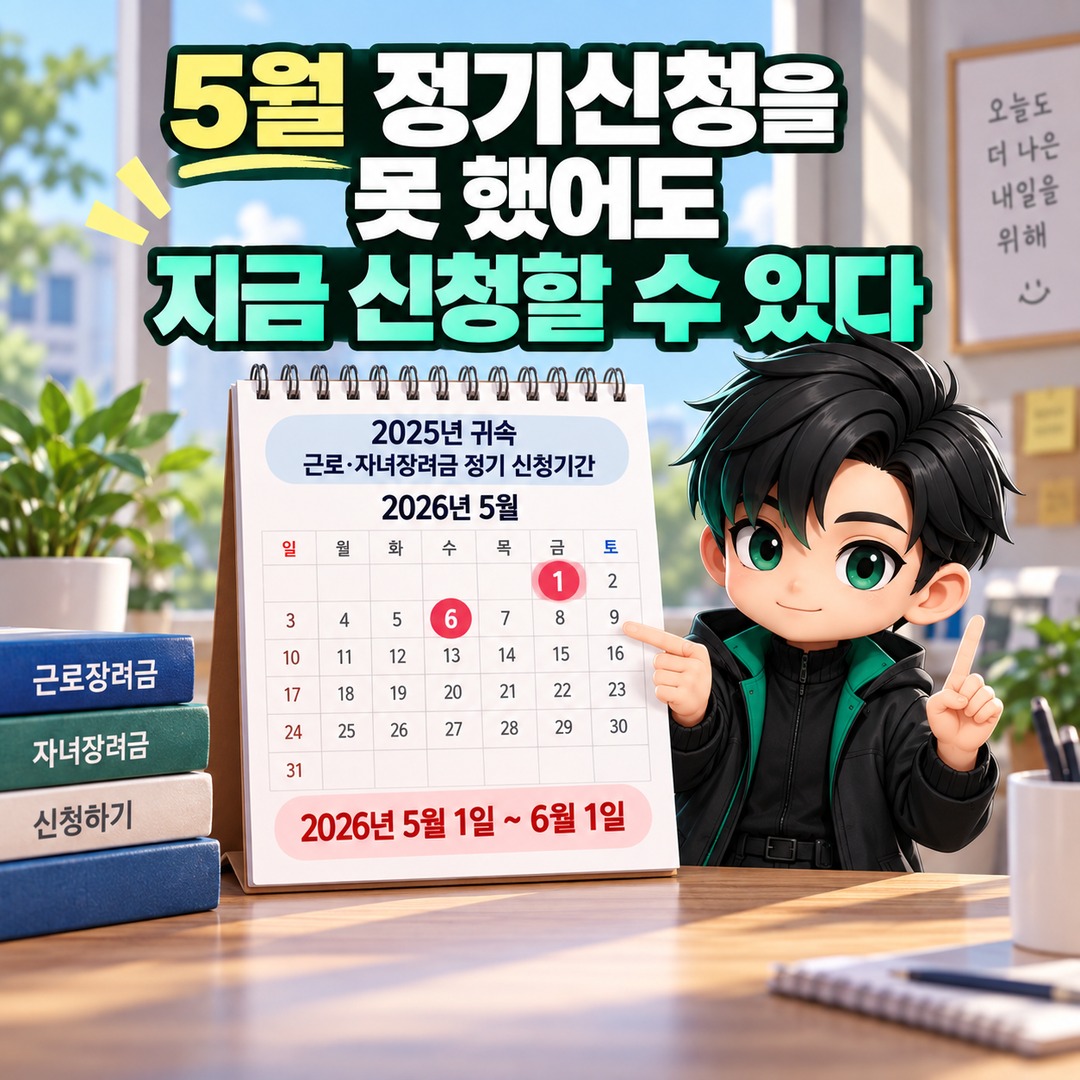
If you did not apply during that period, you can submit a late application from 2026-06-02 through December 1.
However, the payment amount differs from that of a regular application.
Applicants who applied during the regular application period receive payments based on their calculated credit amounts, while late applicants receive 95% of the calculated amount.
The reduction can therefore be calculated easily.
Late Application Payment = Calculated Credit × 95%Reduction Amount = Calculated Credit × 5%
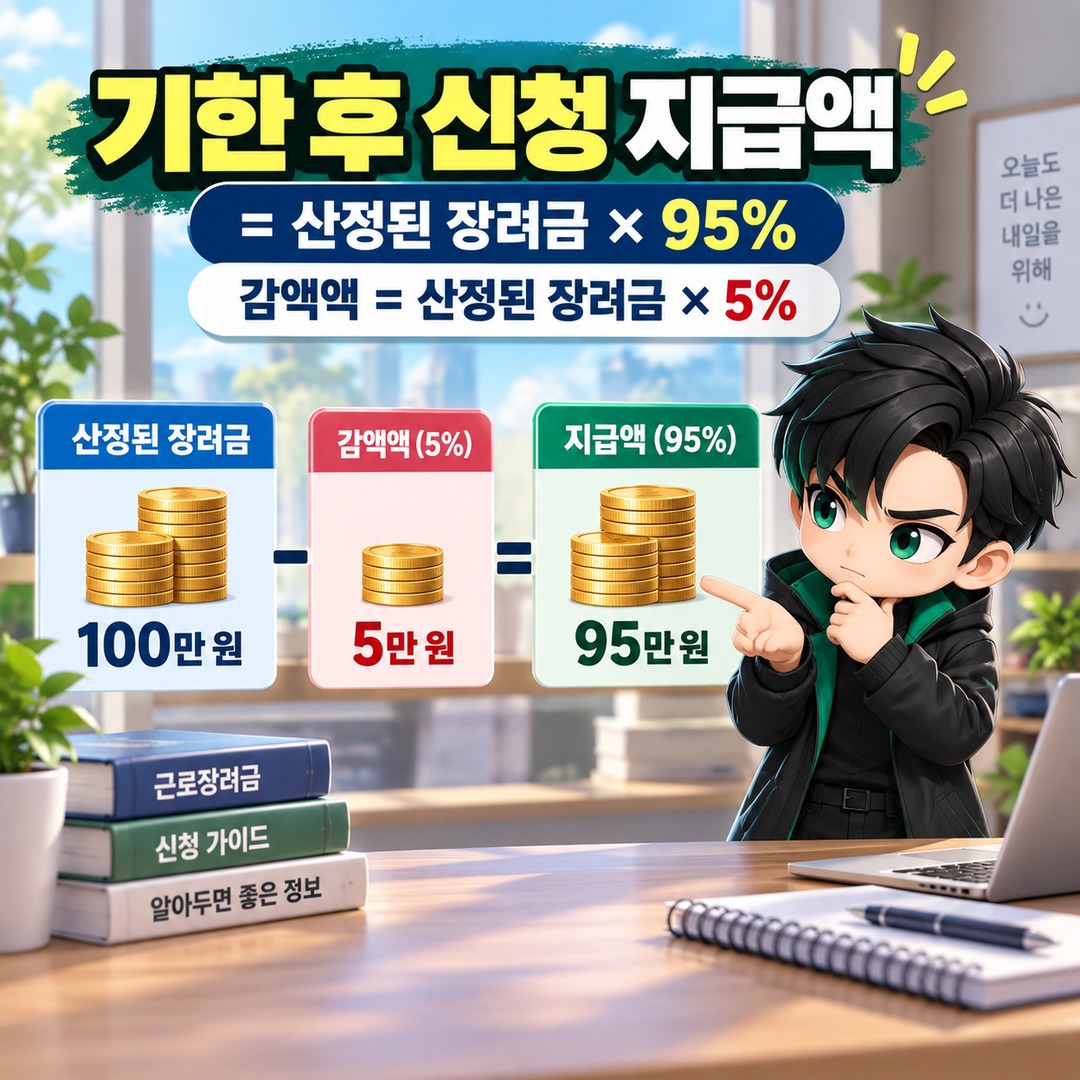
For example, if the earned income tax credit calculated after review is KRW 1,000,000, the amount is reduced by KRW 50,000, leaving KRW 950,000.
If the calculated amount is KRW 2,000,000, it is reduced by KRW 100,000 to KRW 1,900,000. If the calculated amount is KRW 3,000,000, it is reduced by KRW 150,000 to KRW 2,850,000.
Importantly, the 5% reduction does not continue to increase the longer you delay applying. According to NTS guidance, the payment rate applied to late applications is 95% of the calculated amount.
How Much Is the Reduction Based on the Maximum Payment?
The maximum earned income tax credit attributable to 2025 varies by household type.
The maximum is KRW 1,650,000 for single-person households, KRW 2,850,000 for single-earner households, and KRW 3,300,000 for dual-earner households.
Applying the 5% late-application reduction directly to these maximum amounts produces the following results:
Single-person household: KRW 1,650,000 × 95% = KRW 1,567,500
Single-earner household: KRW 2,850,000 × 95% = KRW 2,707,500
Dual-earner household: KRW 3,300,000 × 95% = KRW 3,135,000
The corresponding reductions from the maximum payments are KRW 82,500, KRW 142,500, and KRW 165,000, respectively.
However, this does not mean every applicant will receive these amounts. Actual earned income tax credit payments vary depending on household type, income, assets, and other eligibility factors assessed during the review. The figures above are the author's calculations, applying the 5% reduction to the maximum payment amounts.
Late Applications Do Not Have Relaxed Eligibility Requirements
The late-application period provides an additional opportunity for people who missed the original deadline. It does not eliminate the income or asset requirements for the earned income tax credit.
The combined total income of spouses for 2025 must be below KRW 22,000,000 for single-person households, below KRW 32,000,000 for single-earner households, and below KRW 44,000,000 for dual-earner households.
For assets, the combined assets of all household members as of 2025-06-01 must be below KRW 240,000,000. Debts are not deducted.
If the household's combined assets are at least KRW 170,000,000 but below KRW 240,000,000, a separate reduction rule applies, under which only 50% of the credit is paid.
Therefore, assuming that a late application simply results in a 5% reduction may lead to a discrepancy between your expectations and the actual payment. Other eligibility requirements, including income and assets, are also reviewed.
When Will You Receive the Payment If You Apply Now?
Late applications also follow a different payment schedule from regular applications.
According to the NTS guidance on earned income tax credit reviews and payments, the payment deadline for late applications is within 4 months of the application date.
Therefore, applying in October 5 does not mean a specific payment date can be confirmed in advance. After applying, the most reliable approach is to check the review status through the earned income tax credit section of Hometax.
In addition, the amount entered when submitting an application is not automatically confirmed as the final payment. The NTS determines the actual payment after reviewing eligibility requirements, including income and assets.
Do Not Confuse This With the 2026 First-Half-Year Application
As of October, searches for '2026 earned income tax credit' may return different application schedules under the same general name.
This article covers late applications for the regular earned income tax credit attributable to 2025, based on income earned in 2025 and applied for in 2026.
By contrast, the application period from 2026-09-01 through September 15 was the half-year application period for employment income earned during the first half of 2026.
These applications relate to different income years and should not be treated as the same process.
In addition, employees who already completed a half-year application for the earned income tax credit attributable to 2025 in September 2025 or March 2026 may not need to submit a separate regular application in 2026.
Therefore, rather than assuming that missing the May application period automatically makes you a late applicant, first check whether you submitted a half-year application during the second half of last year or in March this year.
You May Still Be Eligible Even If You Did Not Receive an Application Notice
Not receiving an earned income tax credit application notice does not automatically mean you are ineligible to apply.
If you believe you meet the income, asset, and other eligibility requirements, you can apply directly through Hometax. If you received an application notice, you can use the mobile notice, the QR code on the mailed notice, or the automated telephone service (ARS) at 1544-9944, among other methods.
Older adults and others who have difficulty using a computer or mobile device can receive application assistance through the tax credit consultation center at 1566-3636.
If you missed the regular application period for the credit attributable to 2025, the first step is to check whether you previously submitted a half-year application and whether you meet the income and asset requirements. If you qualify, the key is to check your late-application options before 2026-12-01 passes.
Missing the May application period is not a reason to give up. However, you should also understand that late applications are subject to a 5% reduction in the calculated amount and follow a different payment schedule from regular applications.