

Will the 2026 ISA Reform Apply to Existing Account Holders? 2027 Contribution Limits and Contract Duration Rules
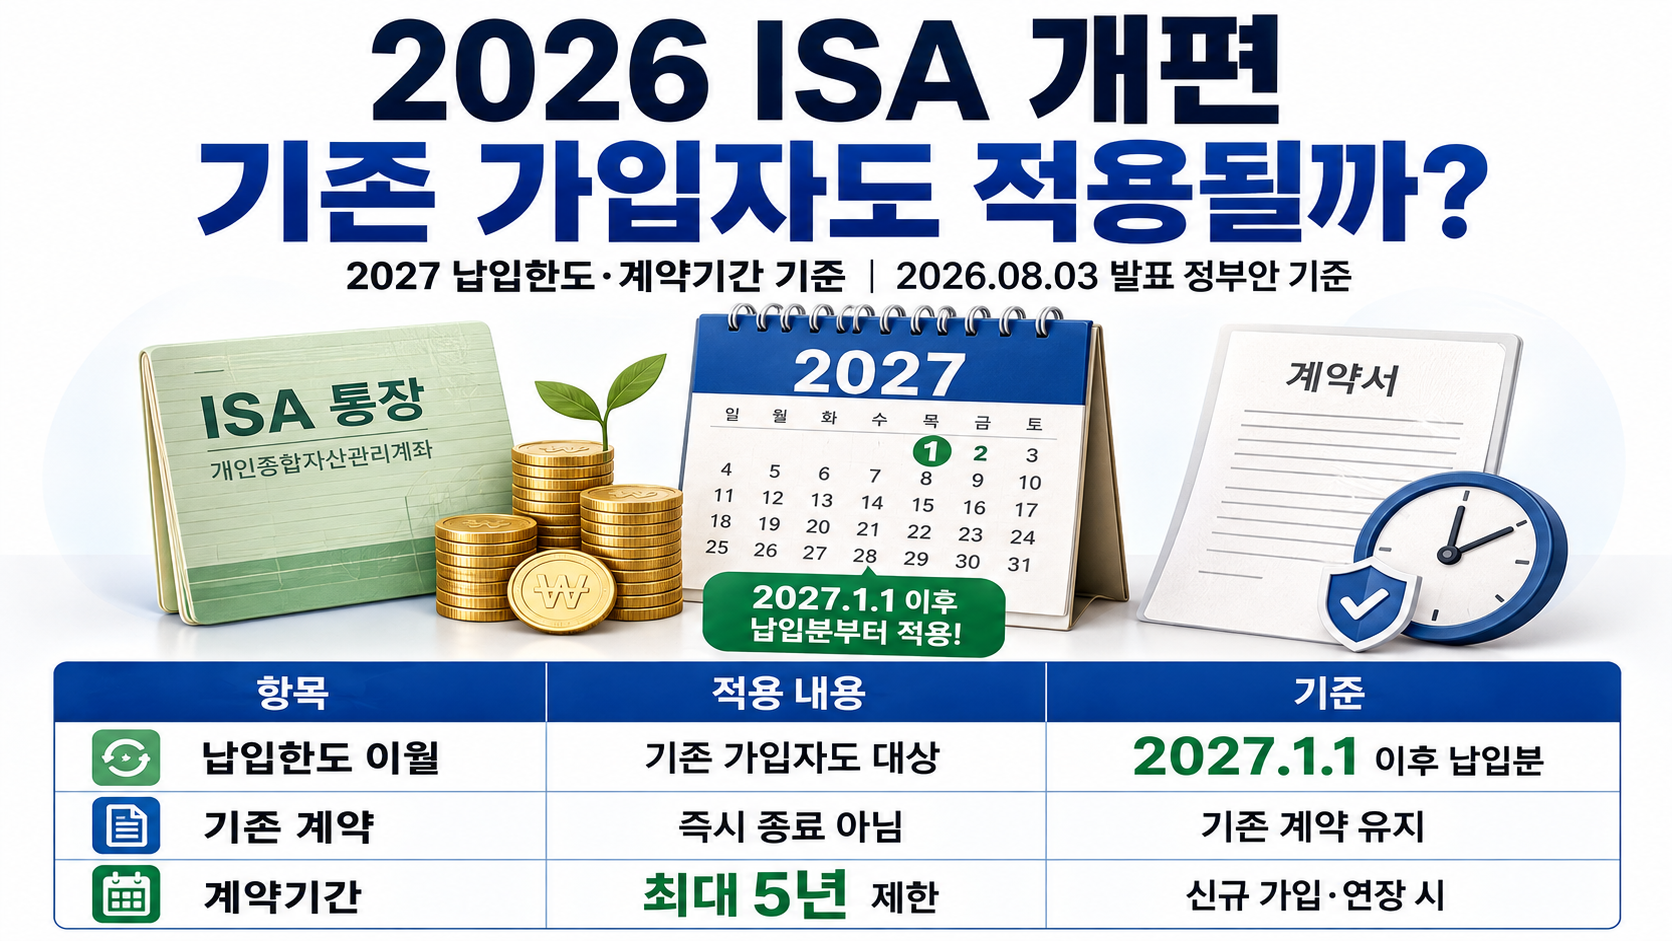
The bottom line is that the government proposal announced on 2026-08-03 includes existing ISA account holders in the planned abolition of annual contribution limit carryovers for contributions made from 2027-01-01 onward. However, existing contracts will not terminate immediately, and the maximum contract duration of 5 years is expected to apply when opening a new account or extending an existing contract.
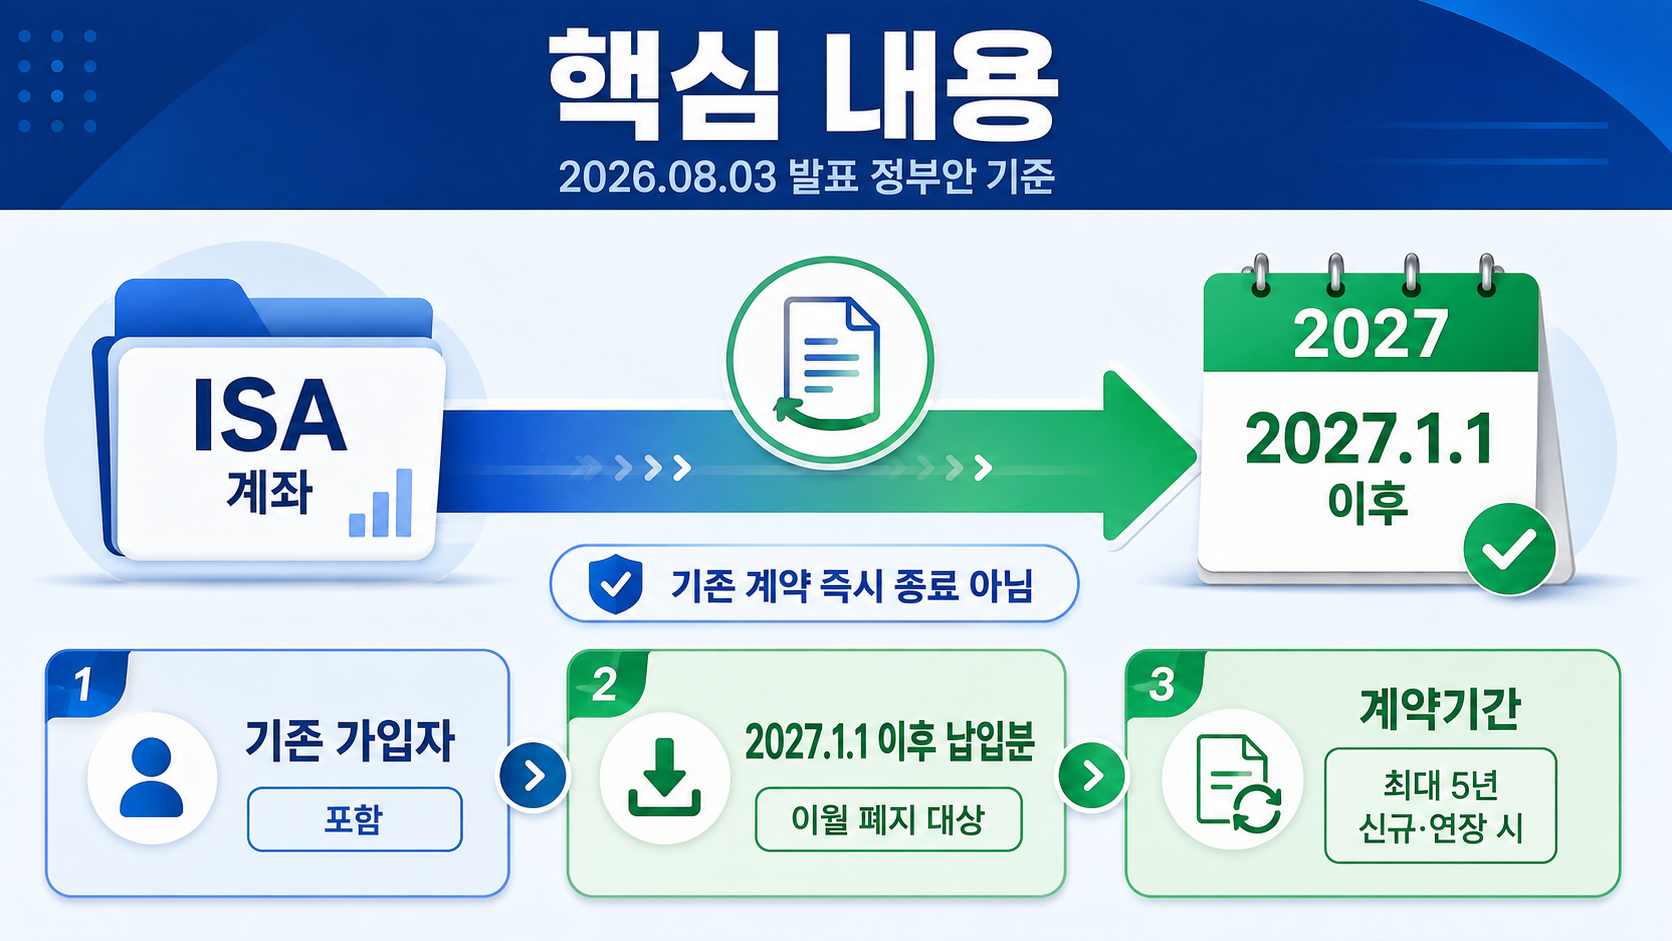
The measures announced so far are a government tax reform proposal, not legislation finalized by the National Assembly. There is no need to rush to close an existing ISA before the final legislation and transitional provisions are released.
What Will Change for Existing ISA Account Holders?
The changes that directly affect existing account holders concern contribution limit carryovers and contract extensions. Rather than eliminating previously contributed funds or tax benefits already received, the proposal changes the rules governing new contributions and contract extensions from 2027 onward.
| Category | Current Rules | 2026 Government Proposal | Application to Existing Account Holders |
|---|---|---|---|
| Annual contribution limit | KRW 20,000,000 per year | KRW 20,000,000 per year | Unchanged |
| Unused contribution allowance | Can be carried forward to the following year | Carryovers abolished | Expected to include contributions from 2027 onward |
| Total contribution limit | Up to KRW 100,000,000 | Up to KRW 100,000,000 | Expected to remain unchanged |
| Contract duration | Minimum 3 years, with extensions permitted | Initial 3 years, up to 5 years in total | Expected to apply to new accounts and extensions |
| Tax exemption for standard accounts | Net profits up to KRW 2,000,000 | No separate changes announced | Current rules expected to remain |
| Tax exemption for low-income and farming/fishing accounts | Net profits up to KRW 4,000,000 | No separate changes announced | Current rules expected to remain |
| Amount exceeding the tax-exempt threshold | Separately taxed at 9.9% | No separate changes announced | Current rules expected to remain |
The key point is that simply having an existing account does not guarantee continued access to the current carryover rules. If the government proposal passes unchanged, existing accounts will also be subject to the annual KRW 20,000,000 contribution limit from 2027 onward.
What Does 'Retroactive Application' Mean for Existing Account Holders?
The term 'retroactive application,' which has become a point of controversy, does not mean that previously received tax exemptions will be recalculated and recovered through additional taxation. The proposal is better understood as applying new rules to contributions and contract extensions made after the effective date, including those involving existing accounts.
The measures announced so far should be distinguished as follows.
No provision has been identified requiring funds contributed through 2026 to be forcibly withdrawn from accounts.
No provision has been identified requiring existing investment products to be sold.
No measure has been announced to reclaim previously received tax exemptions across the board.
Contribution limits from 2027 onward and future contract extensions may be subject to the revised rules.
Therefore, there is no reason to interpret the proposal as meaning that 'existing ISAs will disappear immediately' or that 'all benefits received so far must be repaid.'
How Much Difference Will Abolishing Contribution Limit Carryovers Make?
Under the current rules, if you do not use the full annual KRW 20,000,000 allowance, the unused portion can be carried forward to the following year. If the reform takes effect, it will become difficult to use the remaining allowance for contributions in subsequent years.
For example, assume that only KRW 5,000,000 was contributed in 2026.
| Category | Amount Available for Contribution in 2027 |
|---|---|
| Current carryover rules remain | KRW 35,000,000 |
| Carryover abolition applies | KRW 20,000,000 |
| Difference | KRW 15,000,000 |
Author's calculation: Under the current rules, the unused KRW 15,000,000 allowance from 2026 was added to the KRW 20,000,000 allowance for 2027. Under the reform proposal, the calculation applies only the annual KRW 20,000,000 limit.
However, the final wording of the legislation must be checked to determine whether all unused allowances accumulated through the end of 2026 will become unavailable in 2027 or whether transitional measures will preserve some of them. Although the government proposal states that existing account holders are included, the treatment of accumulated unused allowances has not yet been finalized in the operational systems of individual financial institutions.
Will Existing Contract Durations Suddenly Be Reduced to 5 Years?
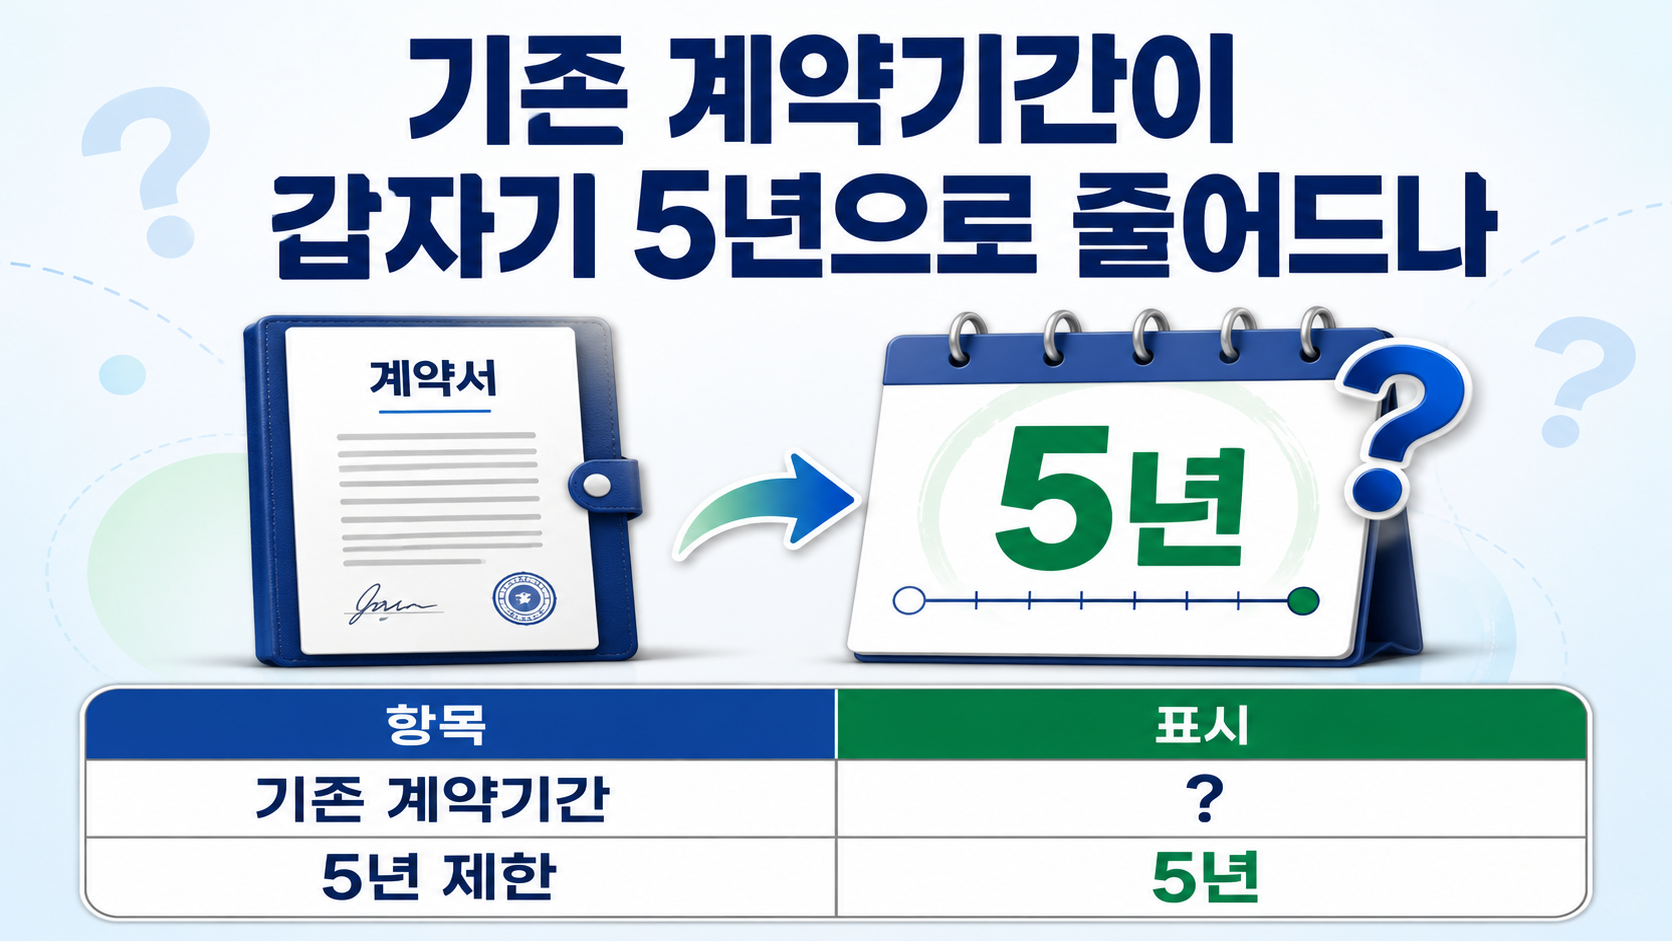
Existing contracts will not automatically terminate on the effective date. The government proposal would limit the total duration to 5 years, including the initial 3-year contract period, when someone opens a new account or extends an existing contract.
If you currently have an 3-year contract, the account will remain active until its agreed maturity date. When applying for an extension after maturity, you may be able to add only 2 years, making it highly likely that the total contract duration will be limited to 5 years.
For example, if you opened an account in 2025 with an 3-year contract, its existing maturity date would be 2028. If the reform takes effect unchanged, the account would be expected to remain operational until 2030 through a maximum extension of 2 years at maturity.
The final legislation and guidance from financial institutions will need to clarify which transitional measures apply to accounts with long-term extensions already agreed upon or accounts whose extensions were completed before the effective date.
Existing ISAs Will Not Automatically Convert into Productive Finance ISAs
The Productive Finance ISA is a separately established account type, not simply a renamed version of the existing ISA. Existing ISA holders will not be converted automatically, nor will their assets be forcibly transferred.
| Category | Government Proposal for Existing Standard ISAs | Government Proposal for Productive Finance ISAs |
|---|---|---|
| Annual contribution limit | KRW 20,000,000 | KRW 20,000,000 |
| Total contribution limit | KRW 100,000,000 | KRW 200,000,000 |
| Contract duration | Up to 5 years in total | Up to 10 years in total |
| Carryover of unused allowances | Expected to be abolished | Not permitted |
| Taxation of interest and dividends | KRW 2,000,000 or KRW 4,000,000 tax-exempt, then 9.9% | Full tax exemption planned |
| Main eligible investments | Domestic stocks, funds, domestically listed ETFs, and others | Domestic stocks, domestic equity products, the National Growth Fund, BDCs, and others |
| Domestically listed overseas index ETFs | Eligible for investment | Expected to be excluded |
| Planned implementation | Rule changes including existing accounts | New accounts opened from 2027 onward |
There is no need to close an existing ISA immediately simply because the Productive Finance ISA is expected to offer a full tax exemption. If your portfolio primarily consists of domestically listed ETFs tracking overseas indices such as the US S&P500 or Nasdaq100, the investment options available through an existing ISA may be more suitable.
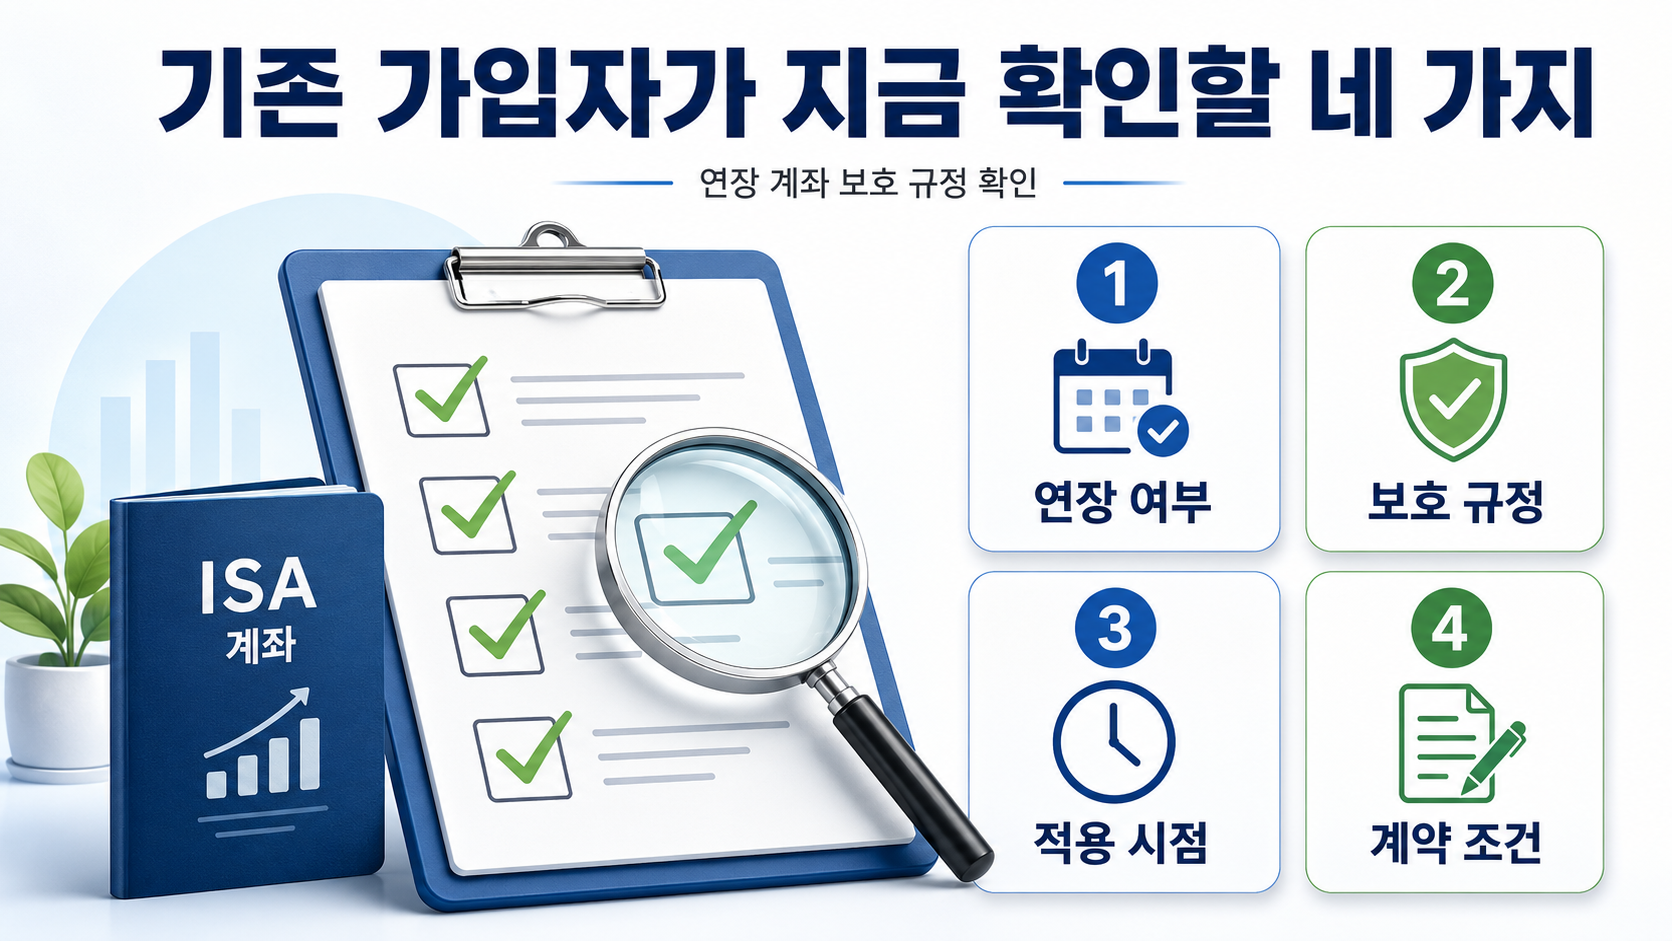
Four Things Existing Account Holders Should Check Now
1. Check Your Available Contribution Allowance in Your Financial Institution's App
Check this year's contributions and your remaining cumulative contribution allowance in your brokerage or banking app. Rather than estimating your allowance solely from the account opening date, it is safer to rely on the actual amount available for contribution as displayed by your financial institution.
2. Check Your Contract Maturity Date and Extension Status
Confirm the original account opening date, current maturity date, and whether a contract extension has already been agreed upon. In particular, if your account matures after 2027, the period for which it can be extended may change depending on the final legislation.
3. Do Not Make Excessive Contributions Solely Because of the Tax Changes
The expected abolition of carryovers does not mean you need to rush to invest money you would not otherwise use. An ISA is an account offering tax benefits, not a product that guarantees your principal or investment returns.
Whether to use your remaining allowance before the end of 2026 should be decided by considering your available cash, investment horizon, product risks, and asset allocation together.
4. Check the Transitional Provisions in the Final Legislation
The following points still need to be confirmed.
Whether the abolition of carryovers remains in the proposal during National Assembly deliberations.
Whether the 2027-01-01 effective date is finalized.
How unused allowances accumulated through the end of 2026 will be treated.
Whether separate protections will apply to accounts that have already been extended.
When the changes will be reflected in financial institutions' systems.
Because the government proposal and the rules ultimately implemented may differ, account holders should check both announcements in their financial institutions' apps and follow-up materials from the Ministry of Economy and Finance.
Should You Close Your Existing ISA Now?
At this stage, there is no need to rush to close an account solely because of the proposed reform. Early termination may reset the account's membership period and contribution allowance, and closing an account before completing the mandatory holding period may affect its tax benefits.
The Productive Finance ISA is also not yet available for subscription. It is safer to compare it with your existing ISA after the final legislation passes and financial institutions disclose the account structure and eligible investment products.
Frequently Asked Questions
Q1. If I Open an ISA Now, Will I Be Guaranteed the Current Carryover Benefits?
That is unlikely. The government proposal is designed to include both new and existing account holders in the abolition of contribution allowance carryovers from 2027 onward. You should not assume that opening an account now will lock in the current rules for an extended period.
Q2. Will All Unused Allowances Accumulated Through 2026 Disappear?
The government has announced its intention to apply the abolition of carryovers to existing account holders. However, whether all allowances accumulated through the end of 2026 will expire on the effective date or be covered by separate transitional measures must be confirmed through the final legislation and guidance from financial institutions.
Q3. Do I Have to Sell Overseas Index ETFs Held in My Existing ISA?
No provision has been identified in the announced measures requiring the forced sale of domestically listed overseas index ETFs already held in existing ISAs. The restriction on overseas index ETFs concerns eligible investments in the newly proposed Productive Finance ISA.
Q4. Will My Account Be Closed Immediately If Its Contract Duration Exceeds 5 Years?
No. The proposal does not mean existing contracts will be terminated immediately. The intended change is to limit total contract duration to a maximum of 5 years when opening a new account or extending a contract. The treatment of long-term extensions already agreed upon will depend on the transitional provisions.
Q5. Has This ISA Reform Been Finalized?
Not yet. It is a government tax reform proposal announced on 2026-08-03. Its provisions and implementation date may change during the legislative notice period, Cabinet deliberations, and the National Assembly's review and approval process.
Key Points to Remember
The government proposal intends to include existing ISA account holders in the abolition of contribution allowance carryovers from 2027 onward.
Existing contracts will not terminate immediately, and the maximum 5-year duration is expected to apply when opening new accounts or extending existing contracts.
The treatment of unused allowances accumulated through 2026 and contracts already extended must be confirmed through the final transitional provisions.
Because the legislation has not yet been finalized by the National Assembly, there is no reason to rush to close an existing ISA solely because of the reform proposal.
---
※ This article is provided for informational purposes to help readers understand market developments and does not constitute an investment recommendation for any particular security or asset. All final investment decisions and associated responsibilities rest with the individual investor.