

2026 Year-End Tax Settlement: Family Card Income Deductions Are Based on the Cardholder, Not the Person Who Pays the Bill
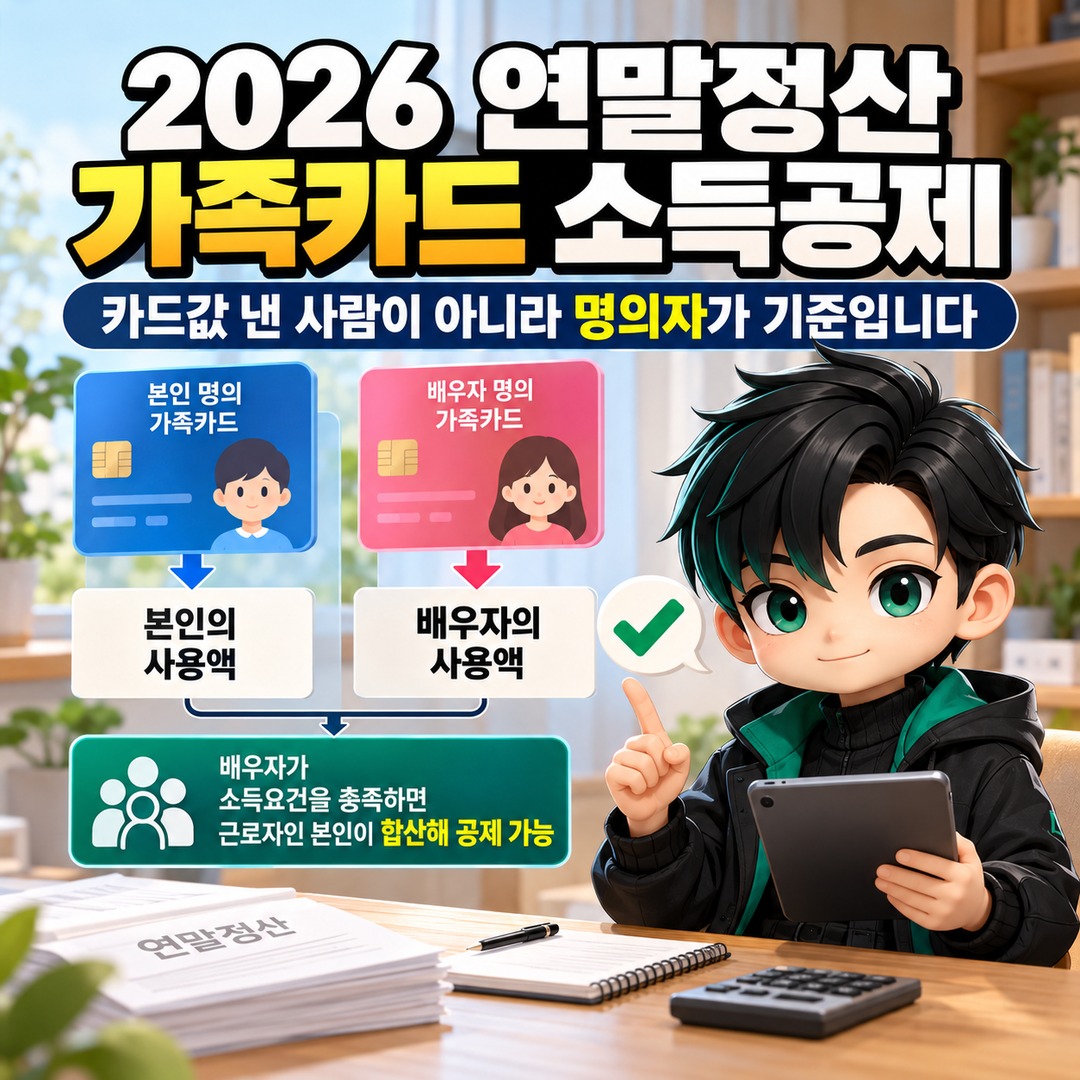
For the 2026 year-end tax settlement, family card spending is attributed to the family cardholder, not the person who pays the credit card bill. Even if you pay your spouse's card bill, spending on a card issued in your spouse's name is generally considered your spouse's spending. However, if your spouse meets the income requirements, you may include that spending in your own income deduction as an employee.
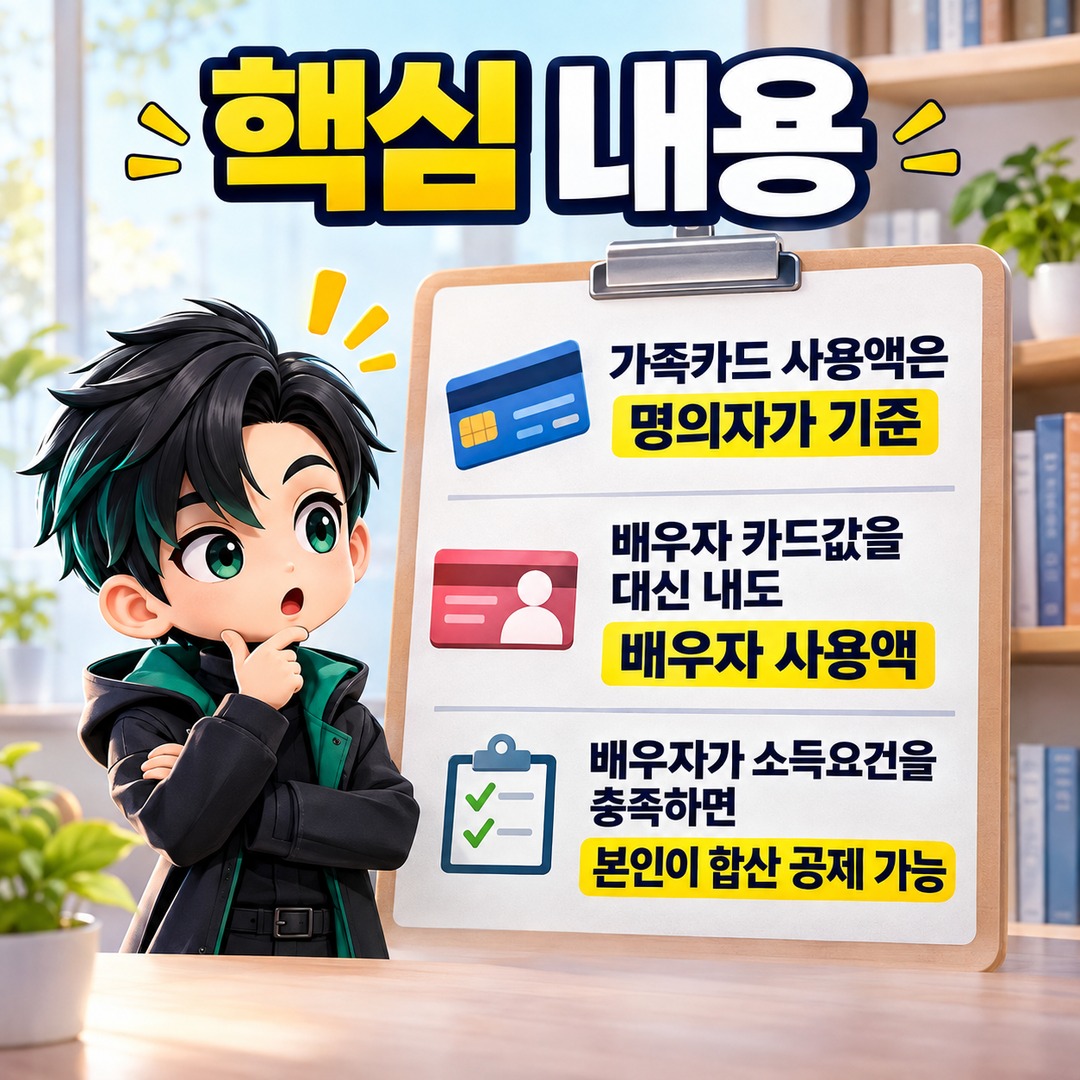
In particular, dual-income couples cannot combine their card spending simply because both card bills are paid from the same bank account.
As of 2026-10-19, the first things to check when preparing for year-end tax settlement are the name on each card and each family member's annual income, rather than the account used to pay the bills.
1. Who Is Eligible for Family Card Income Deductions?
Family card spending is attributed to the person named on the card, regardless of who actually pays the bill.
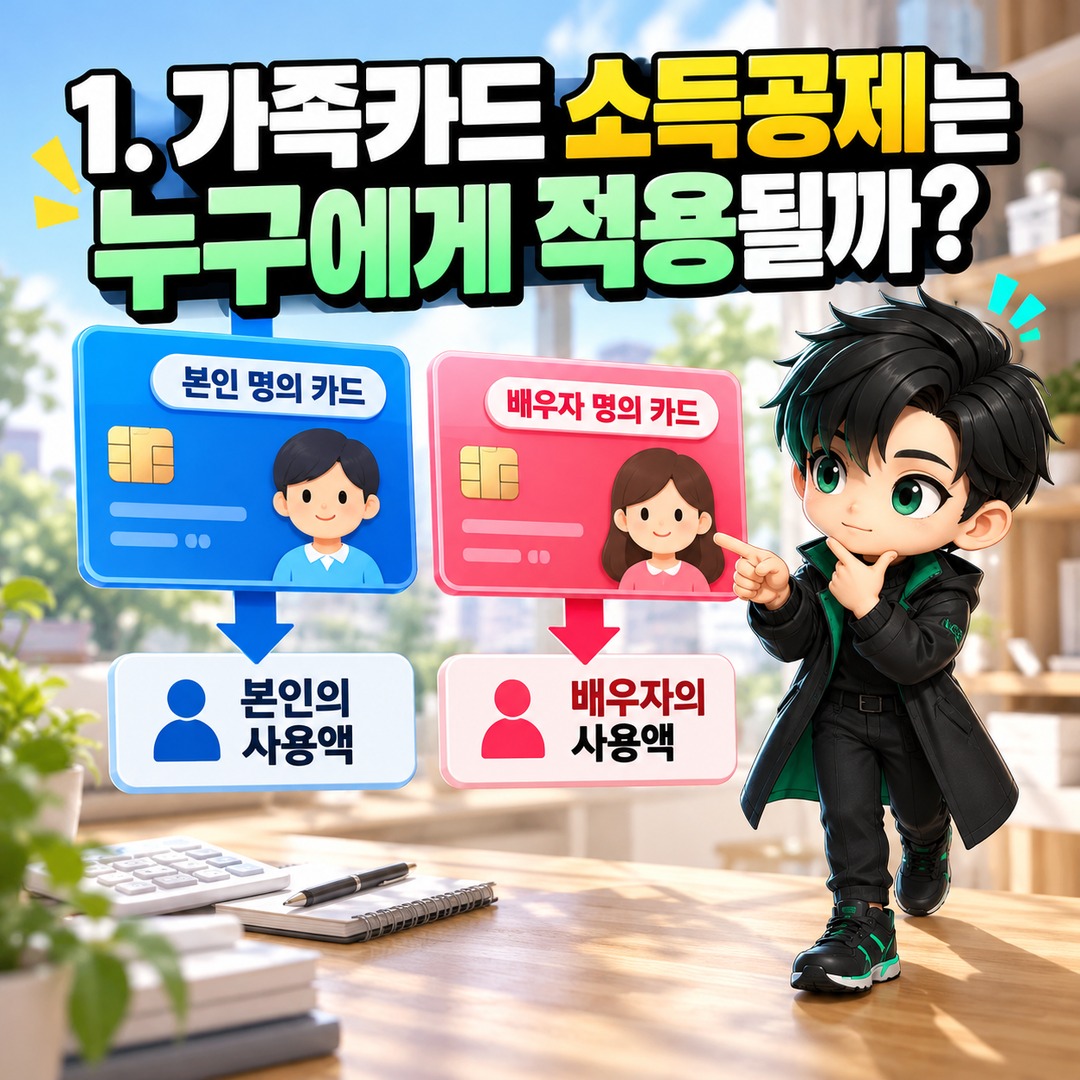
For example, suppose a husband obtains a supplementary family card in his wife's name under his credit card account and pays all the card bills from his own bank account.
In this case, spending on the family card issued in his wife's name is not automatically added to the husband's spending.
| Card Usage Situation | Basis for Determining the Income Deduction |
|---|---|
| Card issued in the husband's name | Husband's spending |
| Family card issued in the wife's name | Wife's spending |
| Husband pays the wife's card bill | Wife's spending, regardless of who pays |
| Card held by a spouse who meets the income requirements | The employee may combine the spending if the requirements are met |
Importantly, the cardholder and the person claiming the income deduction do not necessarily have to be the same person.
If a spouse meets the income requirements under tax law, spending on that spouse's card may also be included in the employee's year-end tax settlement.
The National Tax Service (NTS) states that family card spending must be attributed to the named cardholder when applying income deductions for credit card and other eligible spending.
2. Can Dual-Income Couples Combine Their Credit Card Spending?
If both spouses in a dual-income household exceed the annual income threshold, they cannot combine each other's card spending.
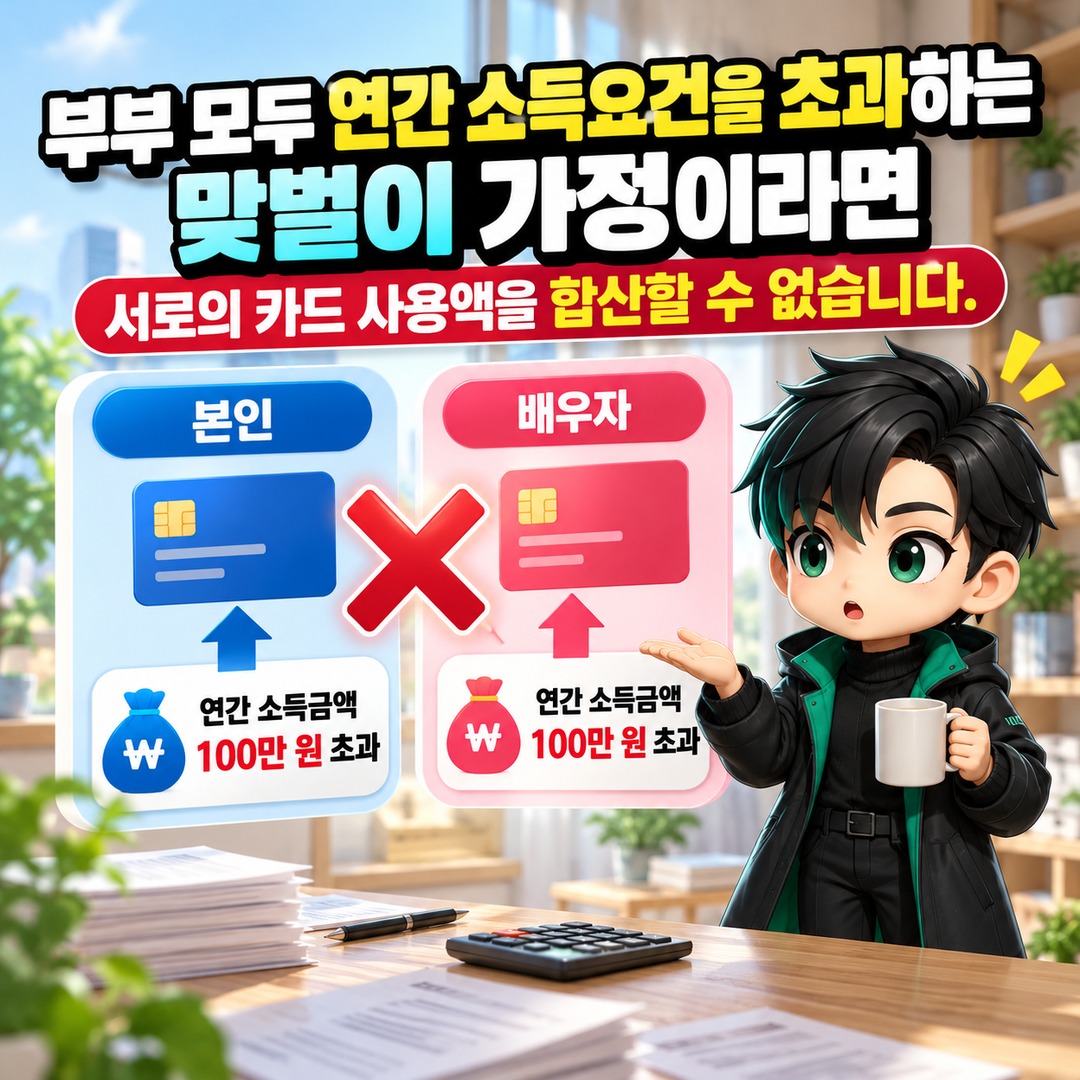
If a spouse's annual income amount exceeds KRW 1,000,000, that spouse's card spending generally cannot be included in the other spouse's income deduction.
However, if the spouse has only employment income, the income requirement is considered satisfied when gross annual salary is KRW 5,000,000 or less.
Here, gross salary generally refers to annual employment income excluding non-taxable employment income.
Understanding the Rules Through Examples
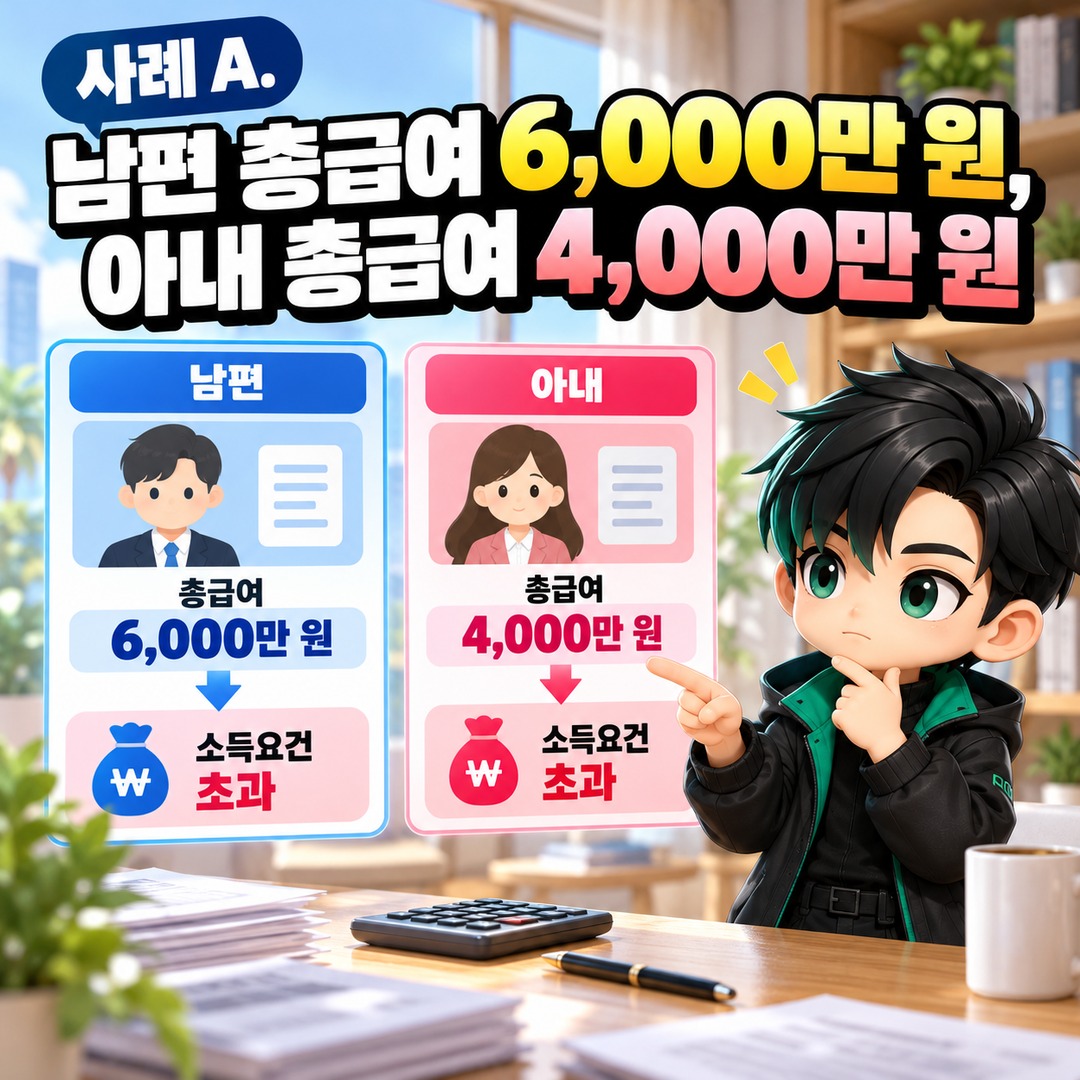
Case A. Husband's Gross Salary KRW 60,000,000, Wife's Gross Salary KRW 40,000,000
Both spouses have employment income, and each exceeds the income threshold.
Even if the husband pays the entire bill for the family card issued in his wife's name, that spending cannot be added to his deductible spending.
Case B. Husband's Gross Salary KRW 60,000,000, Wife's Gross Employment Income KRW 4,000,000
If the wife has only employment income and no other income, she meets the income requirements.
Therefore, eligible spending on the card issued in the wife's name may be included in the husband's year-end tax settlement.
However, the determination may change if the wife has a different type of income or earns additional income.
3. Can You Claim a Spouse's Card Spending Even If the Spouse Is Not Eligible for the Basic Personal Deduction?
In some cases, yes.
When combining spending by a spouse or direct ascendants and descendants, the credit card income deduction has certain eligibility requirements that differ from those for general personal deductions.
One major difference concerns age requirements.
For example, credit card spending by parents who meet the income requirements may qualify for inclusion in the deduction regardless of their age.
However, the applicable family relationship, livelihood, and income requirements must be satisfied.
One important exception is that credit card spending by siblings cannot be combined, even if those siblings qualify as dependents for the basic personal deduction.
You should also ensure that spending by a spouse, parents, or other eligible family members is not claimed twice by different employees.
4. How Much Tax Can You Save by Combining KRW 10,000,000 in Family Card Spending?
Being eligible to combine family card spending does not mean the entire amount spent is deductible.
Income deductions for credit card and other eligible spending are calculated based on the amount exceeding 25% of gross salary.
The deduction rate for ordinary credit card spending is 15%, while the rate for ordinary debit card spending and cash receipt transactions is 30%.
| Category | Standard Deduction Rate |
|---|---|
| Credit cards | 15% |
| Debit cards | 30% |
| Cash receipts | 30% |
| Traditional market spending | 40% |
| Public transportation spending | 40% |
Calculation Example for an Employee With a Gross Salary of KRW 50,000,000
Assume the employee meets the requirements for combining family card spending.
Gross salary: KRW 50,000,000
Employee's ordinary credit card spending: KRW 10,000,000
Ordinary credit card spending in the spouse's name: KRW 10,000,000
Combined spending: KRW 20,000,000
First, calculate 25% of gross salary.
KRW 50,000,000 × 25% = KRW 12,500,000
The amount spent above the deduction threshold is calculated as follows.
KRW 20,000,000 - KRW 12,500,000 = KRW 7,500,000
If all spending consists of ordinary credit card transactions and there are no other adjustments, the calculation is as follows.
KRW 7,500,000 × 15% = KRW 1,125,000
This is the income deduction amount, not the actual tax refund.
An income deduction reduces the income amount used to calculate taxes, so the actual tax savings depend on the individual's taxable income, applicable tax rates, and other deductions.
Deduction limits based on gross salary brackets and additional deduction rules for traditional markets, public transportation, and other eligible spending also apply separately.
Therefore, combining family card spending does not necessarily result in a tax refund.
*The amounts above are the author's illustrative calculations based on the stated assumptions.*
5. What If Your Spouse's Card Spending Does Not Appear in Hometax?
Spending on a card issued in your spouse's name may not automatically appear in your year-end tax settlement records.
If this happens, first check whether consent to provide tax information has been granted and confirm the name on the card.
Steps to Check
1. Visit National Tax Service Hometax.
2. Check credit card and other eligible spending records through the simplified year-end tax settlement service.
3. If your spouse's records are not visible, check the status of consent to provide dependent family members' tax information.
4. Compare the card issuer's transaction records with the amounts displayed in Hometax.
5. Verify your spouse's income eligibility and the amount of qualifying spending before including it in your year-end tax settlement.
Consent to provide tax information is a procedure that allows you to view your spouse's records.
Granting consent to provide tax information does not mean that all spending on your spouse's card qualifies for an income deduction.
If your spouse does not meet the income requirements, you cannot claim a combined deduction even if you can view the records.
Additionally, the total amount charged by the card issuer may differ from the amount eligible for year-end tax settlement deductions.
This is because certain expenses, including taxes, utility charges, and insurance premiums, are excluded under the law.
6. Can Parents Claim Income Deductions for Family Cards Issued in Their Children's Names?
Family cards issued in children's names are also assessed based on the named cardholder.
If a child meets the income requirements and satisfies the family relationship requirements for credit card income deductions, the child's spending may be included in a parent's year-end tax settlement.
Importantly, the age requirement for the general basic personal deduction does not apply to credit card income deductions, even if the child falls outside the usual qualifying age range.
However, if the child earns employment income, business income, or other income, the annual income requirements must be checked separately.
Parents also cannot claim duplicate deductions for the same spending by their child.
7. Three Things to Check Before Year-End Tax Settlement
When preparing to claim family card income deductions, focus on the following three points.
First, Confirm the Name on the Card
Check whose name appears on the family card. The bank account used to pay the bill does not determine who is entitled to the income deduction.
Second, Check the Income Requirements for Your Spouse and Children
Eligibility may differ depending on whether family members have only employment income or also receive other types of comprehensive income.
Third, Check the Amount of Spending Eligible for Deduction
Not every card payment qualifies for a deduction. You must consider the 25% gross salary threshold, deduction rates by spending category, and applicable deduction limits.
In particular, dual-income couples cannot claim deductions by arbitrarily assigning their combined spending to one spouse immediately before year-end tax settlement.
8. Frequently Asked Questions
Q. If the Card Bill Is Paid From the Husband's Bank Account, Can He Claim the Deduction?
No. Family card income deductions are determined based on the named cardholder. Even if the husband pays the bill, spending on a family card issued in the wife's name is considered the wife's spending. The husband must meet separate income-related eligibility requirements to include that spending in his deduction.
Q. Can Card Spending Be Combined If My Spouse Has Left Their Job?
Leaving a job alone does not determine eligibility. You must check the spouse's annual income amount, gross employment income, and other applicable income requirements for the relevant tax year.
Q. If My Spouse's Card Spending Does Not Appear in Hometax, Does That Mean I Cannot Claim a Deduction?
Not necessarily. Check the status of consent to provide tax information and the card issuer's records, then determine whether the actual deduction requirements are satisfied.
Q. Can a Married Couple Split Family Card Spending Between Them for Income Deductions?
Both spouses cannot claim deductions for the same card spending. Eligibility must be determined based on the name on the card and each spouse's income requirements.
---
Conclusion: For Family Card Income Deductions, Card Ownership and Income Matter More Than the Payment Account
When reviewing family card spending for the 2026 year-end tax settlement, the first question is not who paid the credit card bill.
The key factors are whose name is on the card, whether that family member meets the income requirements, and whether the spending actually qualifies for a deduction.
Dual-income couples should distinguish each spouse's spending. If you want to combine spending on a card held by a spouse with little or no income, it is advisable to check the annual income requirements first.
Final eligibility for deductions must be determined according to the laws and National Tax Service guidance applicable to the 2026 tax year, along with each individual's income records.
Information verified as of: 2026-10-19
※ This article is provided for reference to help readers understand market trends and does not constitute an investment recommendation for any particular stock or asset. Individuals are responsible for their final decisions and investment outcomes.