
2026 Tax Credit for Rent: Can a Spouse Living Separately Also Claim It? Conditions for the Combined Couple Limit of KRW 10,000,000
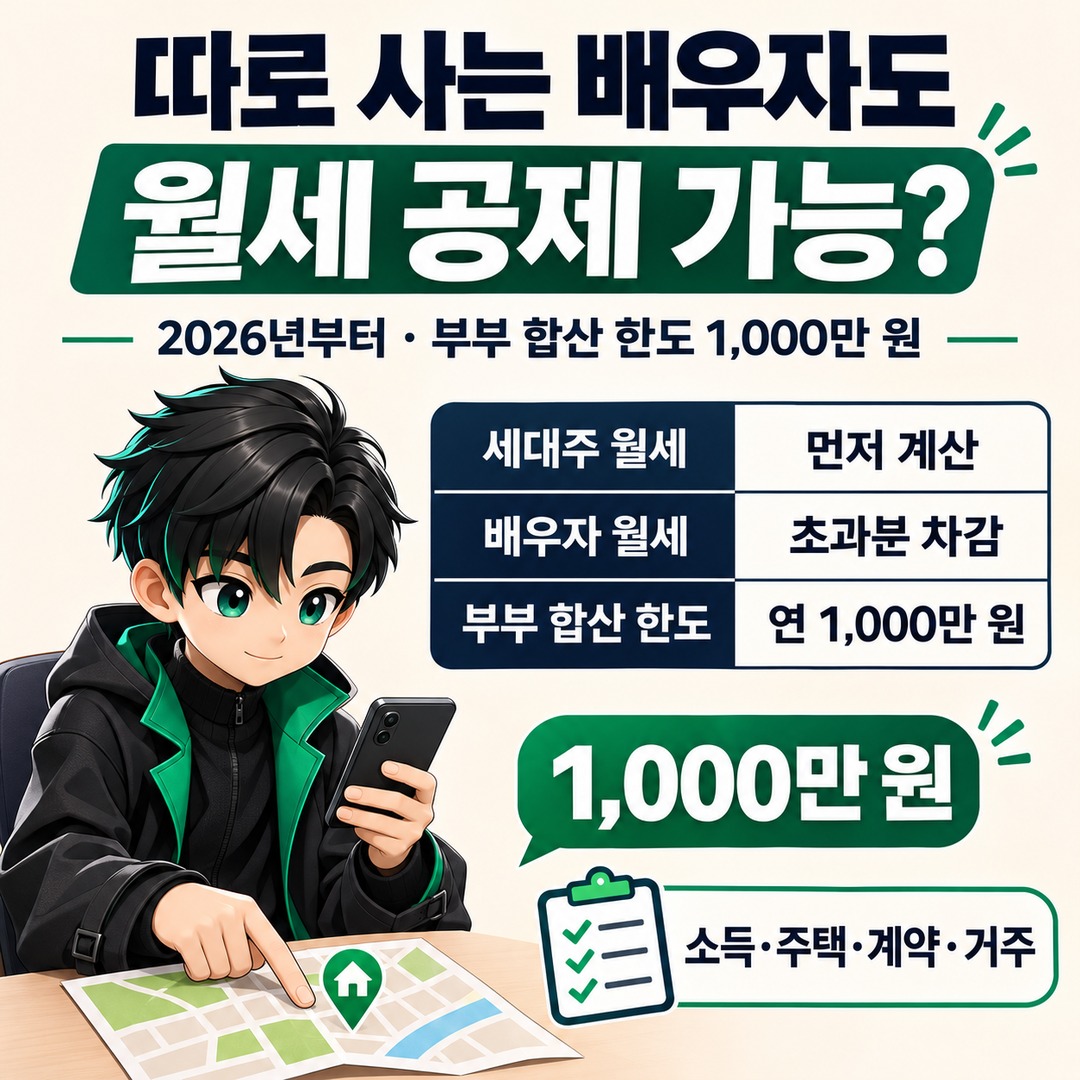
Starting in 2026, childless couples who live at different addresses can each claim a tax credit for rent. The key changes are that a spouse living at a different address from the head of household may qualify for a separate credit, and that the couple’s rent payments are subject to a combined annual limit of KRW 10,000,000. However, living separately does not automatically qualify a couple for the credit; income, housing, lease, and actual-residence requirements must be checked.
What changed starting in 2026?
The legal basis for this change is Article 95(2) of the 「Restriction of Special Taxation Act」, as amended by 2025-12-23. For rent paid from 2026-01-01 onward, it allows the head of household’s spouse to claim an additional tax credit if certain requirements are met.
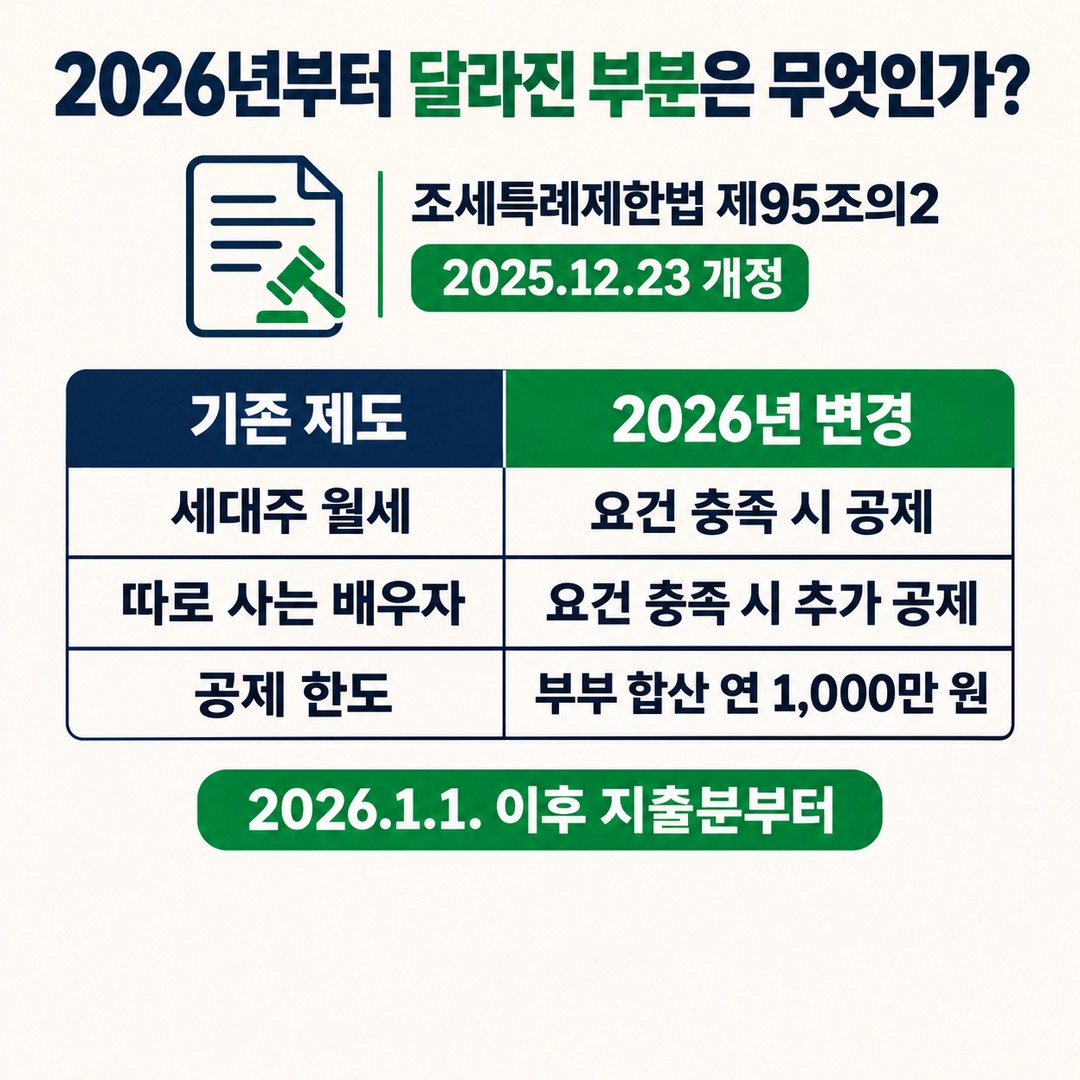
This can be found in Article 95(KRW 2) of the Restriction of Special Taxation Act.
The key changes from the previous system are as follows.
| Category | Previous rules | 2026 changes |
|---|---|---|
| Head of household’s rent | Credit available if requirements are met | Unchanged |
| Spouse living separately | Separate credit restricted | Additional credit available if requirements are met |
| Credit limit | KRW 10,000,000 per year | KRW 10,000,000 per year combined for the couple |
| Applicable period | Previous rules | For rent paid from 2026 onward |
The National Assembly Budget Office’s materials on the review of tax law revisions in 2025 also confirm the addition of a spouse’s credit and the application of a combined limit for the couple.
What requirements apply if spouses live in different areas?
Having different addresses alone is not enough. Article 95, Paragraph 5 of the 「Enforcement Decree of the Restriction of Special Taxation Act」, in force under 2026-09-18, requires that the head of household’s and spouse’s addresses be in different cities, counties, or autonomous districts.
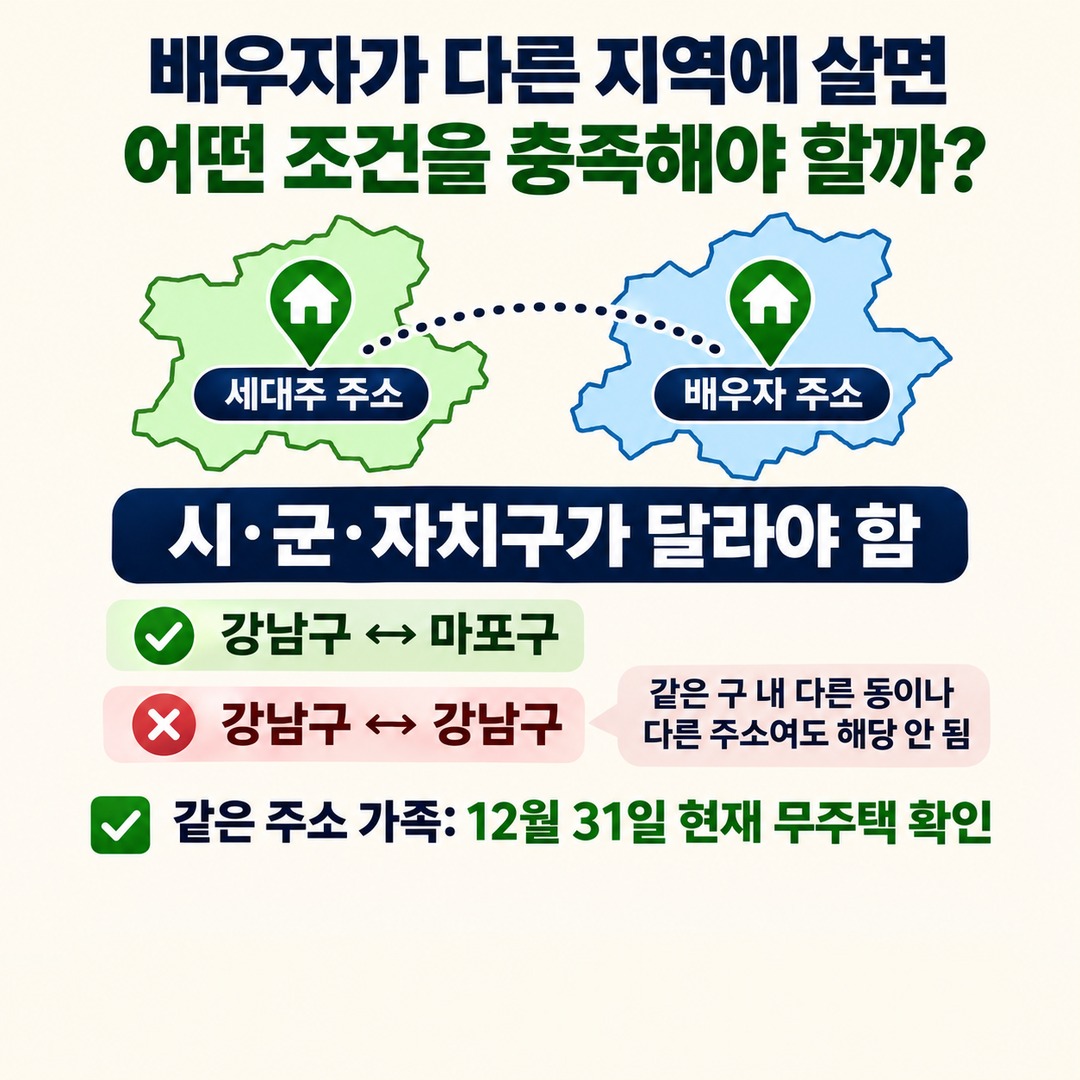
The detailed requirements in Article 95 of the Enforcement Decree of the Restriction of Special Taxation Act are as follows.
First, the addresses must be in different cities, counties, or autonomous districts.
For example, the following cases can be distinguished:
Therefore, simply living in a different apartment or neighborhood does not qualify someone for the credit.
Second, you must also check whether family members living at the same address as the spouse own a home.
If any of the following family members share the spouse’s address, they must be homeowners-free as of December 31, the end of the tax year.
The head of household’s lineal ascendants and descendants, and their spouses
The spouse’s lineal ascendants and descendants, and their spouses
The siblings of the head of household and spouse
The requirements may differ depending on whether the spouse lives alone in another area or lives there with family members such as parents or siblings.
How is the combined couple rent limit of KRW 10,000,000 calculated?
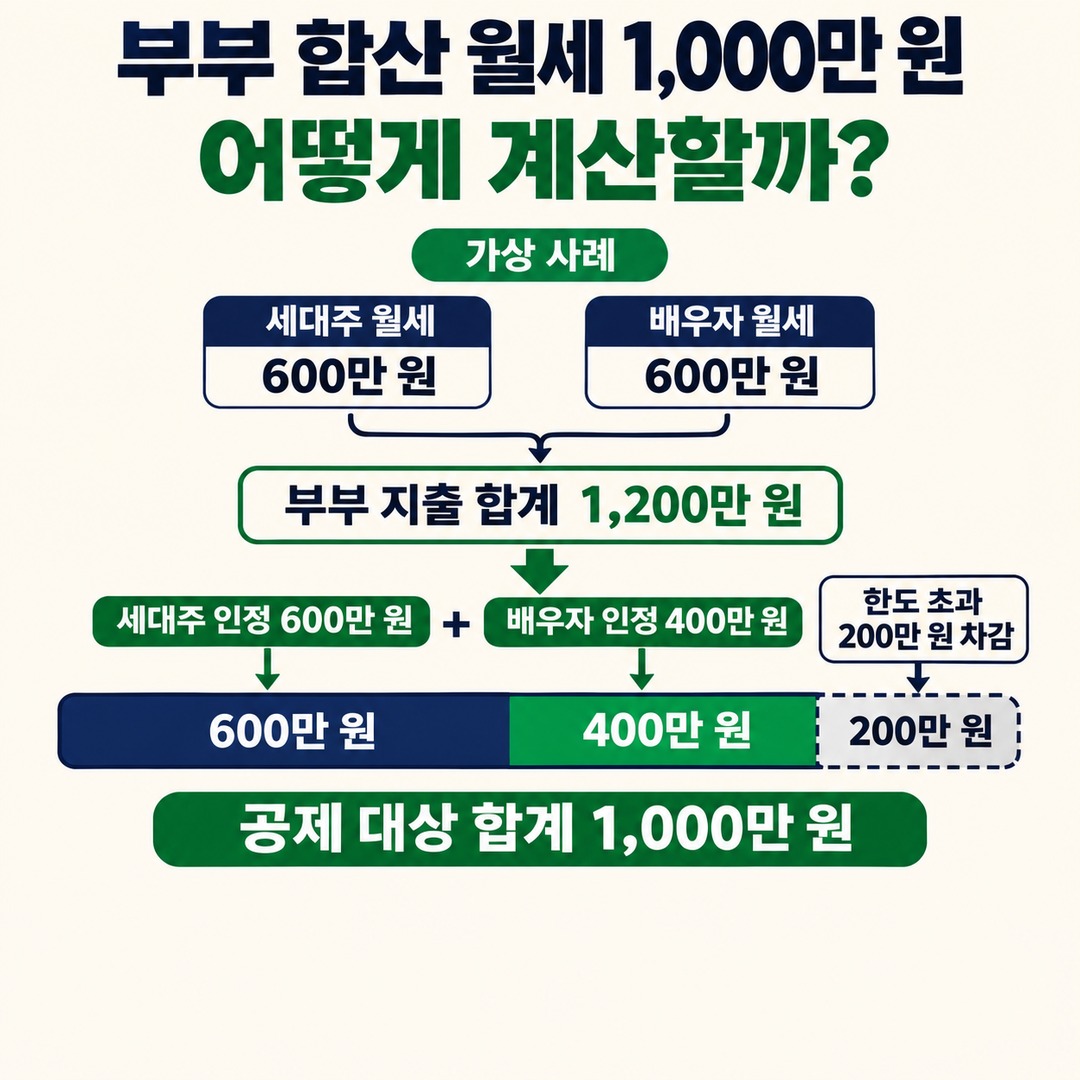
The key point is that this is not a system under which each spouse receives a separate KRW 10,000,000 deduction. The rent paid by the head of household and spouse is combined, and only up to KRW 10,000,000 per year is recognized as an eligible amount for the credit.
In particular, the law provides that if the combined amount exceeds KRW 10,000,000, the excess is deducted from the spouse’s rent amount.
The following is a hypothetical calculation for illustration.
Hypothetical example: The couple each pay KRW 6,000,000 in rent per year
Head of household’s rent
KRW 6,000,000
Spouse’s rent
KRW 6,000,000
Couple’s total actual rent paid
KRW 12,000,000
Amount recognized for the head of household
KRW 6,000,000
Amount recognized for the spouse
KRW 4,000,000
Final rent amount eligible for the credit
KRW 10,000,000
Author’s calculation: KRW 6,000,000 + KRW 6,000,000 - KRW 2,000,000 (amount exceeding the limit) = KRW 10,000,000
The key point is that the head of household’s rent is calculated first, and the spouse’s eligible rent amount is reduced by the amount that exceeds the limit.
Therefore, if the head of household has already paid at least KRW 10,000,000 in rent for the year, the additional rent amount recognized as eligible for the spouse’s credit will be KRW 0.
Which rate applies based on income: 15% or 17%?
The rent tax credit rate is determined by each employee’s income. Check the income requirements for each person claiming the credit; the couple’s combined income is not the basis.
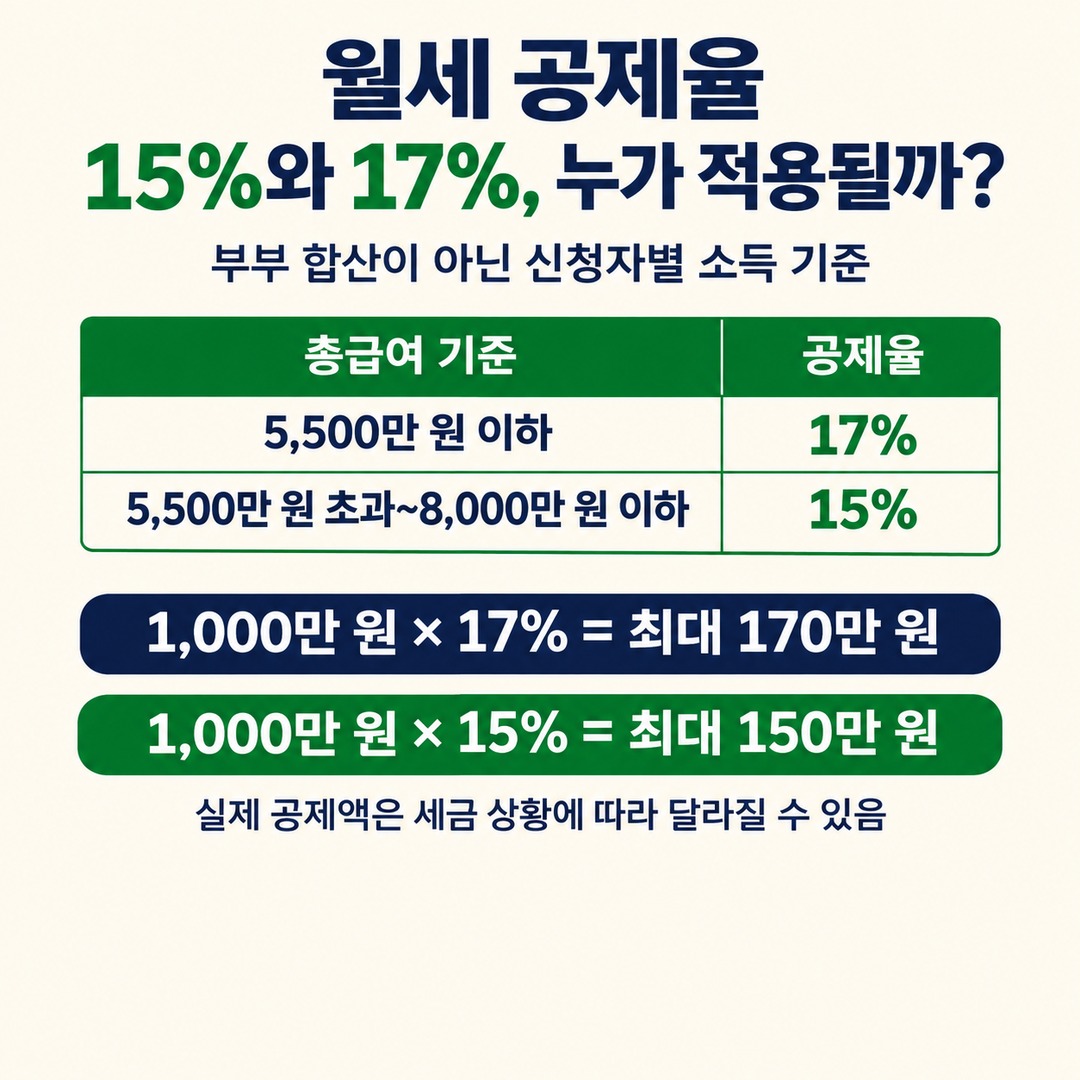
| Individual income threshold | Credit rate |
|---|---|
| Gross salary of KRW 55,000,000 or less | 17% |
| Gross salary over KRW 55,000,000 and up to KRW 80,000,000 | 15% |
If an individual’s comprehensive income exceeds KRW 45,000,000 or KRW 70,000,000, respectively, they do not meet the requirements for the corresponding credit rate.
The credit under Article 95(2) of the Restriction of Special Taxation Act is calculated as follows.
At 17%: KRW 10,000,000 × 17% = maximum KRW 1,700,000
At 15%: KRW 10,000,000 × 15% = maximum KRW 1,500,000
If both spouses qualify for 17%, their combined tax credit is up to KRW 1,700,000. If both qualify for 15%, it is up to KRW 1,500,000.
However, if their income circumstances differ, the applicable credit rate must be calculated separately for each person. The actual credit may vary depending on each person’s tax situation, including their calculated tax liability.
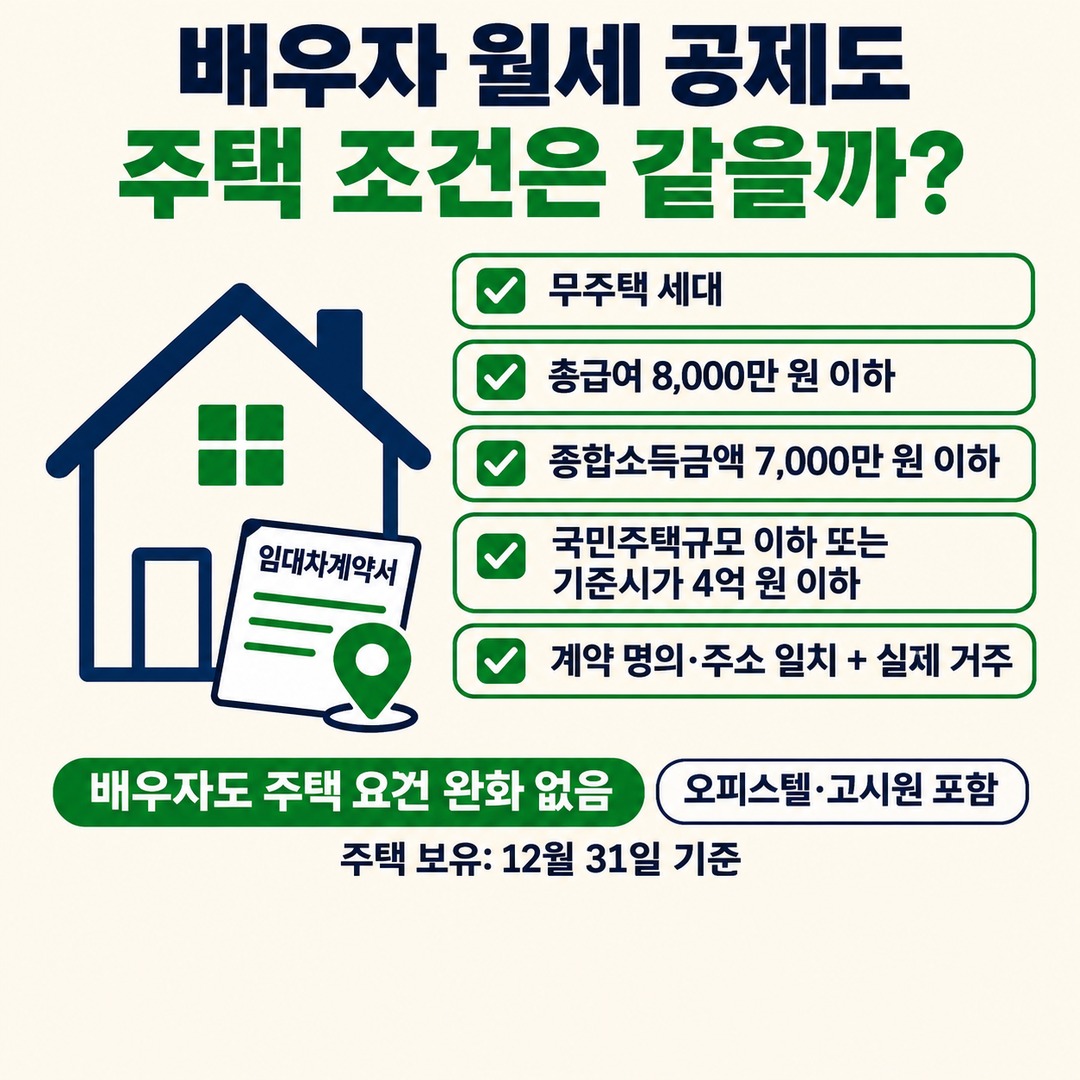
Must the spouse’s rental home meet the same housing requirements to qualify for the rent tax credit?
Yes. Allowing a spouse to claim an additional credit did not relax the requirements for the rented home.
Under Article 95 of the Enforcement Decree of the Restriction of Special Taxation Act, in force in 2026, check the following requirements.
| Requirement | Key condition |
|---|---|
| Home ownership | Household must not own a home |
| Gross salary | KRW 80,000,000 or less |
| Comprehensive income | KRW 70,000,000 or less |
| Home size/value | No larger than the National Housing Size or assessed at KRW 400,000,000 or less |
| Lease in whose name | The employee claiming the credit or a person eligible for the basic deduction |
| Address | Address on the lease must match the address on the resident registration record |
| Actual residence | The employee claiming the credit must actually live there |
Residential officetels and goshiwon rooms are also included in the housing requirements.
In addition, if there are at least 3 children and grandchildren eligible for the basic deduction, the housing size limit expands to a private area of 100㎡ or less, regardless of location. The assessed-value threshold of KRW 400,000,000 or less also applies.
In particular, homeownership must be checked as of December 31, the end of the year.
The National Tax Service’s 2026-01-23 year-end tax settlement guidance also states that the credit is unavailable if the taxpayer has not registered their move-in at the rental home or does not actually live there.
What should you check when preparing to claim the credit?
Prepare the records for rent paid in 2026 so they can be included in the 2027 year-end tax settlement.
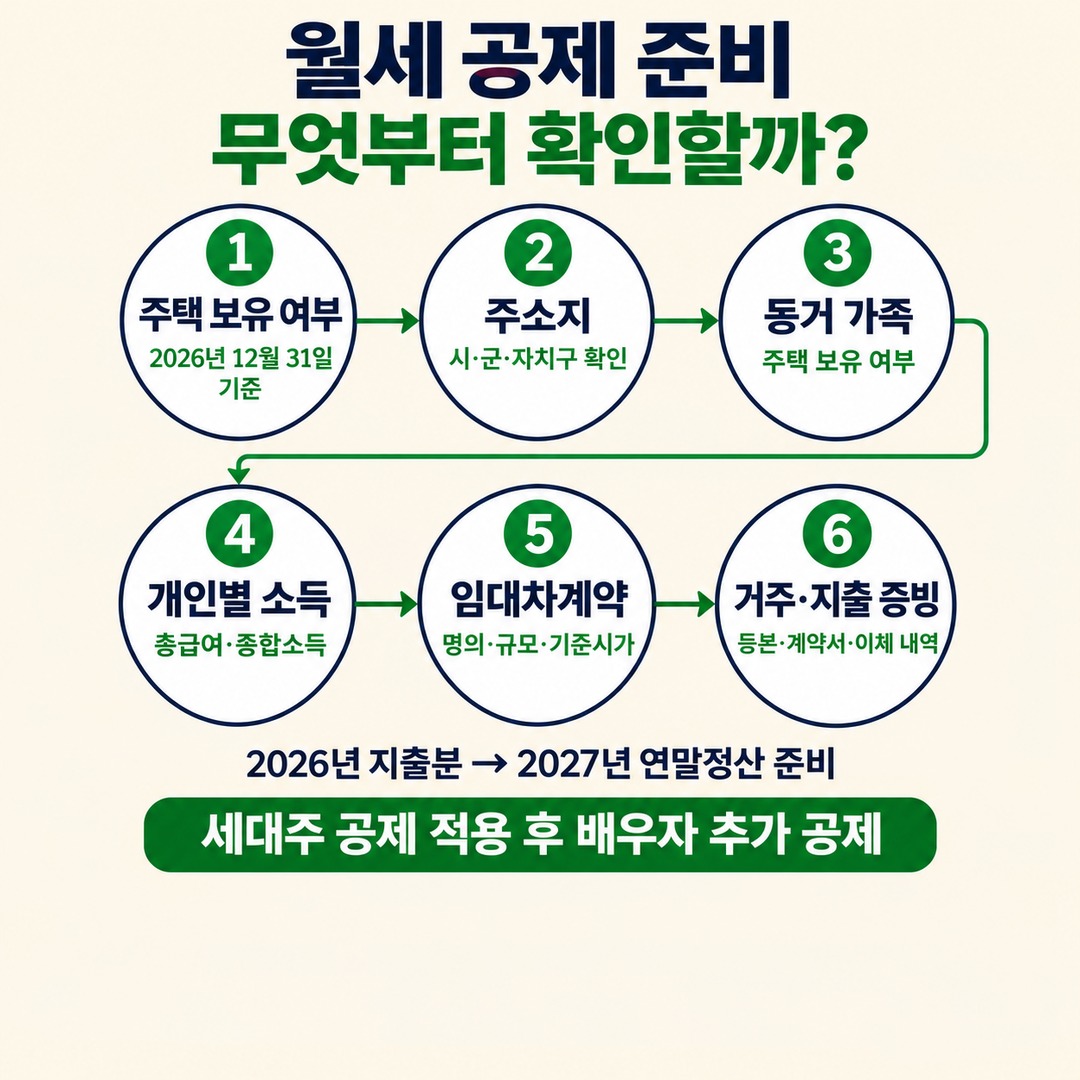
It is best to check the following in order.
1. Check whether either spouse owns a home: Use 2026-12-31 as the reference date.
2. Check the addresses: Confirm that the head of household and spouse live in different cities, counties, or autonomous districts.
3. Check family members living with the spouse: Confirm whether those family members own a home.
4. Check each person’s income: Review both spouses’ gross salary and comprehensive income separately.
5. Check the lease: Confirm the name of the tenant, the home’s size, and its assessed value.
6. Prepare proof of actual residence and rent payments: Gather relevant documents, such as a resident registration record, lease, and bank transfer history.
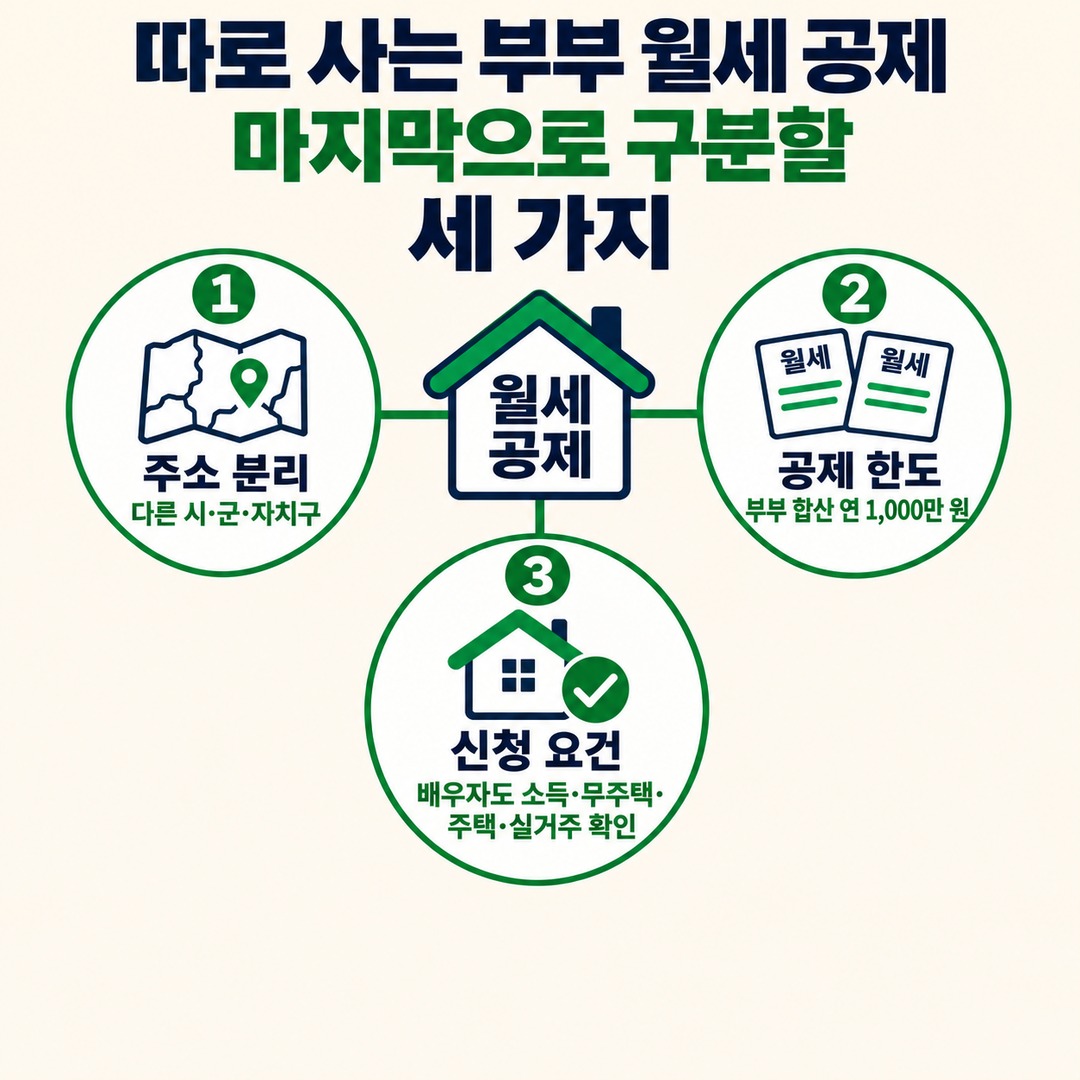
When applying for the credit, remember that the head of household must also be claiming the rent tax credit. The spouse’s additional credit is conditional on the head of household claiming the credit under Paragraph 1.
Three things to distinguish about rent credits for couples living separately
When applying the 2026 amendments, do not confuse the following three points.
Separate addresses: The spouses must live in different cities, counties, or autonomous districts. Having separate addresses within the same district does not qualify.
Credit limit: The couple does not each receive KRW 10,000,000; the combined limit is KRW 10,000,000.
Credit eligibility: The spouse must also meet the requirements in Paragraph 1, including those for income, homeownership, the rented home, and actual residence.
Ultimately, the expanded 2026 rent tax credit is a meaningful change for couples who live in different areas because of work or other circumstances, such as spouses who live apart during the week.
However, even if the spouses have different addresses, eligibility may vary depending on family members’ homeownership, each person’s income, and the lease terms. It is important to check both spouses’ circumstances together before filing their year-end tax returns.
Reference date: 2026-11-07
Content type: Website information on taxes and year-end tax settlement
Meta title: 2026 Rent Tax Credit: Separate-Residence Requirements for Spouses and the Combined Couple Limit
※ This article is for informational purposes to help readers understand market trends and is not a recommendation to invest in any particular stock or asset. You are responsible for your own final decisions and investments.