

Homeplus-Affected Small Businesses: Which In-Store Tenants and Suppliers Qualify for the 12-Month Policy Loan Repayment Deferral?
As of 2026-10-06, in-store tenants and suppliers affected by Homeplus are eligible for support if they hold small business policy loans and are currently repaying principal or have loans maturing within 2026. Eligible borrowers can extend their loan maturity by 12 months. During the deferral period, principal repayments are suspended, but interest payments must continue as usual.
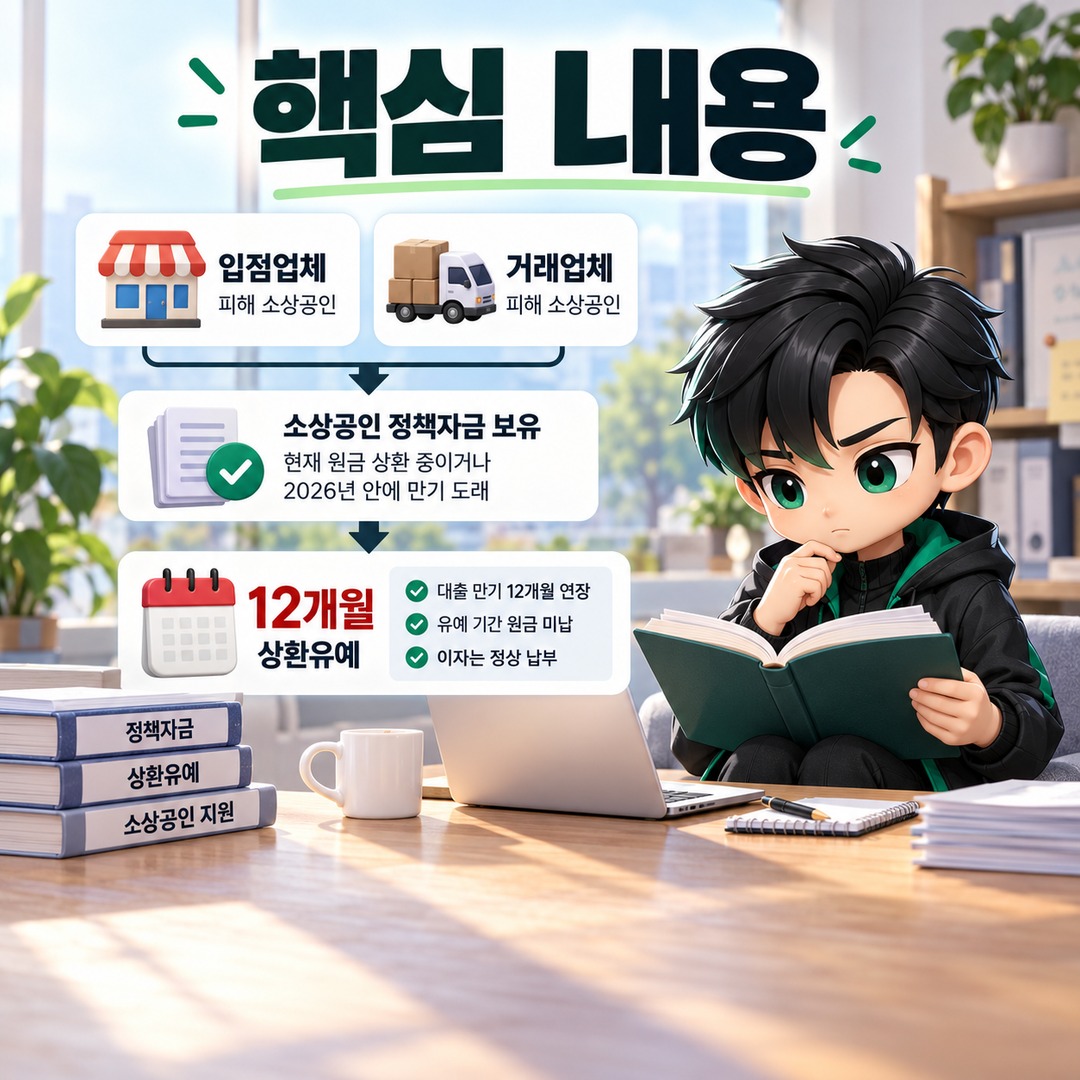
Therefore, assuming that only small businesses operating inside Homeplus stores qualify would be too narrow an interpretation. Small businesses that supplied goods or services to Homeplus and suffered losses may also qualify if they meet the requirements.
Homeplus Suppliers Are Eligible, Not Just In-Store Tenants
The first thing to check is not simply whether the business operated inside a Homeplus store. Both in-store tenants and suppliers affected by Homeplus are included within the scope of eligible businesses.
However, having a business relationship with Homeplus does not automatically qualify a company for the 12-month repayment deferral. The repayment status of its existing small business policy loans must also be checked.
Under the support criteria announced on 2026-10-06, the following two situations qualify:
The business is currently repaying the principal on a small business policy loan.
The business holds a small business policy loan that matures within 2026.
In other words, eligibility is determined by checking whether the business is an in-store tenant or supplier affected by Homeplus and whether it holds a policy loan currently undergoing principal repayment or maturing within the year.
The '1-Year Repayment Deferral' Does Not Mean Both Principal and Interest Payments Are Suspended
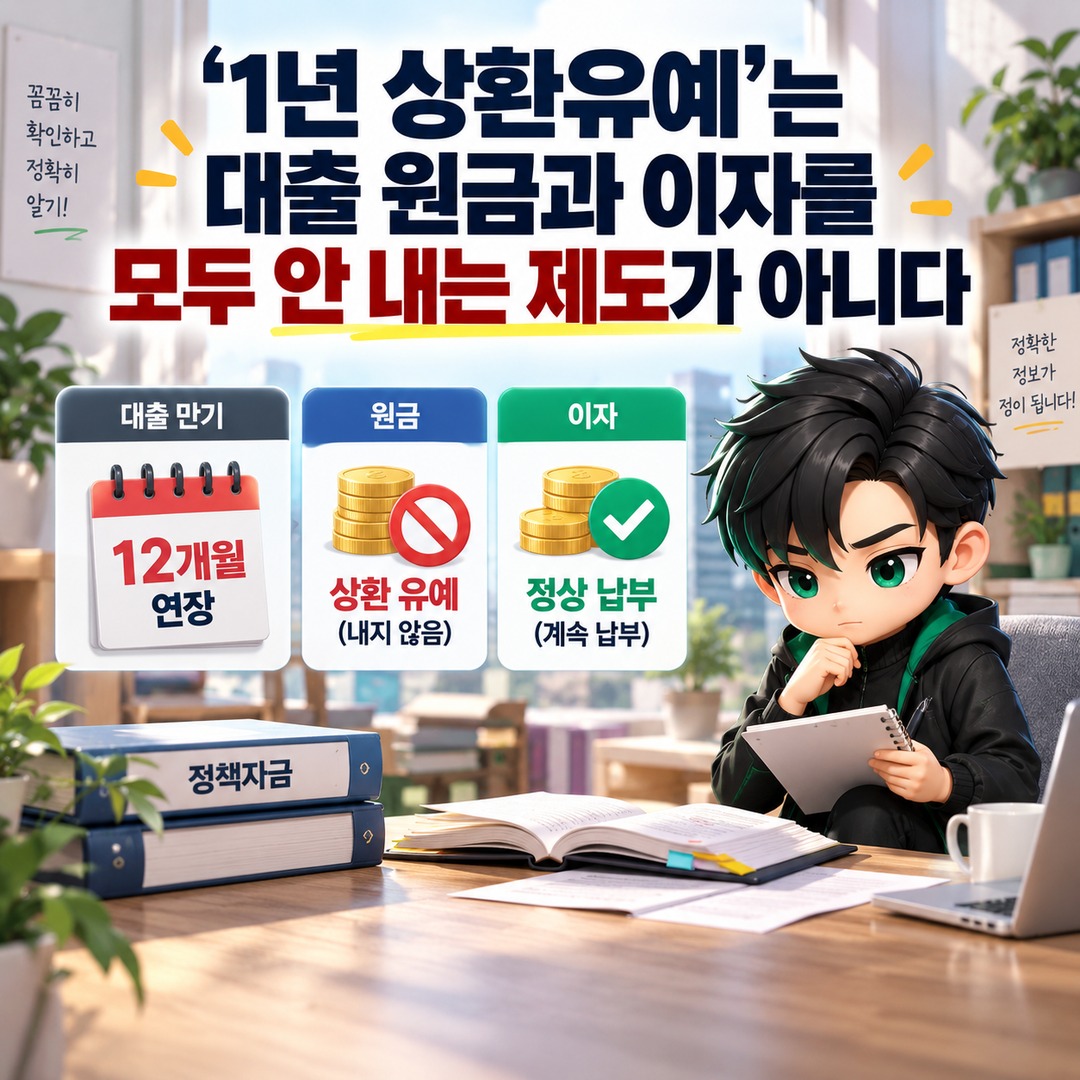
For eligible borrowers, the maturity date of an existing policy loan is extended by 12 months. Principal repayments are deferred during this period, but interest must still be paid.
Therefore, it would be incorrect to assume that borrowers do not have to make any loan payments for 1 years. More precisely, the program postpones principal repayments for 12 months while requiring interest to be paid as usual.
It is also important to distinguish between newly available emergency business stabilization loans and repayment deferrals on existing loans.
A separate Temporary Management Difficulties Fund has been available to small businesses affected by Homeplus. This program provides funding of up to KRW 100,000,000 at an interest rate 0.5% percentage points below the standard policy loan interest rate.
By contrast, the measure accepting applications from October 6 provides support by adjusting the maturity dates and principal repayment schedules of policy loans that borrowers already hold.
Businesses seeking new working capital and those wishing to postpone principal repayments on existing policy loans therefore need to review different support programs.
Application Procedures Differ for Direct Loans and Loans Through Financial Institutions
Applications can be submitted through the Small Business Policy Funds website starting 2026-10-06. However, the subsequent procedure differs depending on whether the borrower has a direct loan or a loan arranged through a financial institution.
Borrowers who obtained direct loans from the Korea SMEs and Startups Agency's small business support counterpart, the Small Enterprise and Market Service (SEMAS), can apply online and then enter into a revised loan agreement to receive a maturity extension and repayment deferral.
Borrowers with loans arranged through financial institutions must obtain a Certificate of Maturity Extension and Repayment Deferral from the Small Business Policy Funds website before proceeding with the remaining steps.
An additional step applies to loans backed by a guarantee certificate. Borrowers must first extend the guarantee period through the relevant guarantee institution and then apply for a maturity extension and repayment deferral at the financial institution that issued the loan.
Checking whether an existing policy loan is a direct loan or a loan arranged through a financial institution before applying will therefore make it easier to identify the required procedure.
Eligibility Is Not Limited to Businesses That Have Already Received New Emergency Funding
An important distinction in this measure is the difference between the new Temporary Management Difficulties Fund and existing policy loans.
Although emergency business stabilization funding for small businesses affected by Homeplus was previously expanded, the current maturity extension and repayment deferral measure is intended to ease the principal repayment burden on existing small business policy loans.
Therefore, it should not be assumed that only businesses that have newly received Homeplus-related emergency funding can qualify for the 12-month deferral. The currently published eligibility criteria focus on whether the applicant is an in-store tenant or supplier affected by Homeplus, together with the principal repayment and maturity status of its existing policy loans.
Three Things to Check Before Applying
Small business owners planning to apply should first confirm whether their business qualifies as an in-store tenant or supplier affected by Homeplus.
Next, they should check whether their existing small business policy loan is currently in the principal repayment stage or is scheduled to mature within 2026. Finally, identifying whether the loan is a direct loan or one arranged through a financial institution will help determine the appropriate application procedure.
Even eligible borrowers must continue paying interest during the deferral period. The conditions confirmed during the application process should be treated as the final basis for determining eligibility and whether the measure can actually be applied to an individual loan.