

Can You Join the Youth Future Savings Account After Waiting for Your Youth Leap Account to Mature? 2 Round Requires a Switch
If you already have a Youth Leap Account and also want to use the Youth Future Savings Account, waiting until your Youth Leap Account matures before applying is not currently permitted. According to Financial Services Commission guidance as of 2026-10-04, not only is simultaneous enrollment in both products prohibited, but joining the Youth Future Savings Account after the Youth Leap Account matures is also disallowed. Instead, during the 2 round of applications, existing Youth Leap Account holders will have another opportunity to switch through a special early termination procedure.
Can You Open a New Youth Future Savings Account After Your Youth Leap Account Matures?
Under the current rules, this is not permitted.
According to the Financial Services Commission's announcement regarding the 2 round of Youth Future Savings Account applications, simultaneous enrollment in the Youth Leap Account and Youth Future Savings Account is prohibited. Opening a Youth Future Savings Account after your Youth Leap Account has matured is also not permitted.
Therefore, the following options must be treated differently.
| Option | Eligibility for the Youth Future Savings Account |
|---|---|
| Keep the Youth Leap Account until maturity | New enrollment after maturity is not permitted |
| Meet the switching requirements during the 2 application round | Enrollment is possible |
| Maintain both the Youth Leap Account and Youth Future Savings Account simultaneously | Generally prohibited |
In other words, if you were thinking, "Why not collect all the benefits from my Youth Leap Account first and then join the Youth Future Savings Account?" you need to be careful. The current system is not designed to let participants receive the full benefits of both products consecutively.
Wouldn't Closing Your Youth Leap Account Early Mean Losing Money?
Special Early Termination for an Authorized Switch to the Youth Future Savings Account Is Different From Ordinary Early Termination
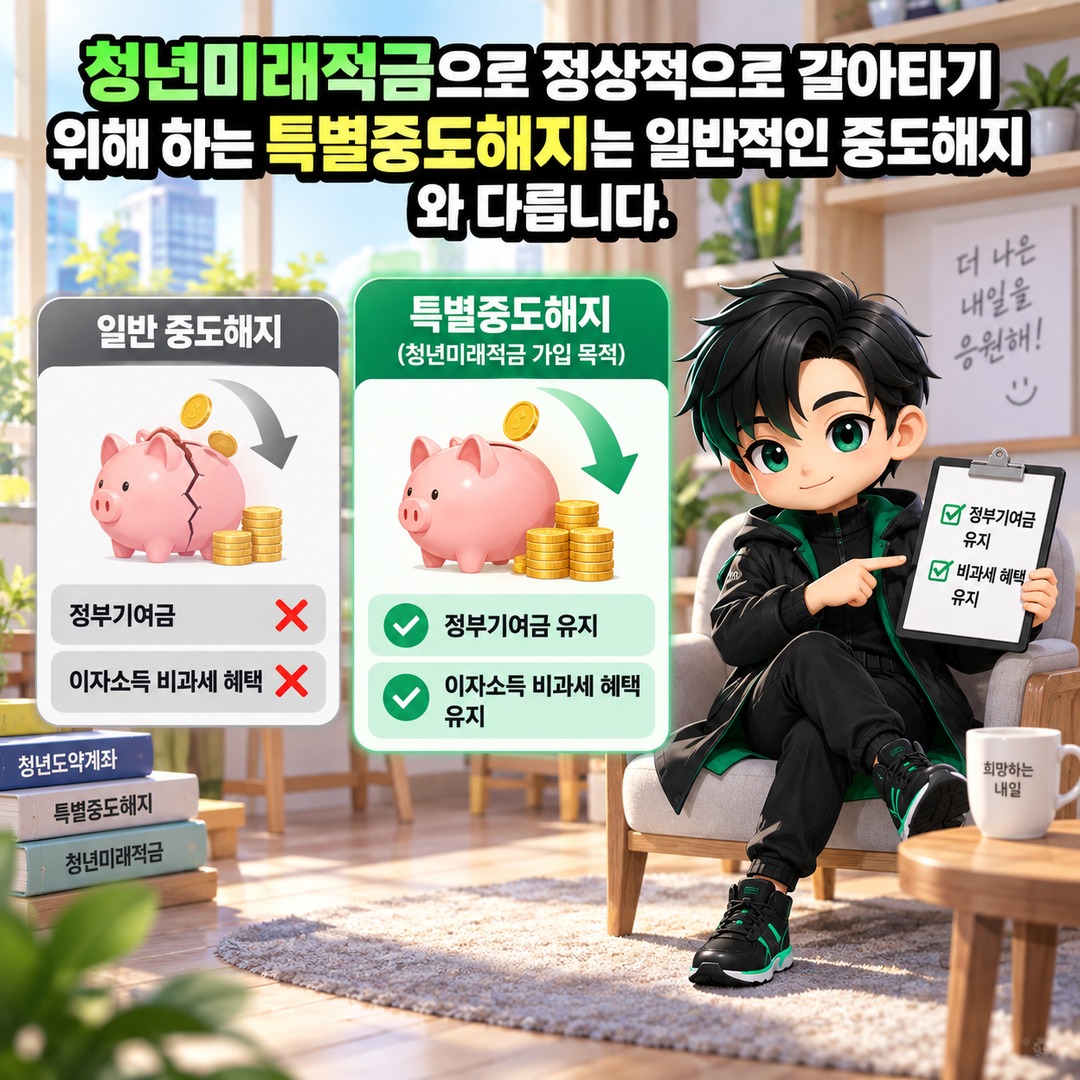
The Financial Services Commission explains that using the special early termination procedure to join the Youth Future Savings Account allows participants to retain the government contributions and income tax exemptions on interest applied to their existing Youth Leap Account deposits.
The key term here is "special early termination."
Voluntarily closing your Youth Leap Account before applying for the Youth Future Savings Account is not the same as using the special early termination procedure established by the government for switching between the two products.
Therefore, you should not automatically assume that early termination means losing every benefit you have received so far. At the same time, you should not assume that all financial outcomes will be identical to those of keeping your current account until maturity.
When making your decision, you need to compare how long you have contributed so far, your monthly contribution amount, the applicable interest rate, and whether you qualify for preferential interest rates.
When Should You Apply to Switch During the 2 Round?
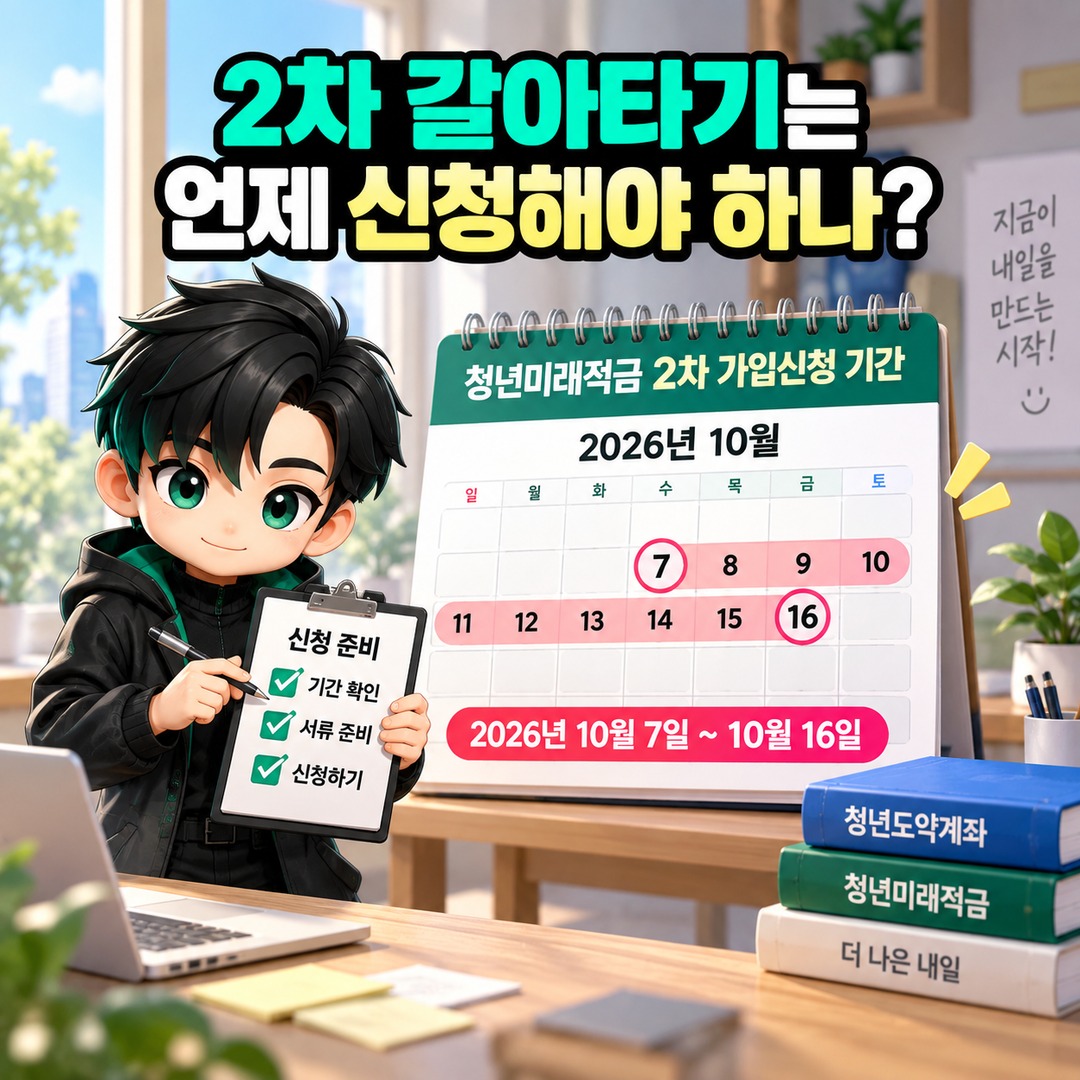
Applications for the 2 round of the Youth Future Savings Account will be accepted from 2026-10-07 through October 16.
On October 7, applicants whose birth years end in an odd digit may apply, while October 8 is reserved for those whose birth years end in an even digit. From October 12 through 16, applications will be accepted regardless of birth year.
Eligibility reviews are scheduled to take place from October 19 through November 13. Successful applicants will be able to open their accounts from November 16 through 27. The internal review schedule may change slightly depending on application volume.
Age eligibility for this 2 application round is determined as of the account opening date. The standard eligible age range is 19–34 years old, and this round covers people born from 1991-11-17 through 2007-11-27. Up to 6 years of military service may be excluded when calculating age eligibility.
If You've Held Your Youth Leap Account for a Long Time, Is Waiting Until Maturity Always Better?
Not necessarily.
The two products differ in both maturity periods and monthly contribution limits. According to the comparison provided by the Financial Services Commission, the Youth Future Savings Account allows monthly contributions of up to KRW 500,000 over 3 years, while the Youth Leap Account allows monthly contributions of up to KRW 700,000 over 5 years. Their maximum total principal contributions also differ significantly, at KRW 18,000,000 and KRW 42,000,000, respectively.
The government contribution structures also differ. The Youth Future Savings Account currently applies contribution matching rates of 6% for the standard tier and 12% for the preferential tier, while the Youth Leap Account applies rates ranging from 3 to 6% depending on income brackets.
Therefore, comparing only the advertised maximum return figures may produce results that differ from what you would actually receive.
For example, someone whose Youth Leap Account is approaching maturity and someone who opened an account recently have very different remaining contribution periods to give up. Government contributions under the Youth Future Savings Account also differ depending on whether an applicant qualifies for the standard or preferential tier.
Ultimately, there are four factors to compare.
How many months you have maintained your current Youth Leap Account
How much time remains until your Youth Leap Account matures
How much you can realistically contribute each month
Whether you qualify for the standard or preferential tier of the Youth Future Savings Account
In particular, the maximum annual return figures presented by the Financial Services Commission represent the equivalent interest rates of ordinary taxable savings products after accounting for government contributions, tax exemptions, and other benefits. They do not mean that individuals will receive those exact interest rates as interest credited directly to their accounts.
Why the Strategy of Collecting Your Maturity Payout First and Then Joining the Youth Future Savings Account Doesn't Work
The Youth Future Savings Account was not designed as a follow-up savings product into which participants can reinvest the maturity proceeds from their Youth Leap Accounts.
Under the current system, the transition mechanism available to existing Youth Leap Account holders is not to maintain the Youth Leap Account until maturity and then open a new account, but to undergo an eligibility review for the Youth Future Savings Account during the application period and switch through the special early termination procedure.
Missing this distinction could mean that deciding to "wait a little longer before making a decision" actually eliminates your opportunity to join the Youth Future Savings Account.
However, the Youth Future Savings Account program may change in the future. The Financial Services Commission has stated that if the government budget proposal covering expanded eligibility in 2027 and increased government contributions for the preferential tier is finalized following National Assembly deliberations, the relevant rules and screening system will be revised before the 3 application round proceeds. Because these proposals still require National Assembly review, they should not be treated as confirmed conditions.
Key Takeaways Before the October 2 Application Round
For people currently maintaining a Youth Leap Account, the most important point is not to assume that they can simply wait until maturity and then join the Youth Future Savings Account.
According to official guidance as of 2026-10-04, joining the Youth Future Savings Account after a Youth Leap Account matures is not permitted. To switch to the Youth Future Savings Account, applicants must undergo an eligibility review during the 2 application round, open their new account, and use the prescribed special early termination procedure for their existing Youth Leap Account.
However, this does not mean switching will necessarily be more financially advantageous for every account holder. The remaining contribution period, actual applicable interest rate, affordable monthly contribution amount, and eligibility for the standard or preferential tier of the Youth Future Savings Account vary from person to person. It is important to compare these factors based on your own circumstances before making a decision.
※ This article is provided for informational purposes to help readers understand market developments and does not constitute an investment recommendation for any specific security or asset. All final investment decisions and responsibilities rest with the individual.